
Treasury Regulations · 26 CFR
§ 1.801-8. Contracts with reserves based on segregated asset accounts.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 801
Cite as 26 CFR § 1.801-8
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- June 23, 1966 by T.D. 6886
- Last amended
- October 13, 2020 by T.D. 9911
- Issued under
- 26 U.S.C. § 801
- Length
- 3,279 words · about 14 min to read
- Defines
- 1 term
- Cross-references
- cites 8 Code sections and 7 regulations; cited by 0
(a) Which provides for the allocation of all or part of the amounts received under the contract to an account which, pursuant to State law or regulation, is segregated from the general asset accounts of the company,
(b) Which provides for the payment of annuities, and
(c) Under which the amounts paid in, or the amount paid as annuities, reflect the investment return and the market value of the segregated asset account.
A method of separate accounting for such items as are not accounted for directly will be deemed “regularly employed” by a life insurance company if the method was consistently followed in prior taxable years, or if, in the case of a company which has never before issued contracts with reserves based on segregated asset accounts, the company initiates in the first taxable year for which it issues such contracts a reasonable method of separate accounting for such items and consistently follows such method thereafter. Ordinarily, a company regularly employs a method of accounting in accordance with the statute of the State, Territory, or the District of Columbia, in which it operates.
Thus, for purposes of determining both taxable investment income and gain or loss from operations, a life insurance company shall separately compute the life insurance company's share of the investment yield on the assets in its segregated asset account without regard to the policy and other contract liability requirements of, and the investment income attributable to, contracts with reserves that are not based on the segregated asset account. Such separate computations shall be made after any allocation required under section 801(g)(4)(B) and subparagraph (2) of this paragraph.
For the taxable year 1962, T, a life insurance company which issues regular life insurance and annuity contracts and contracts with reserves based on segregated asset accounts, had (without regard to section 801(g)(4)(A)) realized short-term capital gains of $10,000 and short-term capital losses of $10,000 attributable to its general asset accounts and realized short-term capital gains of $12,000 attributable to its segregated asset accounts. For the taxable year 1962, the excess of the net short-term capital gain ($10,000 + $12,000−$10,000, or $12,000) over the net long-term capital loss (0) was $12,000. Of the excess of $12,000, 100 percent was contributed by the segregated asset accounts. Applying the provisions of section 801(g)(4)(B), T would allocate the entire $12,000 to its segregated asset accounts for such taxable year.
The facts are the same as in example 1 except that for the taxable year 1962, T had (without regard to section 801(g)(4)(A)) realized short-term capital losses of $8,000 attributable to its general asset accounts and realized long-term capital gains of $1,000 and long-term capital losses of $5,000 attributable to its segregated asset accounts. For the taxable year 1962, the excess of the net short-term capital gain ($10,000 + $12,000−$8,000, or $14,000) over the net long-term capital loss ($5,000−$1,000, or $4,000) was $10,000. Of the excess of $10,000, the general asset accounts contributed 20 percent ($2,000 ($10,000−$8,000) ÷ $10,000) and the segregated asset accounts contributed 80 percent ($8,000 ($12,000−$4,000) ÷ $10,000). Applying the provisions of section 801(g)(4)(B), T would allocate $2,000 ($10,000 × 20 percent) to its general asset accounts and $8,000 ($10,000 × 80 percent) to its segregated asset accounts for such taxable year.
W is a life insurance company which issues regular life insurance and annuity contracts and contracts with reserves based on either of two segregated asset accounts, Separate Account C or Separate Account D. For the taxable year 1962, W had (without regard to section 801(g)(4)(A)) realized short-term capital gains of $16,000 and long-term capital losses of $15,000 attributable to its general asset accounts, long-term capital gains of $12,000 and short-term capital losses of $6,000 attributable to Separate Account C and long-term capital gains of $7,000 and short-term capital losses of $5,000 attributable to Separate Account D. For the taxable year 1962, the excess of the net short-term capital gain ($16,000−$6,000−$5,000) over the net long-term capital loss (0) was $5,000. Of the $5,000 excess, 20 percent ($16,000−$15,000 ÷ $5,000) was contributed by the general asset accounts, leaving 80 percent as the amount contributed by the segregated asset accounts. Applying the provisions of section 801(g)(4)(B) W would allocate $1,000 (20 percent of $5,000) to the general asset accounts, leaving $4,000 (80 percent of $5,000) to be allocated among the segregated asset accounts, Separate Account C and Separate Account D. W would allocate $3,000 of the $4,000 to Separate Account C computed as follows:
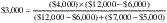
W would allocate $1,000 of the $4,000 to Separate Account D computed as follows:
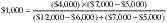
Company M, a life insurance company issuing only contracts with reserves based on segregated asset accounts as defined in section 801(g)(1)(B) and paragraph (a)(2) of this section (other than contracts described in section 805(d)(1) (A), (B), (C), or (D)), increased its life insurance reserves held with respect to such contracts during the taxable year 1962 by $275,000. Of the total increase in the reserves, $100,000 was attributable to premium receipts, $50,000 to dividends and interest, $100,000 to unrealized appreciation in the value of the assets held in relation to such reserves, and $25,000 to realized capital gains on the sale of such assets. As of the close of the taxable year 1962, the reserves held by company M with respect to all such contracts amounted to $1,275,000. However, under section 801(g)(6) and this subparagraph, this amount must be reduced by the $100,000 unrealized asset value appreciation and the $25,000 of realized capital gains. Accordingly, for purposes of section 810(a) and (b), the amount of these reserves which is to be taken into account as of the close of the taxable year 1962 under section 810(c) is $1,150,000 ($1,275,000 less $125,000). However, for purposes of section 810 (a) and (b), the amount of these reserves which is to be taken into account as of the beginning of the taxable year 1963 under section 810(c) is $1,275,000 (the amount as of the close of the taxable year 1962 before reduction of $125,000 for unrealized appreciation and realized capital gains).
On June 30, 1962, X, a life insurance company, reinsured a portion of its insurance contracts with reserves based on segregated asset accounts with Y, a life insurance company, under an agreement whereby Y agreed to assume and become solely liable under the contracts reinsured. The reserves on the contracts reinsured by X were $90,000, of which $10,000 was attributable to unrealized appreciation in the value of the assets held in relation to such reserves. However, no amounts had been added to the reserves by reason of the unrealized appreciation of $10,000 and consequently, the $10,000 was not reflected in adjustments to reserves under section 809(g)(6) or subparagraph (1) of this paragraph. Under the reinsurance agreement, X made a payment of $90,000 in cash to Y for assuming such contracts. Applying the provisions of section 809(d)(7), and assuming no other such reinsurance transactions by X during the taxable year, X would have an allowable deduction of $90,000 as a result of this payment on June 30, 1962. However, applying the provisions of section 801(g)(6) and this subparagraph, the actual deduction allowed would be $80,000 ($90,000 less $10,000). See section 806 (a) and § 1.806-3 for the adjustments in reserves and assets to be made by X and Y as a result of this transaction. For the treatment by Y of this $90,000 payment, see section 809(c)(1) and paragraph (a)(1)(i) of § 1.809-4.
[T.D. 6886, 31 FR 8681, June 23, 1966, as amended by T.D. 6970, 33 FR 12044, Aug. 24, 1968; T.D. 7501, 42 FR 42341, Aug. 23, 1977; T.D. 9911, 85 FR 64392, Oct. 13, 2020]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 801 Tax imposed
- § 301 Distributions of property
- § 805 General deductions
- § 804 Life insurance deductions
- § 1222 Other terms relating to capital gains and losses
- § 810 Repealed
- § 809 Repealed
- § 806 Repealed
Regulations it cites
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9911 (85 FR 64392)
- Amended by T.D. 7501 (42 FR 42341)
- Amended by T.D. 6970 (33 FR 12044)
- Issued by T.D. 6886 (31 FR 8681)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Definition; tax imposed
Nearby sections
- § 1.801-3 Definitions.
- § 1.801-4 Life insurance reserves.
- § 1.801-5 Total reserves.
- § 1.801-6 Adjustments in reserves for policy loans.
- § 1.801-8 Contracts with reserves based on segregated asset accounts.
- § 1.802-3 Tax imposed on life insurance companies.