
Treasury Regulations · 26 CFR
§ 1.902-1. Credit for domestic corporate shareholder of a foreign corporation for foreign income taxes paid by the foreign corporation.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 902
Cite as 26 CFR § 1.902-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- January 7, 1997 by T.D. 8708
- Last amended
- September 22, 2021 by T.D. 9954
- Issued under
- 26 U.S.C. § 902
- Length
- 12,365 words · about 54 min to read
- Defines
- 4 terms
- Cross-references
- cites 25 Code sections and 10 regulations; cited by 17
(i) Domestic corporation M owns 30 percent of the voting stock of foreign corporation A on January 1, 1991, and for all periods thereafter. Corporation A owns 40 percent of the voting stock of foreign corporation B on January 1, 1991, and continues to own that stock until June 1, 1991, when Corporation A sells its stock in Corporation B. Both Corporation A and Corporation B use the calendar year as the taxable year. Corporation B pays a dividend out of its post-1986 undistributed earnings to Corporation A, which Corporation A receives on February 16, 1991. Corporation A pays a dividend out of its post-1986 undistributed earnings to Corporation M, which Corporation M receives on January 20, 1992. Corporation M uses a fiscal year ending on June 30 as the taxable year.
(ii) On February 16, 1991, when Corporation B pays a dividend to Corporation A, Corporation M satisfies the 10 percent stock ownership requirement of paragraphs (a)(1) and (2) of this section with respect to Corporation A. Therefore, Corporation A is a first-tier corporation within the meaning of paragraph (a)(2) of this section and Corporation M is a domestic shareholder of Corporation A within the meaning of paragraph (a)(1) of this section. Also on February 16, 1991, Corporation B is a second-tier corporation within the meaning of paragraph (a)(3) of this section because Corporation A owns at least 10 percent of its voting stock, and the percentage of voting stock owned by Corporation M in Corporation A on February 16, 1991 (30 percent) multiplied by the percentage of voting stock owned by Corporation A in Corporation B on February 16, 1991 (40 percent) equals 12 percent. Corporation A shall be deemed to have paid foreign income taxes of Corporation B with respect to the dividend received from Corporation B on February 16, 1991.
(iii) On January 20, 1992, Corporation M satisfies the 10-percent stock ownership requirement of paragraphs (a)(1) and (2) of this section with respect to Corporation A. Therefore, Corporation A is a first-tier corporation within the meaning of paragraph (a)(2) of this section and Corporation M is a domestic shareholder within the meaning of paragraph (a)(1) of this section. Accordingly, for its taxable year ending on June 30, 1992, Corporation M is deemed to have paid a portion of the post-1986 foreign income taxes paid, accrued, or deemed to be paid, by Corporation A. Those taxes will include taxes paid by Corporation B that were deemed paid by Corporation A with respect to the dividend paid by Corporation B to Corporation A on February 16, 1991, even though Corporation B is no longer a second-tier corporation with respect to Corporations A and M on January 20, 1992, and has not been a second-tier corporation with respect to Corporations A and M at any time during the taxable years of Corporations A and M that include January 20, 1992.
As of December 31, 1991, and since its incorporation, foreign corporation A has owned 100 percent of the stock of foreign corporation B. Corporation B is not a controlled foreign corporation. Corporation B uses the calendar year as its taxable year, and its functional currency is the u. Assume 1u equals $1 at all relevant times. On April 1, 1992, Corporation B pays a 200u dividend to Corporation A and the ownership requirements of section 902(c)(3)(B) and paragraphs (a)(1) through (4) of this section are not met at that time. On July 1, 1992, domestic corporation M purchases 10 percent of the Corporation B stock from Corporation A and, for the first time, Corporation B meets the ownership requirements of section 902(c)(3)(B) and paragraph (a)(2) of this section. Corporation M uses the calendar year as its taxable year. Corporation B does not distribute any dividends to Corporation M during 1992. For its taxable year ending December 31, 1992, Corporation B has 500u of earnings and profits (after foreign taxes but before taking into account the 200u distribution to Corporation A) and pays 100u of foreign income taxes that is equal to $100. Pursuant to paragraph (a)(13)(i) of this section, Corporation B's post-1986 undistributed earnings and post-1986 foreign income taxes will include earnings and profits and foreign income taxes attributable to Corporation B's entire 1992 taxable year and all taxable years thereafter. Thus, the April 1, 1992, dividend to Corporation A will reduce post-1986 undistributed earnings to 300u (500u-200u) under paragraph (a)(9)(i) of this section. The foreign income taxes attributable to the amount distributed as a dividend to Corporation A will not be creditable because Corporation A is not a domestic shareholder. Post-1986 foreign income taxes, however, will be reduced by the amount of foreign taxes attributable to the dividend. Thus, as of the beginning of 1993, Corporation B has $60 ($100-[$100 × 40% (200u/500u)]) of post-1986 foreign income taxes. See paragraphs (a)(8)(i) and (b)(1) of this section.
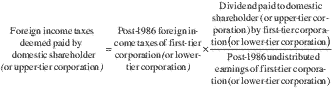
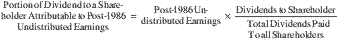
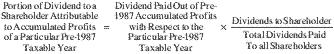
Domestic corporation M owns 100 percent of foreign corporation A. Both Corporation M and Corporation A use the calendar year as the taxable year, and Corporation A uses the u as its functional currency. Assume that 1u equals $1 at all relevant times. All of Corporation A's pre-1987 accumulated profits and post-1986 undistributed earnings are non-subpart F general limitation earnings and profits under section 904(d)(1)(I). As of December 31, 1992, Corporation A has 100u of post-1986 undistributed earnings and $40 of post-1986 foreign income taxes. For its 1986 taxable year, Corporation A has accumulated profits of 200u (net of foreign taxes) and paid 60u of foreign income taxes on those earnings. In 1992, Corporation A distributes 150u to Corporation M. Corporation A has 100u of post-1986 undistributed earnings and the dividend, therefore, is treated as paid out of post-1986 undistributed earnings to the extent of 100u. The first 100u distribution is from post-1986 undistributed earnings, and, because the distribution exhausts those earnings, Corporation M is deemed to have paid the entire amount of post-1986 foreign income taxes of Corporation A ($40). The remaining 50u dividend is treated as a dividend out of 1986 accumulated profits under paragraph (b)(2) of this section. Corporation M is deemed to have paid $15 (60u × 50u/200u, translated at the appropriate exchange rates) of Corporation A's foreign income taxes for 1986. As of January 1, 1993, Corporation A's post-1986 undistributed earnings and post-1986 foreign income taxes are 0. Corporation A has 150u of accumulated profits and 45u of foreign income taxes remaining in 1986.
Domestic corporation M (incorporated on January 1, 1987) owns 100 percent of foreign corporation A (incorporated on January 1, 1987). Both Corporation M and Corporation A use the calendar year as the taxable year, and Corporation A uses the u as its functional currency. Assume that 1u equals $1 at all relevant times. Corporation A has no pre-1987 accumulated profits. All of Corporation A's post-1986 undistributed earnings are non-subpart F general limitation earnings and profits under section 904(d)(1)(I). On January 1, 1992, Corporation A has a deficit in accumulated earnings and profits and a deficit in post-1986 undistributed earnings of (200u). No foreign taxes have been paid with respect to post-1986 undistributed earnings. During 1992, Corporation A earns 100u (net of foreign taxes), pays $40 of foreign taxes on those earnings and distributes 50u to Corporation M. As of the end of 1992, Corporation A has a deficit of (100u) ((200u) post1986 undistributed earnings + 100u current earnings and profits) in post-1986 undistributed earnings. Corporation A, however, has current earnings and profits of 100u. Therefore, the 50u distribution is treated as a dividend in its entirety under section 316(a)(2). Under paragraph (b)(4) of this section, Corporation M is not deemed to have paid any of the foreign taxes paid by Corporation A because post-1986 undistributed earnings and the sum of current plus accumulated earnings and profits are (100u). The dividend reduces both post-1986 undistributed earnings and accumulated earnings and profits. Therefore, as of January 1, 1993, Corporation A's post-1986 undistributed earnings are (150u) and its accumulated earnings and profits are (150u). Corporation A's post-1986 foreign income taxes at the start of 1993 are $40.
P, a domestic corporation, owns 40 percent of the voting stock of foreign corporation S. S owns 30 percent of the voting stock of foreign corporation T, and 30 percent of the voting stock of foreign corporation U. Neither S, T, nor U is a controlled foreign corporation. P, S, T and U all use the calendar year as their taxable year. In 1993, T and U both pay dividends to S and S pays a dividend to P. To compute foreign taxes deemed paid, paragraph (c)(1) of this section requires P to start with the lowest tier corporations and to compute foreign taxes deemed paid separately for dividends from each first-tier and lower-tier corporation. Thus, S first will compute foreign taxes deemed paid separately on its dividends from T and U. The deemed paid taxes will be added to S's post-1986 foreign income taxes, and the dividends will be added to S's post-1986 undistributed earnings. Next, P will compute foreign taxes deemed paid with respect to the dividend from S. This computation will take into account the taxes paid by T and U and deemed paid by S.
P, a domestic corporation, owns 100 percent of the voting stock of controlled foreign corporation S. Corporations P and S use the calendar year as their taxable year, and S uses the u as its functional currency. Assume that 1u equals $1 at all relevant times. As of January 1, 1992, S has -0- post-1986 undistributed earnings and -0- post-1986 foreign income taxes. In 1992, S earns 150u of non-subpart F general limitation income net of foreign taxes and pays 60u of foreign income taxes. As of the end of 1992, but before dividend payments, S has 150u of post-1986 undistributed earnings and $60 of post-1986 foreign income taxes. Assume that 50u of S's earnings for 1992 are from United States sources. S pays P a dividend of 75u which P receives in 1992. Under § 1.904-5(m)(4), one-third of the dividend, or 25u (75u × 50u/150u), is United States source income to P. P computes foreign taxes deemed paid on the dividend under paragraph (b)(1) of this section of $30 ($60 × 50%[75u/150u]) and includes that amount in gross income under section 78 as a dividend. Because 25u of the 75u dividend is United States source income to P, $10 ($30 × 33.33%[25u/75u]) of the section 78 dividend will be treated as United States source income to P under this paragraph (c)(2).
P, a domestic corporation, has owned 100 percent of the voting stock of foreign corporation S at all times since January 1, 1987. Until June 30, 2002, S owned 100 percent of the voting stock of foreign corporation T, T owned 100 percent of the voting stock of foreign corporation U, and U owned 100 percent of the voting stock of foreign corporation V. P, S, T, U, and V each use the calendar year as their U.S. taxable year. Thus, beginning in 1998 V was a fourth-tier controlled foreign corporation, and its foreign taxes paid or accrued in 1998 and later taxable years were eligible to be deemed paid. On June 30, 2002, T was liquidated, causing S to acquire 100 percent of the stock of U. As a result, V became a third-tier controlled foreign corporation. In 2003, V paid a dividend to U. Under paragraph (c)(8) of this section, foreign taxes paid by V in taxable years beginning before 1998 are not taken into account in computing the foreign taxes deemed paid with respect to the dividend paid by V to U.
Since 1987, domestic corporation M has owned 10 percent of the one class of stock of foreign corporation A. The remaining 90 percent of Corporation A's stock is owned by Z, a foreign corporation. Corporation A is not a controlled foreign corporation. Corporation A uses the u as its functional currency, and 1u equals $1 at all relevant times. Both Corporation A and Corporation M use the calendar year as the taxable year. In 1992, Corporation A pays a 30u dividend out of post-1986 undistributed earnings, 3u to Corporation M and 27u to Corporation Z. Corporation M is deemed, under paragraph (b) of this section, to have paid a portion of the post-1986 foreign income taxes paid by Corporation A and includes the amount of foreign taxes deemed paid in gross income under section 78 as a dividend. Both the foreign taxes deemed paid and the dividend would be subject to a separate limitation for dividends from Corporation A, a noncontrolled section 902 corporation. Under paragraph (a)(9)(i) of this section, Corporation A must reduce its post-1986 undistributed earnings as of January 1, 1993, by the total amount of dividends paid to Corporation M and Corporation Z in 1992. Under paragraph (a)(8)(i) of this section, Corporation A must reduce its post-1986 foreign income taxes as of January 1, 1993, by the amount of foreign income taxes that were deemed paid by Corporation M and by the amount of foreign income taxes that would have been deemed paid by Corporation Z had Corporation Z been eligible to compute an amount of foreign income taxes deemed paid with respect to the dividend received from Corporation A. Foreign income taxes deemed paid by Corporation M and Corporation A's opening balances in post-1986 undistributed earnings and post-1986 foreign income taxes for 1993 are computed as follows:
| 1. Assumed post-1986 undistributed earnings of Corporation A at start of 1992 | 25u |
| 2. Assumed post-1986 foreign income taxes of Corporation A at start of 1992 | $25 |
| 3. Assumed pre-tax earnings and profits of Corporation A for 1992 | 50u |
| 4. Assumed foreign income taxes paid or accrued by Corporation A in 1992 | 15u |
| 5. Post-1986 undistributed earnings in Corporation A for 1992 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | 60u |
| 6. Post-1986 foreign income taxes in Corporation A for 1992 (pre-dividend) (Line 2 plus Line 4 translated at the appropriate exchange rates) | $40 |
| 7. Dividends paid out of post-1986 undistributed earnings of Corporation A to Corporation M in 1992 | 3u |
| 8. Percentage of Corporation A's post-1986 undistributed earnings paid to Corporation M (Line 7 divided by Line 5) | 5% |
| 9. Foreign income taxes of Corporation A deemed paid by Corporation M under section 902(a) (Line 6 multiplied by Line 8) | $2 |
| 10. Total dividends paid out of post-1986 undistributed earnings of Corporation A to all shareholders in 1992 | 30u |
| 11. Percentage of Corporation A's post-1986 undistributed earnings paid to all shareholders in 1992 (Line 10 divided by Line 5) | 50% |
| 12. Post-1986 foreign income taxes paid with respect to post-1986 undistributed earnings distributed to all shareholders in 1992 (Line 6 multiplied by Line 11) | $20 |
| 13. Corporation A's post-1986 undistributed earnings at the start of 1993 (Line 5 minus Line 10) | 30u |
| 14. Corporation A's post-1986 foreign income taxes at the start of 1993 (Line 6 minus Line 12) | $20 |
(i) The facts are the same as in Example 1, except that Corporation M has also owned 10 percent of the one class of stock of foreign corporation B since 1987. Corporation B uses the calendar year as the taxable year. The remaining 90 percent of Corporation B's stock is owned by Corporation Z. Corporation B is not a controlled foreign corporation. Corporation B uses the u as its functional currency, and 1u equals $1 at all relevant times. In 1992, Corporation B has earnings and profits and pays foreign income taxes, a portion of which are attributable to high withholding tax interest, as defined in section 904(d)(2)(B)(i). Corporation B must reduce its pool of post-1986 foreign income taxes by the amount of tax imposed on high withholding tax interest in excess of 5 percent because that amount is not treated as a tax for purposes of section 902. See section 904(d)(2)(E)(ii) and paragraph (a)(8)(iii) of this section. Corporation B pays 50u in dividends in 1992, 5u to Corporation M and 45u to Corporation Z. Corporation M must compute its section 902(a) deemed paid taxes separately for the dividends it receives in 1992 from Corporation A (as computed in Example 1) and from Corporation B. Foreign income taxes of Corporation B deemed paid by Corporation M, and Corporation B's opening balances in post-1986 undistributed earnings and post-1986 foreign income taxes for 1993 are computed as follows:
| 1. Assumed post-1986 undistributed earnings of Corporation B at start of 1992 | (100u) |
| 2. Assumed post-1986 foreign income taxes of Corporation B at start of 1992 | $0 |
| 3. Assumed pre-tax earnings and profits of Corporation B for 1992 (including 50u of high withholding tax interest on which 5u of tax is withheld) | 302.50u |
| 4. Assumed foreign income taxes paid or accrued by Corporation B in 1992 | 102.50u |
| 5. Post-1986 undistributed earnings in Corporation B for 1992 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | 100u |
| 6. Amount of foreign income tax of Corporation B imposed on high withholding tax interest in excess of 5% (5u withholding tax—[5% × 50u high withholding tax interest]) | 2.50u |
| 7. Post-1986 foreign income taxes in Corporation B for 1992 (pre-dividend) (Line 2 plus [Line 4 minus Line 6 translated at the appropriate exchange rate]) | $100 |
| 8. Dividends paid out of post-1986 undistributed earnings to Corporation M in 1992 | 5u |
| 9. Percentage of Corporation B's post-1986 undistributed earnings paid to Corporation M (Line 8 divided by Line 5) | 5% |
| 10. Foreign income taxes of Corporation B deemed paid by Corporation M under section 902(a) (Line 7 multiplied by Line 9) | $5 |
| 11. Total dividends paid out of post-1986 undistributed earnings of Corporation B to all shareholders in 1992 | 50u |
| 12. Percentage of Corporation B's post-1986 undistributed earnings paid to all shareholders in 1992 (Line 11 divided by Line 5) | 50% |
| 13. Post-1986 foreign income taxes of Corporation B paid on or with respect to post-1986 undistributed earnings distributed to all shareholders in 1992 (Line 7 multiplied by Line 12) | $50 |
| 14. Corporation B's post-1986 undistributed earnings at start of 1993 (Line 5 minus Line 11) | 50u |
| 15. Corporation B's post-1986 foreign income taxes at start of 1993 (Line 7 minus Line 13) | $50 |
(ii) For 1992, as computed in Example 1, Corporation M is deemed to have paid $2 of the post-1986 foreign income taxes paid by Corporation A and includes $2 in gross income as a dividend under section 78. Both the income inclusion and the credit are subject to a separate limitation for dividends from Corporation A, a noncontrolled section 902 corporation. Corporation M also is deemed to have paid $5 of the post-1986 foreign income taxes paid by Corporation B and includes $5 in gross income as a deemed dividend under section 78. Both the income inclusion and the foreign taxes deemed paid are subject to a separate limitation for dividends from Corporation B, a noncontrolled section 902 corporation.
(i) Since 1987, domestic corporation M has owned 50 percent of the one class of stock of foreign corporation A. The remaining 50 percent of Corporation A is owned by foreign corporation Z. For the same time period, Corporation A has owned 40 percent of the one class of stock of foreign corporation B, and Corporation B has owned 30 percent of the one class of stock of foreign corporation C. The remaining 60 percent of Corporation B is owned by foreign corporation Y, and the remaining 70 percent of Corporation C is owned by foreign corporation X. Corporations A, B, and C are not controlled foreign corporations. Corporations A, B, and C use the u as their functional currency, and 1u equals $1 at all relevant times. Corporation B uses a fiscal year ending June 30 as its taxable year; all other corporations use the calendar year as the taxable year. On February 1, 1992, Corporation C pays a 500u dividend out of post-1986 undistributed earnings, 150u to Corporation B and 350u to Corporation X. On February 15, 1992, Corporation B pays a 300u dividend out of post-1986 undistributed earnings computed as of the close of Corporation B's fiscal year ended June 30, 1992, 120u to Corporation A and 180u to Corporation Y. On August 15, 1992, Corporation A pays a 200u dividend out of post-1986 undistributed earnings, 100u to Corporation M and 100u to Corporation Z. In computing foreign taxes deemed paid by Corporations B and A, section 78 does not apply and Corporations B and A thus do not have to include the foreign taxes deemed paid in earnings and profits. See paragraph (c)(2)(ii) of this section. Foreign income taxes deemed paid by Corporations B, A and M, and the foreign corporations' opening balances in post-1986 undistributed earnings and post-1986 foreign income taxes for Corporation B's fiscal year beginning July 1, 1992, and Corporation C's and Corporation A's 1993 calendar years are computed as follows:
| A. Corporation C (third-tier corporation): | |
| 1. Assumed post-1986 undistributed earnings in Corporation C at start of 1992 | 1300u |
| 2. Assumed post-1986 foreign income taxes in Corporation C at start of 1992 | $500 |
| 3. Assumed pre-tax earnings and profits of Corporation C for 1992 | 500u |
| 4. Assumed foreign income taxes paid or accrued in 1992 | 300u |
| 5. Post-1986 undistributed earnings in Corporation C for 1992 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | 1500u |
| 6. Post-1986 foreign income taxes in Corporation C for 1992 (pre-dividend) (Line 2 plus Line 4 translated at the appropriate exchange rates) | $800 |
| 7. Dividends paid out of post-1986 undistributed earnings of Corporation C to Corporation B in 1992 | 150u |
| 8. Percentage of Corporation C's post-1986 undistributed earnings paid to Corporation B (Line 7 divided by Line 5) | 10% |
| 9. Foreign income taxes of Corporation C deemed paid by Corporation B under section 902(b)(2) (Line 6 multiplied by Line 8) | $80 |
| 10. Total dividends paid out of post-1986 undistributed earnings of Corporation C to all shareholders in 1992 | 500u |
| 11. Percentage of Corporation C's post-1986 undistributed earnings paid to all shareholders in 1992 (Line 10 divided by Line 5) | 33.33% |
| 12. Post-1986 foreign income taxes paid with respect to post-1986 undistributed earnings distributed to all shareholders in 1992 (Line 6 multiplied by Line 11) | $266.66 |
| 13. Post-1986 undistributed earnings in Corporation C at start of 1993 (Line 5 minus Line 10) | 1000u |
| 14. Post-1986 foreign income taxes in Corporation C at start of 1993 (Line 6 minus Line 12) | $533.34 |
| B. Corporation B (second-tier corporation): | |
| 1. Assumed post-1986 undistributed earnings in Corporation B as of July 1, 1991 | 0 |
| 2. Assumed post-1986 foreign income taxes in Corporation B as of July 1, 1991 | 0 |
| 3. Assumed pre-tax earnings and profits of Corporation B for fiscal year ended June 30, 1992, (including 150u dividend from Corporation B) | 1000u |
| 4. Assumed foreign income taxes paid or accrued by Corporation B in fiscal year ended June 30, 1992 | 200u |
| 5. Foreign income taxes of Corporation C deemed paid by Corporation B in its fiscal year ended June 30, 1992 (Part A, Line 9 of paragraph (i) of this Example 3) | $80 |
| 6. Post-1986 undistributed earnings in Corporation B for fiscal year ended June 30, 1992 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | 800u |
| 7. Post-1986 foreign income taxes in Corporation B for fiscal year ended June 30, 1992 (pre-dividend) (Line 2 plus Line 4 translated at the appropriate exchange rates plus Line 5) | $280 |
| 8. Dividends paid out of post-1986 undistributed earnings of Corporation B to Corporation A on February 15, 1992 | 120u |
| 9. Percentage of Corporation B's post-1986 undistributed earnings for fiscal year ended June 30, 1992, paid to Corporation A (Line 8 divided by Line 6) | 15% |
| 10. Foreign income taxes paid and deemed paid by Corporation B as of June 30, 1992, deemed paid by Corporation A under section 902(b)(1) (Line 7 multiplied by Line 9) | $42 |
| 11. Total dividends paid out of post-1986 undistributed earnings of Corporation B for fiscal year ended June 30, 1992 | 300u |
| 12. Percentage of Corporation B's post-1986 undistributed earnings for fiscal year ended June 30, 1992, paid to all shareholders (Line 11 divided by Line 6) | 37.5% |
| 13. Post-1986 foreign income taxes paid and deemed paid with respect to post-1986 undistributed earnings distributed to all shareholders during Corporation B's fiscal year ended June 30, 1992 (Line 7 multiplied by Line 12) | $105 |
| 14. Post-1986 undistributed earnings in Corporation B as of July 1, 1992 (Line 6 minus Line 11) | 500u |
| 15. Post-1986 foreign income taxes in Corporation B as of July 1, 1992 (Line 7 minus Line 13) | $175 |
| C. Corporation A (first-tier corporation): | |
| 1. Assumed post-1986 undistributed earnings in Corporation A at start of 1992 | 250u |
| 2. Assumed post-1986 foreign income taxes in Corporation A at start of 1992 | $100 |
| 3. Assumed pre-tax earnings and profits of Corporation A for 1992 (including 120u dividend from Corporation B) | 250u |
| 4. Assumed foreign income taxes paid or accrued by Corporation A in 1992 | 100u |
| 5. Foreign income taxes paid or deemed paid by Corporation B as of June 30, 1992, that are deemed paid by Corporation A in 1992 (Part B, Line 10 of paragraph (i) of this Example 3) | $42 |
| 6. Post-1986 undistributed earnings in Corporation A for 1992 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | 400u |
| 7. Post-1986 foreign income taxes in Corporation A for 1992 (pre-dividend) (Line 2 plus Line 4 translated at the appropriate exchange rates plus Line 5) | $242 |
| 8. Dividends paid out of post-1986 undistributed earnings of Corporation A to Corporation M on August 15, 1992 | 100u |
| 9. Percentage of Corporation A's post-1986 undistributed earnings paid to Corporation M in 1992 (Line 8 divided by Line 6) | 25% |
| 10. Foreign income taxes paid and deemed paid by Corporation A in 1992 that are deemed paid by Corporation M under section 902(a) (Line 7 multiplied by Line 9) | $60.50 |
| 11. Total dividends paid out of post-1986 undistributed earnings of Corporation A to all shareholders in 1992 | 200u |
| 12. Percentage of Corporation A's post-1986 undistributed earnings paid to all shareholders in 1992 (Line 11 divided by Line 6) | 50% |
| 13. Post-1986 foreign income taxes paid and deemed paid by Corporation A with respect to post-1986 undistributed earnings distributed to all shareholders in 1992 (Line 7 multiplied by Line 12) | $121 |
| 14. Post-1986 undistributed earnings in Corporation A at start of 1993 (Line 6 minus Line 11) | 200u |
| 15. Post-1986 foreign income taxes in Corporation A at start of 1993 (Line 7 minus Line 13) | $121 |
(ii) Corporation M is deemed, under section 902(a) and paragraph (b) of this section, to have paid $60.50 of post-1986 foreign income taxes paid, or deemed paid, by Corporation A on or with respect to its post-1986 undistributed earnings (Part C, Line 10) and Corporation M includes that amount in gross income as a dividend under section 78. Both the income inclusion and the credit are subject to a separate limitation for dividends from Corporation A, a noncontrolled section 902 corporation.
(i) Since 1987, domestic corporation M has owned 100 percent of the voting stock of controlled foreign corporation A, and Corporation A has owned 100 percent of the voting stock of controlled foreign corporation B. Corporations M, A and B use the calendar year as the taxable year. Corporations A and B are organized in the same foreign country and use the u as their functional currency. 1u equals $1 at all relevant times. Assume that all of the earnings of Corporations A and B are general limitation earnings and profits within the meaning of section 904(d)(2)(I), and that neither Corporation A nor Corporation B has any previously taxed income accounts. In 1992, Corporation B pays a dividend of 150u to Corporation A out of post-1986 undistributed earnings, and Corporation A computes an amount of foreign taxes deemed paid under section 902(b)(1). The dividend is not subpart F income to Corporation A because section 954(c)(3)(B)(i) (the same country dividend exception) applies. Pursuant to paragraph (c)(2)(ii) of this section, Corporation A is not required to include the deemed paid taxes in earnings and profits. Corporation A has no pre-1987 accumulated profits and a deficit in post-1986 undistributed earnings for 1992. In 1992, Corporation A pays a dividend of 100u to Corporation M out of its earnings and profits for 1992 (current earnings and profits). Under paragraph (b)(4) of this section, Corporation M is not deemed to have paid any of the foreign income taxes paid or deemed paid by Corporation A because Corporation A has a deficit in post-1986 undistributed earnings as of December 31, 1992, and the sum of its current plus accumulated profits is less than zero. Note that if instead of paying a dividend to Corporation A in 1992, Corporation B had made an additional investment of $150 in United States property under section 956, that amount would have been included in gross income by Corporation M under section 951(a)(1)(B) and Corporation M would have been deemed to have paid $50 of foreign income taxes paid by Corporation B. See sections 951(a)(1)(B) and 960. Foreign income taxes of Corporation B deemed paid by Corporation A and the opening balances in post-1986 undistributed earnings and post-1986 foreign income taxes for Corporation A and Corporation B for 1993 are computed as follows:
| A. Corporation B (second-tier corporation): | |
| 1. Assumed post-1986 undistributed earnings in Corporation B at start of 1992 | 200u |
| 2. Assumed post-1986 foreign income taxes in Corporation B at start of 1992 | $50 |
| 3. Assumed pre-tax earnings and profits of Corporation B for 1992 | 150u |
| 4. Assumed foreign income taxes paid or accrued in 1992 | 50u |
| 5. Post-1986 undistributed earnings in Corporation B for 1992 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | 300u |
| 6. Post-1986 foreign income taxes in Corporation B for 1992 (pre-dividend) (Line 2 plus Line 4 translated at the appropriate exchange rates) | $100 |
| 7. Dividends paid out of post-1986 undistributed earnings of Corporation B to Corporation A in 1992 | 150u |
| 8. Percentage of Corporation B's post-1986 undistributed earnings paid to Corporation A (Line 7 divided by Line 5) | 50% |
| 9. Foreign income taxes of Corporation B deemed paid by Corporation A under section 902(b)(1) (Line 6 multiplied by Line 8) | $50 |
| 10. Post-1986 undistributed earnings in Corporation B at start of 1993 (Line 5 minus Line 7) | 150u |
| 11. Post-1986 foreign income taxes in Corporation B at start of 1993 (Line 6 minus Line 9) | $50 |
| B. Corporation A (first-tier corporation): | |
| 1. Assumed post-1986 undistributed earnings in Corporation A at start of 1992 | (200u) |
| 2. Assumed post-1986 foreign income taxes in Corporation A at start of 1992 | 0 |
| 3. Assumed pre-tax earnings and profits of Corporation A for 1992 (including 150u dividend from Corporation B) | 200u |
| 4. Assumed foreign income taxes paid or accrued by Corporation A in 1992 | 40u |
| 5. Foreign income taxes paid by Corporation B in 1992 that are deemed paid by Corporation A (Part A, Line 9 of paragraph (i) of this Example 4) | $50 |
| 6. Post-1986 undistributed earnings in Corporation A for 1992 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | (40u) |
| 7. Post-1986 foreign income taxes in Corporation A for 1992 (pre-dividend) (Line 2 plus Line 4 translated at the appropriate exchange rates plus Line 5) | $90 |
| 8. Dividends paid out of current earnings and profits of Corporation A for 1992 | 100u |
| 9. Percentage of post-1986 undistributed earnings of Corporation A paid to Corporation M in 1992 (Line 8 divided by the greater of Line 6 or zero) | 0 |
| 10. Foreign income taxes paid and deemed paid by Corporation A in 1992 that are deemed paid by Corporation M under section 902(a) (Line 7 multiplied by Line 9) | 0 |
| 11. Post-1986 undistributed earnings in Corporation A at start of 1993 (line 6 minus line 8) | (140u) |
| 12. Post-1986 foreign income taxes in Corporation A at start of 1993 (Line 7 minus Line 10) | $90 |
(ii) For 1993, Corporation A has 500u of earnings and profits on which it pays 160u of foreign income taxes. Corporation A receives no dividends from Corporation B, and pays a 100u dividend to Corporation M. The 100u dividend to Corporation M carries with it some of the foreign income taxes paid and deemed paid by Corporation A in 1992, which were not deemed paid by Corporation M in 1992 because Corporation A had no post-1986 undistributed earnings. Thus, for 1993, Corporation M is deemed to have paid $125 of post-1986 foreign income taxes paid and deemed paid by Corporation A and includes that amount in gross income as a dividend under section 78, determined as follows:
| 1. Post-1986 undistributed earnings in Corporation A at start of 1993 | (140u) |
| 2. Post-1986 foreign income taxes in Corporation A at start of 1993 | $90 |
| 3. Pre-tax earnings and profits of Corporation A for 1993 | 500u |
| 4. Foreign income taxes paid or accrued by Corporation A in 1993 | 160u |
| 5. Post-1986 undistributed earnings in Corporation A for 1993 (pre-dividend) (Line 1 plus Line 3 minus Line 4) | 200u |
| 6. Post-1986 foreign income taxes in Corporation A for 1993 (pre-dividend) (Line 2 plus Line 4 translated at the appropriate exchange rates) | $250 |
| 7. Dividends paid out of post-1986 undistributed earnings of Corporation A to Corporation M in 1993 | 100u |
| 8. Percentage of post-1986 undistributed earnings of Corporation A paid to Corporation M in 1993 (Line 7 divided by Line 5) | 50% |
| 9. Foreign income taxes paid and deemed paid by Corporation A that are deemed paid by Corporation M in 1993 (Line 6 multiplied by Line 8) | $125 |
| 10. Post-1986 undistributed earnings in Corporation A at start of 1994 (Line 5 minus Line 7) | 100u |
| 11. Post-1986 foreign income taxes in Corporation A at start of 1994 (Line 6 minus Line 9) | $125 |
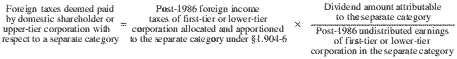
(i) Since 1987, domestic corporation M has owned 100 percent of the voting stock of controlled foreign corporation A. Corporation M also conducts operations through a foreign branch. Both Corporation A and Corporation M use the calendar year as the taxable year. Corporation A uses the u as its functional currency and 1u equals $1 at all relevant times. Corporation A has no subpart F income, as defined in section 952, and no increase in earnings invested in United States property under section 956 for 1992. Corporation A also has no previously taxed income accounts. Corporation A has general limitation income and high withholding tax interest income that, by operation of section 954(b)(4), does not constitute foreign base company income under section 954(a). Because Corporation A is a controlled foreign corporation, it is not required to reduce post-1986 foreign income taxes by foreign taxes paid or accrued with respect to high withholding tax interest in excess of 5 percent. See § 1.902-1(a)(8)(iii). Corporation A pays a 60u dividend to Corporation M in 1992. For 1992, Corporation M is deemed, under paragraph (b) of this section, to have paid $24 of the post-1986 foreign income taxes paid by Corporation A and includes that amount in gross income under section 78 as a dividend, determined as follows:
| 1. Assumed post-1986 undistributed earnings in Corporation A at start of 1992 attributable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest | 20u |
| (b) Section 904(d)(1)(I) general limitation income | 55u |
| 2. Assumed post-1986 foreign income taxes in Corporation A at start of 1992 attributable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest | $5 |
| (b) Section 904(d)(1)(I) general limitation income | $20 |
| 3. Assumed pre-tax earnings and profits of Corporation A for 1992 attributable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest | 20u |
| (b) Section 904(d)(1)(I) general limitation income | 20u |
| 4. Assumed foreign income taxes paid or accrued in 1992 on or with respect to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest | 10u |
| (b) Section 904(d)(1)(I) general limitation income | 5u |
| 5. Post-1986 undistributed earnings in Corporation A for 1992 (pre-dividend) attributable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest (Line 1(a) + Line 3(a) minus Line 4(a)) | 30u |
| (b) Section 904(d)(1)(I) general limitation income (Line 1(b) + Line 3(b) minus Line 4(b)) | 70u |
| (c) Total | 100u |
| 6. Post-1986 foreign income taxes in Corporation A for 1992 (pre-dividend) attributable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest (Line 2(a) + Line 4(a) translated at the appropriate exchange rates) | $15 |
| (b) Section 904(d)(1)(I) general limitation income (Line 2(b) + Line 4(b) translated at the appropriate exchange rates) | $25 |
| 7. Dividends paid to Corporation M in 1992 | 60u |
| 8. Dividends paid to Corporation M in 1992 attributable to section 904(d) separate categories pursuant to § 1.904-5(d): | |
| (a) Dividends paid to Corporation M in 1992 attributable to section 904(d)(1)(B) high withholding tax interest (Line 7 multiplied by Line 5(a) divided by Line 5(c)) | 18u |
| (b) Dividends paid to Corporation M in 1992 attributable to section 904(d)(1)(I) general limitation income (Line 7 multiplied by Line 5(b) divided by Line 5(c)) | 42u |
| 9. Percentage of Corporation A's post-1986 undistributed earnings for 1992 paid to Corporation M attributable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest (Line 8(a) divided by Line 5(a)) | 60% |
| (b) Section 904(d)(1)(I) general limitation income (Line 8(b) divided by Line 5(b)) | 60% |
| 10. Foreign income taxes of Corporation A deemed paid by Corporation M under section 902(a) attributable to: | |
| (a) Foreign income taxes of Corporation A deemed paid by Corporation M under section 902(a) with respect to section 904(d)(1)(B) high withholding tax interest (Line 6(a) multiplied by Line 9(a)) | $9 |
| (b) Foreign income taxes of Corporation A deemed paid by Corporation M under section 902(a) with respect to section 904(d)(1)(I) general limitation income (Line 6(b) multiplied by Line 9(b)) | $15 |
| 11. Post-1986 undistributed earnings in Corporation A at start of 1993 attributable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest (Line 5(a) minus Line 8(a)) | 12u |
| (b) Section 904(d)(1)(I) general limitation income (Line 5(b) minus Line 8(b)) | 28u |
| 12. Post-1986 foreign income taxes in Corporation A at start of 1989 allocable to: | |
| (a) Section 904(d)(1)(B) high withholding tax interest (Line 6(a) minus Line 10(a)) | $6 |
| (b) Section 904(d)(1)(I) general limitation income (Line 6(b) minus Line 10(b)) | $10 |
(ii) For purposes of computing Corporation M's foreign tax credit limitation, the post-1986 foreign income taxes of Corporation A deemed paid by Corporation M with respect to income in separate categories will be added to the foreign income taxes paid or accrued by Corporation M associated with income derived from Corporation M's branch operation in the same separate categories. The dividend (and the section 78 inclusion with respect to the dividend) will be treated as income in separate categories and added to Corporation M's other income, if any, attributable to the same separate categories. See section 904(d) and § 1.904-6.
[T.D. 8708, 62 FR 928, Jan. 7, 1997, as amended by T.D. 8916, 66 FR 274, Jan. 3, 2001; T.D. 9260, 71 FR 24526, Apr. 25, 2006; 71 FR 77264, Dec. 26, 2006; T.D. 9452, 74 FR 27875, June 11, 2009; T.D. 9954, 86 FR 52614, Sept. 22, 2021]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 902 Repealed
- § 1361 S corporation defined
- § 861 Income from sources within the United States
- § 957 Controlled foreign corporations; United States persons
- § 951 Amounts included in gross income of United States shareholders
- § 903 Credit for taxes in lieu of income, etc., taxes
- § 901 Taxes of foreign countries and of possessions of United States
- § 304 Redemption through use of related corporations
- § 441 Period for computation of taxable income
- § 904 Limitation on credit
- § 964 Miscellaneous provisions
- § 959 Exclusion from gross income of previously taxed earnings and profits
- § 1293 Current taxation of income from qualified electing funds
- § 952 Subpart F income defined
- § 953 Insurance income
- § 316 Dividend defined
- § 302 Distributions in redemption of stock
- § 301 Distributions of property
- § 1291 Interest on tax deferral
- § 78 Gross up for deemed paid foreign tax credit
- § 960 Deemed paid credit for subpart F inclusions
- § 907 Special rules in case of foreign oil and gas income
- § 6038 Information reporting with respect to certain foreign corporations and partnerships
- § 954 Foreign base company income
Regulations it cites
- § 1.902-2 Treatment of deficits in post-1986 undistributed earnings and pre-1987 accumulated profits of a first- or lower-tier corporation for purposes of computing an amount of foreign taxes deemed paid under § 1.902-1.
- § 1.901-2 Income, war profits, or excess profits tax paid or accrued.
- § 1.904-7 Transition rules.
- § 1.904-4 Separate application of section 904 with respect to certain categories of income.
- § 1.904-6 Allocation and apportionment of foreign income taxes.
- § 1.902-3 Credit for domestic corporate shareholder of a foreign corporation for foreign income taxes paid with respect to accumulated profits of taxable years of the foreign corporation beginning before January 1, 1987.
- § 1.301-1 Rules applicable with respect to distributions of money and other property.
- § 1.904-5 Look-through rules as applied to controlled foreign corporations and other entities.
- § 1.901-3 Reduction in amount of foreign taxes on foreign mineral income allowed as a credit.
- § 1.905-2 Conditions of allowance of credit.
Cited by 17 other regulations
- § 1.367(b)-2 Definitions and special rules.
- § 1.367(b)-7 Carryover of earnings and profits and foreign income taxes in certain foreign-to-foreign nonrecognition transactions.
- § 1.535-2 Adjustments to taxable income.
- § 1.545-2 Adjustments to taxable income.
- § 1.901-3 Reduction in amount of foreign taxes on foreign mineral income allowed as a credit.
- § 1.901(m)-8 Miscellaneous.
- § 1.902-0 Outline of regulations provisions for section 902.
- § 1.902-2 Treatment of deficits in post-1986 undistributed earnings and pre-1987 accumulated profits of a first- or lower-tier corporation for purposes of computing an amount of foreign taxes deemed paid under § 1.902-1.
- § 1.902-3 Credit for domestic corporate shareholder of a foreign corporation for foreign income taxes paid with respect to accumulated profits of taxable years of the foreign corporation beginning before January 1, 1987.
- § 1.902-4 Rules for distributions attributable to accumulated profits for taxable years in which a first-tier corporation was a less developed country corporation.
- § 1.904-7 Transition rules.
- § 1.905-5 Foreign tax redeterminations of foreign corporations that relate to taxable years of the foreign corporation beginning before January 1, 2018.
- § 1.907(c)-2 Section 907(c)(3) items (for taxable years beginning after December 31, 1982).
- § 1.909-1 Definitions and special rules.
- § 1.909-2 Splitter arrangements.
- § 1.985-7 Adjustments required in connection with a change to DASTM.
- § 1.985-8 Special rules applicable to the European Monetary Union (conversion to euro).
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9954 (86 FR 52614)
- Amended by T.D. 9452 (74 FR 27875)
- Amended (71 FR 77264)
- Amended by T.D. 9260 (71 FR 24526)
- Amended by T.D. 8916 (66 FR 274)
- Issued by T.D. 8708 (62 FR 928)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Foreign tax credit
Nearby sections
- § 1.901(m)-6 Successor rules.
- § 1.901(m)-7 De minimis rules.
- § 1.901(m)-8 Miscellaneous.
- § 1.902-0 Outline of regulations provisions for section 902.
- § 1.902-1 Credit for domestic corporate shareholder of a foreign corporation for foreign income taxes paid by the foreign corporation.
- § 1.902-2 Treatment of deficits in post-1986 undistributed earnings and pre-1987 accumulated profits of a first- or lower-tier corporation for purposes of computing an amount of foreign taxes deemed paid under § 1.902-1.
- § 1.902-3 Credit for domestic corporate shareholder of a foreign corporation for foreign income taxes paid with respect to accumulated profits of taxable years of the foreign corporation beginning before January 1, 1987.
- § 1.902-4 Rules for distributions attributable to accumulated profits for taxable years in which a first-tier corporation was a less developed country corporation.
- § 1.903-1 Taxes in lieu of income taxes.