
Treasury Regulations · 26 CFR
§ 1.1375-1. Tax imposed when passive investment income of corporation having subchapter C earnings and profits exceed 25 percent of gross receipts.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 1375
Cite as 26 CFR § 1.1375-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- September 26, 1986 by T.D. 8104
- Last amended
- May 29, 1992 by T.D. 8419
- Issued under
- 26 U.S.C. § 1375
- Length
- 1,415 words · about 6 min to read
- Defines
- 5 terms
- Cross-references
- cites 8 Code sections and 1 regulation; cited by 1
If the S corporation has no subchapter C earnings and profits at the close of the taxable year (because, for example, such earnings and profits were distributed in accordance with section 1368), the tax shall not be imposed even though the S corporation has passive investment income for the taxable year. If the tax is imposed, the tax shall be computed by multiplying the excess net passive income (as defined in paragraph (b) of this section) by the highest rate of tax specified in section 11(b).
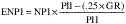
Where:
ENPI = excess net passive income
NPI = net passive income
PII = passive investment income
GR = total gross receipts
the amount of such gain taken into account under section 1374(b) and § 1.1374-1(b) (1) and (2) in determining the amount of tax shall be reduced by the portion of the excess net passive income for the taxable year which is attributable (on a pro rata basis) to such gain. For purposes of the preceding sentence, the portion of excess net passive income for the taxable year which is attributable to such capital gain is equal to the amount determined by multiplying the excess net passive income by the following fraction:

Where:
NCG = net capital gain
NPI = net passive income.
E = Expense attributable to net capital gain.
the Commissioner may waive the tax imposed by section 1375 for such taxable year. The S corporation has the burden of establishing that under the relevant facts and circumsances the Commissioner should waive the tax.
For example, if an S corporation establishes that in good faith and using due diligence it determined that it had no subchapter C earnings and profits at the close of a taxable year, but it was later determined on audit that it did have subchapter C earnings and profits at the close of such taxable year, and if the corporation establishes that it distributed such earnings and profits within a reasonable time after the audit, it may be appropriate for the Commissioner to waive the tax on passive income for such taxable year.
Assume Corporation M, an S corporation, has for its taxable year total gross receipts of $200,000, passive investment income of $100,000, $60,000 of which is interest income, and expenses directly connected with the production of such interest income in the amount of $10,000. Assume also that at the end of the taxable year Corporation M has subchapter C earnings and profits. Since more than 25 percent of the Corporation M's total gross receipts are passive investment income, and since Corporation M has subchapter C earnings and profits at the end of the taxable year, Corporation M will be subject to the tax imposed by section 1375. The amount of excess net passive investment income is $45,000 ($90,000 × (50,000 / 100,000)). Assume that the other $40,000 of passive investment income is attributable to net capital gain and that there are no expenses directly connected with such gain. Under these facts, $20,000 of the excess net passive income is attributable to the net capital gain ($45,000 × ($40,000 / $90,000)). Accordingly, the amount of gain taken into account under section 1374(b)(1) and the taxable income of Corporation M under section 1374(b)(2) shall be reduced by $20,000.
Assume an S corporation with subchapter C earnings and profits has tax-exempt income of $400, its only passive income, gross receipts of $1,000 and taxable income of $250 and there are no expenses associated with the tax-exempt income. The corporation's excess net income for the taxable year would total $150 (400 × ((400 − 250 / 400)). This amount is subject to the tax imposed by section 1375, notwithstanding that such amount is otherwise tax-exempt income.
[T.D. 8104, 51 FR 34203, Sept. 26, 1986; 52 FR 9162, Mar. 23, 1987. Redesignated and amended by T.D. 8419, 57 FR 22653, May 29, 1992]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 1375 Tax imposed when passive investment income of corporation having accumulated earnings and profits exceeds 25 percent of gross receipts
- § 1362 Election; revocation; termination
- § 1368 Distributions
- § 11 Tax imposed
- § 1374 Tax imposed on certain built-in gains
- § 172 Net operating loss deduction
- § 34 Certain uses of gasoline and special fuels
- § 1366 Pass-thru of items to shareholders
Regulations it cites
Cited by 1 other regulation
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 8419 (57 FR 22653)
- Amended (52 FR 9162)
- Issued by T.D. 8104 (51 FR 34203)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Small Business Corporations and Their Shareholders
Nearby sections
- § 1.1374-7 Inventory.
- § 1.1374-8 Section 1374(d)(8) transactions.
- § 1.1374-9 Anti-stuffing rule.
- § 1.1374-10 Effective date and additional rules.
- § 1.1375-1 Tax imposed when passive investment income of corporation having subchapter C earnings and profits exceed 25 percent of gross receipts.
- § 1.1377-0 Table of contents.
- § 1.1377-1 Pro rata share.
- § 1.1377-2 Post-termination transition period.
- § 1.1377-3 Applicability dates.