
Treasury Regulations · 26 CFR
§ 1.367(a)-6T. Transfer of foreign branch with previously deducted losses (temporary).
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 367(a)
Cite as 26 CFR § 1.367(a)-6T
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- May 16, 1986 by T.D. 8087
- Last amended
- December 16, 2016 by T.D. 9803
- Issued under
- 26 U.S.C. § 367(a)
- Length
- 4,133 words · about 18 min to read
- Defines
- 3 terms
- Cross-references
- cites 10 Code sections and 1 regulation; cited by 7
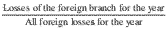
For purposes of this fraction, the term losses of the foreign branch for the year means the losses of the foreign branch that were taken into account under section 904(f)(2) in determining the amount of the transferor's overall foreign loss for the year, and the term all foreign losses for the year means all of the losses of the transferor that were taken into account under section 904(f)(2).
(i) Facts. X, a U.S. corporation, is a calendar year taxpayer. On January 1, 1981, X established a branch in foreign country A to manufacture and sell X's products in country A. On July 1, 1986, X organized corporation Y, a country A subsidiary, and transferred to Y all of the assets of its country A branch, including goodwill and going concern value. During the period from January 1, 1981, through July 1, 1986, X's country A branch earned income and incurred losses in the following amounts:
| Year | Ordinary income (loss) | Capital gain (loss) |
|---|---|---|
| 1981 | (200) | 0 |
| 1982 | (300) | (100) |
| 1983 | (400) | 0 |
| 1984 | (200) | 0 |
| 1985 | (100) | 0 |
| 1986 | 50 | 0 |
At the time of the transfer of X's country A branch assets to Y, those assets had a fair market value of $2,500 and an adjusted basis of $1,000. For each of the assets, fair market value exceeded adjusted basis. X had no net capital loss or unused investment credit during any taxable year relevant to the transfer. In 1984, X incurred a net operating loss of $400, $200 of which was carried back to prior years. An additional $50 of the 1984 net operating loss was carried over to 1985. The remaining $150 of the 1984 net operating loss was not used in any year prior to the transfer. In 1979, X paid creditable foreign taxes of $330 that could not be claimed as a credit in that year or any earlier year because of section 904. Of those foreign taxes, $100 were carried over and claimed as a credit in 1983, but the remaining $230 were not used in any year prior to the transfer. X was not required to recognize any gain under section 904(f)(3) on account of the 1986 transfer or any prior transfer. X was not required to recognize gain upon the transfer under section 367(a) (other than by reason of the provisions of this section).
(ii) Previously deducted losses. The previously deducted losses of X's country A branch are $575 of ordinary losses and $25 of capital losses, computed as follows: Initially, the branch has previously deducted ordinary losses of $1,000 ($200 + $300 + $400 + $100), and previously deducted capital losses of $100. (See paragraph (d)(1) of this section.)
(iii) Expired losses and credits. Under the facts of this example, there are no reductions for expired net ordinary losses or expired net capital losses under paragraph (d)(2) or (3) of this section. However, the previously deducted losses are reduced proceeding from the first branch loss year to the last branch loss year to reflect the expired foreign tax credit from 1979. The amount of the foreign tax credit loss equivalent with respect to 1981 is $500 ($230/.46). It reduces the previously deducted losses for 1981 proportionately. Thus, the previously deducted ordinary loss for 1981 is reduced from $200 to $0. (See paragraph (d)(4) of this section.) The amount of the foreign tax credit loss equivalent with respect to 1982 is $300 ($500−$200, i.e., $138/.46). (See paragraph (d)(4)(ii)(C) of this section.) It reduces the previously deducted losses for 1982 proportionately. Thus, the previously deducted ordinary loss for 1982 is reduced from $300 to $75, and the previously deducted capital loss for 1982 is reduced from $100 to $25.
(iv) Further reductions. The previously deducted ordinary losses of $575 and the previously deducted capital losses of $25 are reduced by the taxable income earned by the branch prior to the date of the transfer ($250). (See paragraph (e)(2) of this section.) Since that income was ordinary income, it is applied first to reduce the previously deducted ordinary losses of $575 to $325. (See paragraph (e)(1) of this section.)
(v) Recapture. Since the gain realized by X upon its transfer of the branch assets to Y exceeds the sum of the previously deducted branch losses as defined and reduced above $325 + $25), the limitation in paragraph (c)(2) of this section does not apply. Thus, X is required to recognize $325 of ordinary income and $25 of long-term capital gain upon the transfer. (See paragraph (b) and (c)(1) of this section.)
Notwithstanding the preceding rule of this paragraph (g)(3), gains of a foreign branch of a domestic corporation arising in a year in which that corporation did not file a consolidated return with a second domestic corporation shall not be applied to reduce the previously deducted losses of a foreign branch of the second corporation (but may be applied to reduce such losses of the foreign branch of the first corporation) upon the transfer of the two branches to a foreign corporation, even though the two domestic corporations file a consolidated return for the year in which the transfer occurs and the two branches are considered at that time to constitute a single foreign branch. For an example of the application of the principles of this paragraph (g)(3), see Revenue Ruling 81-89, 1981-1 C.B. 129.
Then, solely for purposes of this section, that U.S. person shall be treated as having transferred the property of the branch directly to the foreign corporation. A U.S. person shall be presumed to have transferred property of a foreign branch for a principal purpose of avoiding the effect of this section if the property is transferred to the domestic corporation less than two years prior to the domestic corporation's transfer of the property to a foreign corporation. This presumption may be rebutted by clear evidence that the subsequent transfer of the property was not contemplated at the time of the initial transfer to the domestic corporation and that avoidance of the effect of this section was not a principal purpose for the transaction. A transfer may have more than one principal purpose.
[T.D. 8087, 51 FR 17950, May 16, 1986, as amended by T.D. 9615, 78 FR 17063, Mar. 19, 2013; T.D. 9760, 81 FR 15169, Mar. 22, 2016; T.D. 9803, 81 FR 91028, Dec. 16, 2016]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 367 Foreign corporations
- § 907 Special rules in case of foreign oil and gas income
- § 172 Net operating loss deduction
- § 1222 Other terms relating to capital gains and losses
- § 1212 Capital loss carrybacks and carryovers
- § 902 Repealed
- § 904 Limitation on credit
- § 46 Amount of credit
- § 39 Carryback and carryforward of unused credits
- § 38 General business credit
Regulations it cites
Cited by 7 other regulations
- § 1.367(a)-3 Treatment of transfers of stock or securities to foreign corporations.
- § 1.367(a)-6 Transfer of foreign branch with previously deducted losses.
- § 1.954-1 Foreign base company income.
- § 1.1503(d)-1 Definitions, special rules, and filings.
- § 1.1503(d)-7 Examples.
- § 1.6038B-1T Reporting of certain transactions to foreign corporations (temporary).
- § 4.954-1 Foreign base company income; taxable years beginning after December 31, 1986.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9803 (81 FR 91028)
- Amended by T.D. 9760 (81 FR 15169)
- Amended by T.D. 9615 (78 FR 17063)
- Issued by T.D. 8087 (51 FR 17950)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Effects on corporation
Nearby sections
- § 1.367(a)-2 Exceptions for transfers of property for use in the active conduct of a trade or business.
- § 1.367(a)-3 Treatment of transfers of stock or securities to foreign corporations.
- § 1.367(a)-4 Special rule applicable to U.S. depreciated property.
- § 1.367(a)-6 Transfer of foreign branch with previously deducted losses.
- § 1.367(a)-6T Transfer of foreign branch with previously deducted losses (temporary).
- § 1.367(a)-7 Outbound transfers of property described in section 361(a) or (b).
- § 1.367(a)-8 Gain recognition agreement requirements.
- § 1.367(a)-9T Treatment of deemed section 351 exchanges pursuant to section 304(a)(1) (temporary).
- § 1.367(b)-0 Table of contents.