
Treasury Regulations · 26 CFR
§ 1.412(c)(3)-1. Reasonable funding methods.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 412(c)(3)
Cite as 26 CFR § 1.412(c)(3)-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- December 31, 1980 by T.D. 7746
- Issued under
- 26 U.S.C. § 412(c)(3)
- Length
- 2,919 words · about 13 min to read
- Cross-references
- cites 5 Code sections and 3 regulations; cited by 1
Thus, for example, benefits payable if a participant dies or becomes disabled prior to separation from service are ancillary benefits because the events giving rise to the benefits are detrimental to the participant's health. However, an early retirement benefit, a social security supplement (as defined in § 1.411(a)-7(c)(4)(ii)), and the vesting of plan benefits (even if more rapid than is required by section 411) are not ancillary benefits because those benefits do not result from an event which is detrimental to the participant's health.
Assume that a plan, using funding method A, is in its first year. No contributions have been made to the plan, other than a nominal contribution to establish a corpus for the plan's trust. There is no past service liability, and the normal cost is a constant percentage of an annually determined amount. The constant percentage is 99 percent, and the annually determined amount is the excess of the present value of future benefits over plan assets. The present value of future benefits is $10,000. Under paragraph (b)(1) of this section, the present value of future benefits must equal the present value of future normal costs plus plan assets. (No amortizable bases exist, nor are there credit or debit balances.) Under method A, the present value of future normal costs would equal the sum of a series of annually decreasing amounts. Because of the constant percentage factor, the present value of future normal costs over the years can never equal $10,000, the present value of future benefits. In effect, then, assets under method A can never equal the present value of future benefits if all assumptions are exactly realized. Therefore, method A is not a reasonable funding method.
Assume that a plan, using funding method B, determines normal cost by computing the present value of benefits expected to be accrued under the plan by the end of 10 years after the valuation date and adding to this the present value of benefits expected to be paid within these 10 years. Plan assets are subtracted from the sum of the two present value amounts. The difference then is divided by the present value of salaries projected over the 10 years. Under paragraph (c)(1) of this section, all liabilities of a plan must be taken into account. Because method B takes into account only benefits paid or accrued by the end of 10 years, it is not a reasonable funding method.
Assume that a plan, using funding method C, determines normal cost as a constant percentage of compensation. (This percentage is determined as follows: The excess of projected benefits over accrued benefits is computed. Then the present value of this excess is divided by the present value of future salaries.) However, the accrued liability is computed each year as the present value of accrued benefits. (This computation does not reflect normal cost as a constant percentage of compensation. Thus, normal cost under the plan does not link accrued liabilities under the plan for consecutive years as would be the case, for example, under a unit credit cost method.) In determining gains and losses, method C compares the actual unfunded liability (the accrued liability less assets) with the expected unfunded liability (the sum of the actual unfunded liability in the previous year and the normal cost for the previous year less the contribution made for the previous year, all adjusted for interest). Under paragraph (c)(2) of this section, if actuarial assumptions are exactly realized, experience gains and losses must not be produced. Under method C, the use of a constant percentage in computing normal cost (and the expected unfunded liability) coupled with the manner of computing the accrued liability (and the actual unfunded liability) generally produces gains in the earlier years and losses in the later years if each actuarial assumption is exactly realized. Therefore, method C is not a reasonable funding method.
Assume that a plan, using funding method D, bases benefits on final average pay. Under method D, the past service liability on any date equals the present value of the accrued benefit on that date based on compensation as of that date. The normal cost for any year equals the present value of a certain amount. That amount is the excess of the projected accrued benefit as of the end of the year over the actual accrued benefit at the beginning of the year. Accrued benefits, projected as of the end of a year, reflect a 1-year salary projection. Under paragraph (c)(4) of this section, salary scales reflected in projected benefits must project salaries to the salary on which benefits would be based under the plan at the age when the receipt of benefits under the plan is expected to begin. Because the plan is not a career average pay plan and compensation is projected only 1 year, method D is not a reasonable funding method. (Under paragraph (c)(4) of this section, the use of a salary scale assumption could be required with a unit credit method if, without the use of a salary scale, assumptions in the aggregate are unreasonable.)
Assume that a plan, using method E, a unit credit funding method, calculates a participant's accrued benefit according to the following formula: 2 percent of final salary for the first 10 years of service and 1 percent of final salary for the years of service in excess of 10. Under the plan, no employee may be credited with more than 25 years of service. The actuarial assumptions for the valuation include a salary scale of 5 percent per year. For a participant at age 40 with 15 years of service, a current salary of $20,000 and a normal retirement age of 65, the accrued liability for the retirement benefit is the present value of an annuity of $16,932 per year, commencing at age 65. The $16,932 is calculated as follows:
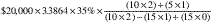
(3.3864 is 1.05 raised to the 25th power; the 25th power reflects the difference between normal retirement age and attained age (65-40).)
Salary under this method is projected to the age when the receipt of benefits is expected to begin. Therefore, method E meets the requirement of paragraph (c)(4) of this section. Also, the allocation of benefits under method E between past and future years of service meets the requirements of paragraph (e)(3) of this section.
Assume that a plan that has two participants and that previously used the unit credit cost method wishes to change the funding method at the beginning of the plan year to funding method F, a modification of the aggregate cost method. The modification involves determining normal cost for each of the two participants under the plan. Therefore, it requires an allocation of assets to each participant for valuation purposes. The actuary proposes to allocate the assets on hand at the beginning of the plan year of the change in funding method in proportion to the accrued liabilities calculated under the unit credit cost method. The relevant results of the calculations are shown below:
| Employees | Totals | ||
|---|---|---|---|
| M | N | ||
| Accrued Liabilities (unit credit method): | |||
| Dollar amount | 15,670 | 906 | 16,576 |
| Per cent of total | 94.53 | 5.47 | 100.00 |
| Assets: | |||
| Dollar amount | 7,835 | 453 | 8,288 |
| per cent of total | 94.53 | 5.47 | 100.00 |
The proposed allocation in proportion to the accrued liabilities under the unit credit cost method satisfies the requirements of paragraph (c)(5) of this section at the beginning of the first plan year for which the new method is used.
The facts are the same as in Example 6. However, the actuary proposes to allocate all the assets to employee M, the older employee. Method F, under these facts, is not an acceptable funding method because the allocation is not in proportion to related liabilities as required under paragraph (c)(5) of this section.
[T.D. 7746, 45 FR 86430, Dec. 31, 1980]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 412 Minimum funding standards
- § 411 Minimum vesting standards
- § 410 Minimum participation standards
- § 413 Collectively bargained plans, etc.
- § 401 Qualified pension, profit-sharing, and stock bonus plans
Regulations it cites
- § 1.412(c)(1)-1 Determinations to be made under funding method—terms defined.
- § 1.412(c)(1)-2 Shortfall method.
- § 1.411(a)-7 Definitions and special rules.
Cited by 1 other regulation
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 7746 (45 FR 86430)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Pension, Profit-Sharing, Stock Bonus Plans, etc.
Nearby sections
- § 1.412(c)(1)-1 Determinations to be made under funding method—terms defined.
- § 1.412(c)(1)-2 Shortfall method.
- § 1.412(c)(1)-3 Applying the minimum funding requirements to restored plans.
- § 1.412(c)(2)-1 Valuation of plan assets; reasonable actuarial valuation methods.
- § 1.412(c)(3)-1 Reasonable funding methods.
- § 1.412(c)(3)-2 Effective dates and transitional rules relating to reasonable funding methods.
- § 1.412(i)-1 Certain insurance contract plans.
- § 1.413-1 Special rules for collectively bargained plans.
- § 1.413-2 Special rules for plans maintained by more than one employer.