
Treasury Regulations · 26 CFR
§ 1.467-5. Section 467 rental agreements with variable interest.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 467
Cite as 26 CFR § 1.467-5
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- May 18, 1999 by T.D. 8820
- Issued under
- 26 U.S.C. § 467
- Length
- 1,617 words · about 7 min to read
- Cross-references
- cites 1 Code section and 5 regulations; cited by 3
(i) X and Y enter into a section 467 rental agreement for the lease of personal property beginning on January 1, 2000, and ending on December 31, 2002. The rental agreement allocates $100,000 of rent to 2000, $200,000 to 2001, and $100,000 to 2002, and requires the lessee to pay all $400,000 of rent on December 31, 2002. The rental agreement requires the accrual of interest on unpaid accrued rent at two different qualified floating rates (as defined in § 1.1275-5(b)), one for 2001 and the other for 2002, such interest to be paid on December 31 of the year it accrues. The rental agreement provides that the qualified floating rate is set at a current value within the meaning of § 1.1275-5(a)(4). Assume that on the agreement date, 110 percent of the applicable Federal rate is 10 percent, compounded annually. Assume also that the agreement is not a leaseback or long-term agreement and, therefore, is not subject to constant rental accrual.
(ii) To determine if the section 467 rental agreement provides for adequate interest under § 1.467-2(b), § 1.467-2(b)(2) requires the use of fixed rate substitutes (in this example determined in the same manner as under § 1.1275-5(e)(3)(i) treating the agreement date as the issue date) in place of the variable rates called for by the rental agreement. Assume that on the agreement date the qualified floating rates, and therefore the fixed rate substitutes, relating to 2001 and 2002 are 10 and 15 percent compounded annually. Taking into account the fixed rate substitutes, the sum of the present values of all amounts payable by the lessee as fixed rent and interest thereon is greater than the sum of the present values of the fixed rent allocated to each rental period. Accordingly, the rental agreement provides adequate interest under § 1.467-2(b)(1)(iii) and the fixed rent accruing in each calendar year during the rental agreement is the fixed rent allocated under the rental agreement.
(iii) Because the section 467 rental agreement provides for variable interest on unpaid accrued fixed rent at qualified floating rates and the qualified floating rates are set at a current value, the requirements of § 1.1275-5(a)(3)(i)(A) and (4) are met and the rental agreement provides for variable interest within the meaning of paragraph (a)(1) of this section. Therefore, under paragraph (b)(1)(i) of this section, the yield of the section 467 loan is computed based on the fixed rate substitutes. Under § 1.467-4(c), the constant yield (rounded to two decimal places) equals 13.63 percent compounded annually. Based on the fixed rate substitutes, the fixed rent, interest on fixed rent, and the principal balance of the section 467 loan, for each calendar year during the lease term, are as follows:
| Accrued rent | Accrued interest | Projected payment | Cumulative loan | |
|---|---|---|---|---|
| 2000 | $100,000 | $0 | $0 | $100,000 |
| 2001 | 200,000 | 13,630 | (10,000) | 303,630 |
| 2002 | 100,000 | 41,370 | (445,000) | 0 |
(iv) To compute the actual reported interest on fixed rent for each calendar year, the variable interest adjustment amount, as described in paragraph (b)(2) of this section, must be added to the accrued interest determined in paragraph (iii) of this Example 1. Assume that the variable rates for 2001 and 2002 are actually 11 and 14 percent, respectively. Without regard to section 467, the interest that would have accrued during each calendar year under the terms of the section 467 rental agreement, and the interest that would have accrued under the terms of the rental agreement using the fixed rate substitutes determined under paragraph (b)(1)(i) of this section are as follows:
| Accrued interest under rental agreement | Accrued interest using fixed rate substitutes | |
|---|---|---|
| 2000 | $0 | $0 |
| 2001 | 11,000 | 10,000 |
| 2002 | 42,000 | 45,000 |
(v) Under paragraph (b)(2) of this section, the variable interest adjustment amount is $1,000 ($11,000−$10,000) for 2001 and is −$3,000 ($42,000−$45,000) for 2002. Thus, under paragraph (b)(1)(ii) of this section, the actual interest on fixed rent for 2001 is $14,630 ($13,630 + $1,000) and for 2002 is $38,370 ($41,370−$3,000).
(i) The facts are the same as in Example 1 except that 110 percent of the applicable Federal rate is 15 percent compounded annually and the section 467 rental agreement does not provide adequate interest under § 1.467-2(b). Consequently, the fixed rent for each calendar year during the lease is the proportional rental amount.
(ii) The sum of the present values of the fixed rent provided for each calendar year during the lease term, discounted at 15 percent compounded annually, equals $303,936.87.
(iii)(A) Paragraph (b)(1)(i) of this section requires the proportional rental amount to be computed based on the assumption that interest will accrue and be paid based on the fixed rate substitutes. Thus, the sum of the present values of the projected payments under the section 467 rental agreement equals $300,156.16, computed as follows:
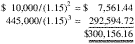
(B) The fraction for computing the proportional rental amount equals .9875609 ($300,156.16/$303,936.87).
(iv) Based on the fixed rate substitutes, the fixed rent, interest on fixed rent, and the balance of the section 467 loan for each calendar year during the lease term are as follows:
| Proportional rent | Accrued interest | Projected payment | Cumulative loan | |
|---|---|---|---|---|
| 2000 | $98,756.09 | $0.00 | $0 | $98,756.09 |
| 2001 | 197,512.18 | 14,813.41 | (10,000) | 301,081.68 |
| 2002 | 98,756.09 | 45,162.23 | (445,000) | 0.00 |
(v) The variable interest adjustment amount in this example is the same as in Example 1. Under paragraph (b)(1)(ii) of this section, the actual interest on fixed rent for 2001 is $15,813.41 ($14,813.41 + $1,000) and for 2002 is $42,162.23 ($45,162.23−$3,000).
[T.D. 8820, 64 FR 26865, May 18, 1999]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
Regulations it cites
- § 1.1275-5 Variable rate debt instruments.
- § 1.467-2 Rent accrual for section 467 rental agreements without adequate interest.
- § 1.467-3 Disqualified leasebacks and long-term agreements.
- § 1.467-4 Section 467 loan.
- § 1.467-1 Treatment of lessors and lessees generally.
Cited by 3 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 8820 (64 FR 26865)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Taxable year for which deductions taken
Nearby sections
- § 1.467-1 Treatment of lessors and lessees generally.
- § 1.467-2 Rent accrual for section 467 rental agreements without adequate interest.
- § 1.467-3 Disqualified leasebacks and long-term agreements.
- § 1.467-4 Section 467 loan.
- § 1.467-5 Section 467 rental agreements with variable interest.
- § 1.467-7 Section 467 recapture and other rules relating to dispositions and modifications.
- § 1.467-8 Automatic consent to change to constant rental accrual for certain rental agreements.
- § 1.467-9 Effective/applicability dates and automatic method changes for certain agreements.
- § 1.468A-0 Nuclear decommissioning costs; table of contents.