
Treasury Regulations · 26 CFR
§ 1.501(c)(12)-1. Local benevolent life insurance associations, mutual irrigation and telephone companies, and like organizations.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 501(c)(12)
Cite as 26 CFR § 1.501(c)(12)-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- November 26, 1960 by T.D. 6500
- Last amended
- October 16, 1979
- Issued under
- 26 U.S.C. § 501(c)(12)
- Length
- 448 words · about 2 min to read
- Cross-references
- cites 1 Code section and 0 regulations; cited by 1
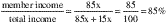
of the cooperative's total income is derived from member income.
[T.D. 6500, 25 FR 11737, Nov. 26, 1960; 25 FR 14021, Dec. 31, 1960, as amended at 44 FR 59523, Oct. 16, 1979]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
Cited by 1 other regulation
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended (44 FR 59523)
- Amended (25 FR 14021)
- Issued by T.D. 6500 (25 FR 11737)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Exempt Organizations
Nearby sections
- § 1.501(c)(9)-6 Voluntary employees' beneficiary associations; benefits includible in gross income.
- § 1.501(c)(9)-7 Voluntary employees' beneficiary associations; section 3(4) of ERISA.
- § 1.501(c)(9)-8 Voluntary employees' beneficiary associations; effective date.
- § 1.501(c)(10)-1 Certain fraternal beneficiary societies.
- § 1.501(c)(12)-1 Local benevolent life insurance associations, mutual irrigation and telephone companies, and like organizations.
- § 1.501(c)(13)-1 Cemetery companies and crematoria.
- § 1.501(c)(14)-1 Credit unions and mutual insurance funds.
- § 1.501(c)(15)-1 Mutual insurance companies or associations.
- § 1.501(c)(16)-1 Corporations organized to finance crop operations.