
Treasury Regulations · 26 CFR
§ 1.514(a)-1. Unrelated debt-financed income and deductions.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 514(a)
Cite as 26 CFR § 1.514(a)-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- December 21, 1972 by T.D. 7229
- Issued under
- 26 U.S.C. § 514(a)
- Length
- 2,598 words · about 11 min to read
- Cross-references
- cites 6 Code sections and 3 regulations; cited by 3
(a) The average acquisition indebtedness (as defined in subparagraph (3) of this paragraph) with respect to the property is of
(b) The average adjusted basis of such property (as defined in subparagraph (2) of this paragraph).
X, an exempt trade association, owns an office building which in 1971 produces $10,000 of gross rental income. The average adjusted basis of the building for 1971 is $100,000, and the average acquisition indebtedness with respect to the building for 1971 is $50,000. Accordingly, the debt/basis percentage for 1971 is 50 percent (the ratio of $50,000 to $100,000). Therefore, the unrelated debt-financed income with respect to the building for 1971 is $5,000 (50 percent of $10,000).
(a) The highest acquisition indebtedness with respect to such property during the 12-month period, preceding the date of disposition, is of
(b) The average adjusted basis of such property.
The tax on the amount of gain (or loss) included in unrelated business taxable income pursuant to the preceding sentence shall be determined in accordance with the rules set forth in subchapter P, chapter 1 of the Code (relating to capital gains and losses). See also section 511(d) and the regulations thereunder (relating to the minimum tax for tax preferences).
(a) The adjusted basis of such property as of the first day during the taxable year that the organization holds the property, and
(b) The adjusted basis of such property as of the last day during the taxable year that the organization holds the property
See section 1011 and the regulations thereunder for determination of the adjusted basis of property.
On July 10, 1970, X, an exempt educational organization, purchased an office building for $510,000, using $300,000 of borrowed funds. During 1970 the only adjustment to basis is $20,000 for depreciation. As of December 31, 1970, the adjusted basis of the building is $490,000 and the indebtedness is still $300,000. X files its return on a calendar year basis. Under these circumstances, the debt/basis percentage for 1970 is 60 percent, calculated in the following manner:
| Basis | |
|---|---|
| As of July 10, 1970 (acquisition date) | $510,000 |
| As of December 31, 1970 | 490,000 |
| Total | 1,000,000 |
Average Adjusted basis:
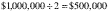
Debt/basis percentage:
Average acquisition indebtedness ($300,000) / Average adjusted basis ($500,000) = 60 percent
For an illustration of the determination of the debt/basis percentage as changes in the acquisition indebtedness occur, see example 1 of subparagraph (3)(iii) of this paragraph.
Assume the facts as stated in the example in subparagraph (2)(iv) of this paragraph, except that beginning July 20, 1970, the organization makes payments of $21,000 a month ($20,000 of which is attributable to principal and $1,000 to interest). In this situation, the average acquisition indebtedness for 1970 is $250,000. Thus, the debt/basis percentage for 1970 is 50 percent, calculated in the following manner:
| Indebtedness on the first day in each calendar month that the property is held | |
|---|---|
| Month: | |
| July | $300,000 |
| August | 280,000 |
| September | 260,000 |
| October | 240,000 |
| November | 220,000 |
| December | 200,000 |
| Total | 1,500,000 |
Average acquisition indebtedness:
$1,500,000 ÷ 6 months = $250,000
Debt/basis percentage:
Average acquisition indebtedness ($250,000) / Average adjusted basis ($500,000) = 50 percent
Y, an exempt organization, owns stock in a corporation which it does not control. At the beginning of the year, Y has an outstanding principal indebtedness with respect to such stock of $12,000. Such indebtedness is paid off at the rate of $2,000 per month beginning January 30, so that it is retired at the end of 6 months. The average acquisition indebtedness for the taxable year is $3,500, calculated in the following manner:
| Indebtedness on the first day in each calendar month that the property is held | |
|---|---|
| Month: | |
| January | $12,000 |
| February | 10,000 |
| March | 8,000 |
| April | 6,000 |
| May | 4,000 |
| June | 2,000 |
| July thru December | 0 |
| Total | 42,000 |
Average acquisition indebtedness:
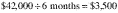
On January 1, 1971, X, an exempt trade association, acquires an office building for a down payment of $310,000 and an agreement to pay 10 percent of the income generated by the building for 10 years. Neither the sales price nor the amount which X is obligated to pay in the future is certain. The fair market value of the building on the date of acquisition is $600,000. The depreciation allowance for 1971 is $40,000. Unless X obtains the consent of the Commissioner to use another method, the unadjusted basis of the property is $600,000 (the fair market value of the property on the date of acquisition), and the initial acquisition indebtedness is $290,000 (fair market value of $600,000 less initial payment of $310,000). Under these circumstances, the average adjusted basis of the property for 1971 is $580,000, calculated as follows:
[Initial fair market value + (initial fair market value less depreciation)] ÷ 2 = [$600,000 + ($600,000 − $40,000)] ÷ 2 = $580,000.
If no payment other than the initial payment is made in 1971, the average acquisition indebtedness for 1971 is $290,000. Thus, the debt/basis percentage for 1971 is 50 percent, calculated as follows:
Average acquisition indebtedness ÷ average adjusted basis = $290,000 ÷ $580,000 = 50 percent
X, an exempt educational organization, owns securities which are capital assets and which it has held for more than 6 months. In 1972 X sells the securities at a loss of $20,000. The debt/basis percentage with respect to computing the gain (or loss) derived from the sale of the securities is 40 percent. Thus, X has sustained a capital loss of $8,000 (40 percent of $20,000) with respect to the sale of the securities. For 1972 and the preceding three taxable years X has no other capital transactions. Under these circumstances, the $8,000 of capital loss may be carried over to the succeeding 5 taxable years without further application of the debt/basis percentage.
During 1974, Y, an exempt organization, receives $20,000 of rent from a building which it owns. Y has no other unrelated business taxable income for 1974. For 1974 the deductions directly connected with this building are property taxes of $5,000, interest of $5,000 on the acquisition indebtedness, and salary of $15,000 to the manager of the building. The debt/basis percentage for 1974 with respect to the building is 50 percent. Under these circumstances, Y shall take into account in computing its unrelated business taxable income for 1974, $10,000 of income (50 percent of $20,000) and $12,500 (50 percent of $25,000) of the deductions directly connected with such income. Thus, for 1974 Y has sustained a net operating loss of $2,500 ($10,000 of income less $12,500 of deductions) which may be carried back or carried over to other taxable years without further application of the debt/basis percentage.
[T.D. 7229, 37 FR 28143, Dec. 21, 1972]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 514 Unrelated debt-financed income
- § 511 Imposition of tax on unrelated business income of charitable, etc., organizations
- § 1011 Adjusted basis for determining gain or loss
- § 243 Dividends received by corporations
- § 512 Unrelated business taxable income
- § 167 Depreciation
Regulations it cites
- § 1.514(b)-1 Definition of debt-financed property.
- § 1.514(c)-1 Acquisition indebtedness.
- § 1.514(d)-1 Basis of debt-financed property acquired in corporate liquidation.
Cited by 3 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 7229 (37 FR 28143)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Taxation of Business Income of Certain Exempt Organizations
Nearby sections
- § 1.513-4 Certain sponsorship not unrelated trade or business.
- § 1.513-5 Certain bingo games not unrelated trade or business.
- § 1.513-6 Certain hospital services not unrelated trade or business.
- § 1.513-7 Travel and tour activities of tax exempt organizations.
- § 1.514(a)-1 Unrelated debt-financed income and deductions.
- § 1.514(a)-2 Business lease rents and deductions for taxable years beginning before January 1, 1970.
- § 1.514(b)-1 Definition of debt-financed property.
- § 1.514(c)-1 Acquisition indebtedness.
- § 1.514(c)-2 Permitted allocations under section 514(c)(9)(E).