
Treasury Regulations · 26 CFR
§ 1.6015-3. Allocation of deficiency for individuals who are no longer married, are legally separated, or are not members of the same household.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 6015
Cite as 26 CFR § 1.6015-3
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- July 18, 2002 by T.D. 9003
- Issued under
- 26 U.S.C. § 6015
- Length
- 6,857 words · about 30 min to read
- Cross-references
- cites 6 Code sections and 2 regulations; cited by 5
(i) H and W file their 2001 joint Federal income tax return on April 15, 2002. On the return, H and W report W's self-employment income, but they do not report W's self-employment tax on that income. H and W divorce in July 2003. In August 2003, H and W receive a 30-day letter from the Internal Revenue Service proposing a deficiency with respect to W's unreported self-employment tax on the 2001 return. On November 4, 2003, H files an election to allocate the deficiency to W. The erroneous item is the self-employment income, and it is allocable to W. H knows that W earned income in 2001 as a self-employed musician, but he does not know that self-employment tax must be reported on and paid with a joint return.
(ii) H's election to allocate the deficiency to W is invalid because, at the time H signed the joint return, H had actual knowledge of W's self-employment income. The fact that H was unaware of the tax consequences of that income (i.e., that an individual is required to pay self-employment tax on that income) is not relevant.
(i) H has long been an avid gambler. H supports his gambling habit and keeps all of his gambling winnings in an individual bank account, held solely in his name. W knows about H's gambling habit and that he keeps a separate bank account, but she does not know whether he has any winnings because H does not tell her, and she does not otherwise know of H's bank account transactions. H and W file their 2001 joint Federal income tax return on April 15, 2002. On October 31, 2003, H and W receive a 30-day letter proposing a $100,000 deficiency relating to H's unreported gambling income. In February 2003, H and W divorce, and in March 2004, W files an election under section 6015(c) to allocate the $100,000 deficiency to H.
(ii) While W may have had reason to know of the gambling income because she knew of H's gambling habit and separate account, W did not have actual knowledge of the erroneous item (i.e., the gambling winnings). The Internal Revenue Service may not infer actual knowledge from W's reason to know of the income. Therefore, W's election to allocate the $100,000 deficiency to H is valid.
(i) H and W are legally separated. In February 1999, W signs a blank joint Federal income tax return for 1998 and gives it to H to fill out. The return was timely filed on April 15, 1999. In September 2001, H and W receive a 30-day letter proposing a deficiency relating to $100,000 of unreported dividend income received by H with respect to stock of ABC Co. owned by H. W knew that H received the $100,000 dividend payment in August 1998, but she did not know whether H reported that payment on the joint return.
(ii) On January 30, 2002, W files an election to allocate the deficiency from the 1998 return to H. W claims she did not review the completed joint return, and therefore, she had no actual knowledge that there was an understatement of the dividend income. W's election to allocate the deficiency to H is invalid because she had actual knowledge of the erroneous item (dividend income from ABC Co.) at the time she signed the return. The fact that W signed a blank return is irrelevant. The result would be the same if W had not reviewed the completed return or if W had reviewed the completed return and had not noticed that the item was omitted.
(i) H and W are legally separated. In June 2004, a deficiency is proposed with respect to H's and W's 2002 joint Federal income tax return that is attributable to $30,000 of unreported income from H's plumbing business that should have been reported on a Schedule C. No Schedule C was attached to the return. At the time W signed the return, W knew that H had a plumbing business but did not know whether H received any income from the business. W's election to allocate to H the deficiency attributable to the $30,000 of unreported plumbing income is valid.
(ii) Assume the same facts as in paragraph (i) of this Example 5 except that, at the time W signed the return, W knew that H received $20,000 of plumbing income. W's election to allocate to H the deficiency attributable to the $20,000 of unreported plumbing income (of which W had actual knowledge) is invalid. W's election to allocate to H the deficiency attributable to the $10,000 of unreported plumbing income (of which W did not have actual knowledge) is valid.
(iii) Assume the same facts as in paragraph (i) of this Example 5 except that, at the time W signed the return, W did not know the exact amount of H's plumbing income. W did know, however, that H received at least $8,000 of plumbing income. W's election to allocate to H the deficiency attributable to $8,000 of unreported plumbing income (of which W had actual knowledge) is invalid. W's election to allocate to H the deficiency attributable to the remaining $22,000 of unreported plumbing income (of which W did not have actual knowledge) is valid.
(iv) Assume the same facts as in paragraph (i) of this Example 5 except that H reported $26,000 of plumbing income on the return and omitted $4,000 of plumbing income from the return. At the time W signed the return, W knew that H was a plumber, but she did not know that H earned more than $26,000 that year. W's election to allocate to H the deficiency attributable to the $4,000 of unreported plumbing income is valid because she did not have actual knowledge that H received plumbing income in excess of $26,000.
(v) Assume the same facts as in paragraph (i) of this Example 5 except that H reported only $20,000 of plumbing income on the return and omitted $10,000 of plumbing income from the return. At the time W signed the return, W knew that H earned at least $26,000 that year as a plumber. However, W did not know that, in reality, H earned $30,000 that year as a plumber. W's election to allocate to H the deficiency attributable to the $6,000 of unreported plumbing income (of which W had actual knowledge) is invalid. W's election to allocate to H the deficiency attributable to the $4,000 of unreported plumbing income (of which W did not have actual knowledge) is valid.
(i) H and W are legally separated. In February 2005, a deficiency is asserted with respect to their 2002 joint Federal income tax return. The deficiency is attributable to a disallowed $1,000 deduction for medical expenses H claimed he incurred. At the time W signed the return, W knew that H had not incurred any medical expenses. W's election to allocate to H the deficiency attributable to the disallowed medical expense deduction is invalid because W had actual knowledge that H had not incurred any medical expenses.
(ii) Assume the same facts as in paragraph (i) of this Example 6 except that, at the time W signed the return, W did not know whether H had incurred any medical expenses. W's election to allocate to H the deficiency attributable to the disallowed medical expense deduction is valid because she did not have actual knowledge that H had not incurred any medical expenses.
(iii) Assume the same facts as in paragraph (i) of this Example 6 except that the Internal Revenue Service disallowed $400 of the $1,000 medical expense deduction. At the time W signed the return, W knew that H had incurred some medical expenses but did not know the exact amount. W's election to allocate to H the deficiency attributable to the disallowed medical expense deduction is valid because she did not have actual knowledge that H had not incurred medical expenses (in excess of the floor amount under section 213(a)) of more than $600.
(iv) Assume the same facts as in paragraph (i) of this Example 6 except that H claims a medical expense deduction of $10,000 and the Internal Revenue Service disallows $9,600. At the time W signed the return, W knew H had incurred some medical expenses but did not know the exact amount. W also knew that H incurred medical expenses (in excess of the floor amount under section 213(a)) of no more than $1,000. W's election to allocate to H the deficiency attributable to the portion of the overstated deduction of which she had actual knowledge ($9,000) is invalid. W's election to allocate the deficiency attributable to the portion of the overstated deduction of which she had no knowledge ($600) is valid.
(i) H and W are divorced. In May 1999, W transfers $20,000 to H, and in April 2000, H and W receive a 30-day letter proposing a $40,000 deficiency on their 1998 joint Federal income tax return. The liability remains unpaid, and in October 2000, H elects to allocate the deficiency under this section. Seventy-five percent of the net amount of erroneous items are allocable to W, and 25% of the net amount of erroneous items are allocable to H.
(ii) In accordance with the proportionate allocation method (see paragraph (d)(4) of this section), H proposes that $30,000 of the deficiency be allocated to W and $10,000 be allocated to himself. H submits a signed statement providing that the principal purpose of the $20,000 transfer was not the avoidance of tax or payment of tax, but he does not submit any documentation indicating the reason for the transfer. H has not overcome the presumption that the $20,000 was a disqualified asset. Therefore, the portion of the deficiency for which H is liable ($10,000) is increased by the value of the disqualified asset ($20,000). H is relieved of liability for $10,000 of the $30,000 deficiency allocated to W, and remains jointly and severally liable for the remaining $30,000 of the deficiency (assuming that H does not qualify for relief under any other provision).
On May 1, 2001, H and W receive a 30-day letter regarding a proposed deficiency on their 1999 joint Federal income tax return relating to unreported capital gain from H's sale of his investment in Z stock. W had no actual knowledge of the stock sale. The deficiency is assessed in November 2001, and in December 2001, H and W divorce. According to a decree of divorce, H must transfer 1/2 of his interest in mutual fund A to W. The transfer takes place in February 2002. In August 2002, W elects to allocate the deficiency to H. Although the transfer of 1/2 of H's interest in mutual fund A took place after the 30-day letter was mailed, the mutual fund interest is not presumed to be a disqualified asset because the transfer of H's interest in the fund was made pursuant to a decree of divorce.
(i) H and W are married for 25 years. Every September, on W's birthday, H gives W a gift of $500. On February 28, 2002, H and W receive a 30-day letter from the Internal Revenue Service relating to their 1998 joint individual Federal income tax return. The deficiency relates to H's Schedule C business, and W had no knowledge of the items giving rise to the deficiency. H and W are legally separated in June 2003, and, despite the separation, H continues to give W $500 each year for her birthday. H is not required to give such amounts pursuant to a decree of divorce or separate maintenance.
(ii) On January 27, 2004, W files an election to allocate the deficiency to H. The $1,500 transferred from H to W from February 28, 2001 (a year before the 30-day letter was mailed) to the present is presumed disqualified. However, W may overcome the presumption that such amounts were disqualified by establishing that such amounts were birthday gifts from H and that she has received such gifts during their entire marriage. Such facts would show that the amounts were not transferred for the purpose of avoidance of tax or payment of tax.
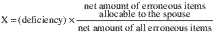
where X = the portion of the deficiency allocable to the spouse.
(i) H and W file a 2003 joint Federal income tax return on April 15, 2004. On April 28, 2006, a deficiency is assessed with respect to their 2003 return. Three erroneous items give rise to the deficiency—
(A) Unreported interest income, of which W had actual knowledge, from H's and W's joint bank account;
(B) A disallowed business expense deduction on H's Schedule C; and
(C) A disallowed Lifetime Learning Credit for W's post-secondary education, paid for by W.
(ii) H and W divorce in May 2006, and in September 2006, W timely elects to allocate the deficiency. The erroneous items are allocable as follows:
(A) The interest income would be allocated 1/2 to H and 1/2 to W, except that W has actual knowledge of it. Therefore, W's election to allocate the portion of the deficiency attributable to this item is invalid, and W remains jointly and severally liable for it.
(B) The business expense deduction is allocable to H.
(C) The Lifetime Learning Credit is allocable to W.
(i) W and H timely file their 2001 joint Federal income tax return on April 15, 2002. On August 16, 2004, a $54,000 deficiency is assessed with respect to their 2001 joint return. H and W divorce on October 14, 2004, and W timely elects to allocate the deficiency. Five erroneous items give rise to the deficiency—
(A) A disallowed $15,000 business deduction allocable to H;
(B) $20,000 of unreported income allocable to H;
(C) A disallowed $5,000 deduction for educational expense allocable to H;
(D) A disallowed $40,000 charitable contribution deduction allocable to W; and
(E) A disallowed $40,000 interest deduction allocable to W.
(ii) In total, there are $120,000 worth of erroneous items, of which $80,000 are attributable to W and $40,000 are attributable to H.
| W's items | H's items | |||
| $40,000 | charitable deduction | $15,000 | business deduction | |
| 40,000 | interest deduction | 20,000 | unreported income | |
| 5,000 | education deduction | |||
| $80,000 | $40,000 |
(iii) The ratio of erroneous items allocable to W to the total erroneous items is 2/3 ($80,000/$120,000). W's liability is limited to $36,000 of the deficiency ( 2/3 of $54,000). The Internal Revenue Service may collect up to $36,000 from W and up to $54,000 from H (the total amount collected, however, may not exceed $54,000). If H also made an election, there would be no remaining joint and several liability, and the Internal Revenue Service would be permitted to collect $36,000 from W and $18,000 from H.
(i) On September 4, 2001, W elects to allocate a $3,000 deficiency for the 1998 tax year to H. Three erroneous items give rise to the deficiency—
(A) Unreported interest in the amount of $4,000 from a joint bank account;
(B) A disallowed deduction for business expenses in the amount of $2,000 attributable to H's business; and
(C) Unreported wage income in the amount of $6,000 attributable to W's second job.
(ii) The erroneous items total $12,000. Generally, income, deductions, or credits from jointly held property that are erroneous items are allocable 50% to each spouse. However, in this case, both spouses had actual knowledge of the unreported interest income. Therefore, W's election to allocate the portion of the deficiency attributable to this item is invalid, and W and H remain jointly and severally liable for this portion. Assume that this portion is $1,000. W may allocate the remaining $2,000 of the deficiency.
| H's items | W's items | |||
| $2,000 | business deduction | $6,000 | wage income |
Total allocable items: $8,000
(iii) The ratio of erroneous items allocable to W to the total erroneous items is 3/4 ($6,000/$8,000). W's liability is limited to $1,500 of the deficiency ( 3/4 of $2,000) allocated to her. The Internal Revenue Service may collect up to $2,500 from W ( 3/4 of the total allocated deficiency plus $1,000 of the deficiency attributable to the joint bank account interest) and up to $3,000 from H (the total amount collected, however, cannot exceed $3,000).
(iv) Assume H also elects to allocate the 1998 deficiency. H is relieved of liability for 3/4 of the deficiency, which is allocated to W. H's relief totals $1,500 ( 3/4 of $2,000). H remains liable for $1,500 of the deficiency ( 1/4 of the allocated deficiency plus $1,000 of the deficiency attributable to the joint bank account interest).
(i) On September 1, 2006, a $28,000 deficiency is assessed with respect to H's and W's 2003 joint return. The deficiency is the result of 4 erroneous items—
(A) A disallowed Lifetime Learning Credit of $2,000 attributable to H;
(B) A disallowed business expense deduction of $8,000 attributable to H;
(C) Unreported income of $24,000 attributable to W; and
(D) Unreported self-employment tax of $14,000 attributable to W.
(ii) H and W both elect to allocate the deficiency.
(iii) The $2,000 Lifetime Learning Credit and the $14,000 self-employment tax are STIs totaling $16,000. The amount of erroneous items included in computing the proportionate allocation ratio is $32,000 ($24,000 unreported income and $8,000 disallowed business expense deduction). The amount of the deficiency subject to proportionate allocation is reduced by the amount of STIs ($28,000−$16,000 = $12,000).
(iv) Of the $32,000 of proportionate allocation items, $24,000 is allocable to W, and $8,000 is allocable to H.
| W's share of allocable items | H's share of allocable items | |
| 3⁄4 ($24,000/$32,000) | 1⁄4 ($8,000/$32,000) |
(v) W's liability for the portion of the deficiency subject to proportionate allocation is limited to $9,000 ( 3/4 of $12,000) and H's liability for such portion is limited to $3,000 ( 1/4 of $12,000).
(vi) After the proportionate allocation is completed, the amount of the STIs is added to each spouse's allocated share of the deficiency.
| W's share of total deficiency | H's share of total deficiency | |||
| $ 9,000 | allocated deficiency | $3,000 | allocated deficiency | |
| 14,000 | self-employment tax | 2,000 | Lifetime Learning Credit | |
| $23,000 | $5,000 |
(vii) Therefore, W's liability is limited to $23,000 and H's liability is limited to $5,000.
(i) In 2001, H reports gross income of $4,000 from his business on Schedule C, and W reports $50,000 of wage income. On their 2001 joint Federal income tax return, H deducts $20,000 of business expenses resulting in a net loss from his business of $16,000. H and W divorce in September 2002, and on May 22, 2003, a $5,200 deficiency is assessed with respect to their 2001 joint return. W elects to allocate the deficiency. The deficiency on the joint return results from a disallowance of all of H's $20,000 of deductions.
(ii) Since H used only $4,000 of the disallowed deductions to offset gross income from his business, W benefitted from the other $16,000 of the disallowed deductions used to offset her wage income. Therefore, $4,000 of the disallowed deductions are allocable to H and $16,000 of the disallowed deductions are allocable to W. W's liability is limited to $4,160 ( 4/5 of $5,200). If H also elected to allocate the deficiency, H's election to allocate the $4,160 of the deficiency to W would be invalid because H had actual knowledge of the erroneous items.
Assume the same facts as in Example 5, except that H deducts $18,000 for business expenses on the joint return, of which $16,000 are disallowed. Since H used only $2,000 of the $16,000 disallowed deductions to offset gross income from his business, W received benefit on the return from the other $14,000 of the disallowed deductions used to offset her wage income. Therefore, $2,000 of the disallowed deductions are allocable to H and $14,000 of the disallowed deductions are allocable to W. W's liability is limited to $4,550 ( 7/8 of $5,200).
H and W timely file their 1998 joint Federal income tax return. H and W divorce in 1999. On July 13, 2001, a $5,100 deficiency is assessed with respect to H's and W's 1998 return. Of this deficiency, $2,000 results from unreported capital gain of $6,000 that is attributable to W and $4,000 of capital gain that is attributable to H (both gains being subject to tax at the 20% marginal rate). The remaining $3,100 of the deficiency is attributable to $10,000 of unreported dividend income of H that is subject to tax at a marginal rate of 31%. H and W both timely elect to allocate the deficiency, and qualify under this section to do so. There are erroneous items subject to different tax rates; thus, the alternative allocation method of this paragraph (d)(6) applies. The three erroneous items are first categorized according to their applicable tax rates, then allocated. Of the total amount of 20% tax rate items ($10,000), 60% is allocable to W and 40% is allocable to H. Therefore, 60% of the $2,000 deficiency attributable to these items (or $1,200) is allocated to W. The remaining 40% of this portion of the deficiency ($800) is allocated to H. The only 31% tax rate item is allocable to H. Accordingly, H is liable for $3,900 of the deficiency ($800 + $3,100), and W is liable for the remaining $1,200.
[T.D. 9003, 67 FR 47285, July 18, 2002]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 7703 Determination of marital status
- § 6015 Relief from joint and several liability on joint return
- § 213 Medical, dental, etc., expenses
- § 55 Alternative minimum tax imposed
- § 1 Tax imposed
- § 6662 Imposition of accuracy-related penalty on underpayments
Regulations it cites
Cited by 5 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 9003 (67 FR 47285)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Tax returns or statements
Nearby sections
- § 1.6014-2 Tax not computed by taxpayer for taxable years beginning after December 31, 1969.
- § 1.6015-0 Table of contents.
- § 1.6015-1 Relief from joint and several liability on a joint return.
- § 1.6015-2 Relief from liability applicable to all qualifying joint filers.
- § 1.6015-3 Allocation of deficiency for individuals who are no longer married, are legally separated, or are not members of the same household.
- § 1.6015-4 Equitable relief.
- § 1.6015-5 Time and manner for requesting relief.
- § 1.6015-6 Nonrequesting spouse's notice and opportunity to participate in administrative proceedings.
- § 1.6015-7 Tax Court review.