
Treasury Regulations · 26 CFR
§ 1.904(b)-1. Special rules for capital gains and losses.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 904(b)
Cite as 26 CFR § 1.904(b)-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- July 20, 2004 by T.D. 9141
- Last amended
- October 21, 2004
- Issued under
- 26 U.S.C. § 904(b)
- Length
- 10,509 words · about 46 min to read
- Defines
- 2 terms
- Cross-references
- cites 8 Code sections and 1 regulation; cited by 6
Taxpayer A, a corporation, has a $3,000 capital loss from sources outside the United States in the general limitation category, a $6,000 capital gain from sources outside the United States in the passive category, and a $2,000 capital loss from sources within the United States. A's capital gain net income from sources outside the United States in the aggregate, from all separate categories, is $3,000 ($6,000 − $3,000). A's capital gain net income from all sources is $1,000 ($6,000 − $3,000 − $2,000). Thus, for purposes of section 904, A's taxable income from sources outside the United States in all of A's separate categories in the aggregate includes only $1,000 of capital gain net income from sources outside the United States. See paragraph (a)(1)(i) of this section. Pursuant to paragraphs (a)(1)(i) and (a)(1)(ii)(A) of this section, A must reduce the $6,000 of capital gain net income from sources outside the United States in the passive category by $2,000 ($3,000 of capital gain net income from sources outside the United States − $1,000 of capital gain net income from all sources). After the adjustment, A has $4,000 of capital gain from sources outside the United States in the passive category and $3,000 of capital loss from sources outside the United States in the general limitation category.
Taxpayer B, a corporation, has a $300 capital gain from sources outside the United States in the general limitation category and a $200 capital gain from sources outside the United States in the passive category. B's capital gain net income from sources outside the United States is $500 ($300 + $200). B also has a $150 capital loss from sources within the United States and a $50 capital gain from sources within the United States. Thus, B's capital gain net income from all sources is $400 ($300 + $200 − $150 + $50). Pursuant to paragraph (a)(1)(ii)(A) of this section, the $100 excess of capital gain net income from sources outside the United States over capital gain net income from all sources ($500 − $400) must be apportioned, as a reduction, three-fifths ($300/$500 of $100, or $60) to the general limitation category and two-fifths ($200/$500 of $100, or $40) to the passive category. Therefore, for purposes of section 904, the general limitation category includes $240 ($300 − $60) of capital gain net income from sources outside the United States and the passive category includes $160 ($200 − $40) of capital gain net income from sources outside the United States.
Taxpayer C, a corporation, has a $10,000 capital loss from sources outside the United States in the general limitation category, a $4,000 capital gain from sources outside the United States in the passive category, and a $2,000 capital gain from sources within the United States. C's capital gain net income from sources outside the United States is zero, since losses exceed gains. C's capital gain net income from all sources is also zero. C's capital gain net income from sources outside the United States does not exceed its capital gain net income from all sources, and therefore paragraph (a)(1) of this section does not require any reduction of C's passive category capital gain. For purposes of section 904, C's passive category includes $4,000 of capital gain net income. C's general limitation category includes a capital loss of $6,000 because only $6,000 of capital loss is allowable as a deduction in the current year. The entire $4,000 of capital loss in excess of the $6,000 of capital loss that offsets capital gain in the taxable year is carried back or forward under section 1212(a), and none of such $4,000 is taken into account under section 904(a) or (b) for the current taxable year.
(i) M, an individual, has $300 of long-term capital gain from foreign sources in the passive category, $200 of which is subject to tax at a rate of 15 percent under section 1(h) and $100 of which is subject to tax at a rate of 28% under section 1(h). M has $150 of short-term capital gain from sources within the United States. M has a $100 long-term capital loss from sources within the United States.
(ii) M's capital gain net income from sources outside the United States ($300) does not exceed M's capital gain net income from all sources ($350). Therefore, paragraph (a)(1) of this section does not require any reduction of M's capital gain net income in the passive category.
(iii) Because M has a net long-term capital loss from sources within the United States ($100) and also has a short-term capital gain from U.S. sources ($150), M must apply the provisions of paragraph (c)(1)(ii) of this section to determine the amount of the $300 of capital gain net income in the passive category that is subject to a rate differential adjustment. Under Step 1, the U.S. long-term capital loss adjustment amount is $100 ($100 − $0). Under Step 2, M must apportion this amount to each rate group in the passive category pro rata based on the amount of capital gain net income in each rate group. Thus, $66.67 ($200/$300 of $100) is apportioned to the 15 percent rate group and $33.33 ($100/$300 of $100) is apportioned to the 28 percent rate group. The applicable rate differential amount for the 15 percent rate group is $133.33 ($200 − $66.67). Thus, $133.33 of the $200 of capital gain net income in the 15 percent rate group is subject to a rate differential adjustment pursuant to paragraph (c)(1) of this section. The remaining $66.67 is not subject to a rate differential adjustment. The applicable rate differential amount for the 28 percent rate group is $66.67 ($100 − $33.33). Thus, $66.67 of the $100 of capital gain net income in the 28 percent rate group is subject to a rate differential adjustment pursuant to paragraph (c)(1) of this section. The remaining $33.33 is not subject to a rate differential adjustment.
(i) N, an individual, has $300 of long-term capital gain from foreign sources in the passive category, all of which is subject to tax at a rate of 15 percent under section 1(h). N has $50 of short-term capital gain from sources within the United States. N has a $100 long-term capital loss from sources within the United States.
(ii) N's capital gain net income from sources outside the United States ($300) exceeds N's capital gain net income from all sources ($250). Pursuant to paragraph (a)(1) of this section, N must reduce the $300 capital gain in the passive category by $50. N has $250 of capital gain remaining in the passive category.
(iii) Because N has a net long-term capital loss from sources within the United States ($100) and also has a short-term capital gain from U.S. sources ($50), N must apply the provisions of paragraph (c)(1)(ii) of this section to determine the amount of the $250 of capital gain in the passive category that is subject to a rate differential adjustment. Under Step 1, the U.S. long-term capital loss adjustment amount is $50 ($100 − $50). Under Step 2, the applicable rate differential amount is $200 ($250 − $50). Thus, $200 of the capital gain in the passive category is subject to a rate differential adjustment under paragraph (c)(1) of this section. The remaining $50 is not subject to a rate differential adjustment.
(i) O, an individual, has a $100 short-term capital gain from foreign sources in the passive category. O has $300 of long-term capital gain from foreign sources in the passive category, all of which is subject to tax at a rate of 15 percent under section 1(h). O has a $100 long-term capital loss from sources within the United States.
(ii) O's capital gain net income from sources outside the United States ($400) exceeds O's capital gain net income from all sources ($300). Pursuant to paragraph (a)(1) of this section, O must reduce the $400 capital gain net income in the passive category by $100. Because C has capital gain net income in two or more rate groups in the passive category, O must apportion such amount, as a reduction, to each rate group on a pro rata basis pursuant to paragraph (a)(1)(ii)(B) of this section. Thus, $25 ($100/$400 of $100) is apportioned to the short-term capital gain and $75 ($300/$400 of $100) is apportioned to the long-term capital gain in the 15 percent rate group. After application of paragraph (a)(1) of this section, O has $75 of short-term capital gain in the passive category and $225 of long-term capital gain in the 15 percent rate group in the passive category.
(iii) Because O has a net long-term capital loss from sources within the United States ($100) and also has a short-term capital gain from foreign sources ($100), O must apply the provisions of paragraph (c)(1)(ii) of this section to determine the amount of the $225 of long-term capital gain in the 15 percent rate group that is subject to a rate differential adjustment. Under Step 1, the U.S. long-term capital loss adjustment amount is $25 ($100 − $75). Under Step 2, the applicable rate differential amount is $200 ($225 − $25). Thus, $200 of the long-term capital gain is subject to a rate differential adjustment under paragraph (c)(1) of this section. The remaining $25 of long-term capital gain is not subject to a rate differential adjustment.
(i) AA, an individual, has items from sources outside the United States only in the passive category for the taxable year. AA has $1000 of long-term capital gains from sources outside the United States that are subject to tax at a rate of 15 percent under section 1(h). AA has $700 of long-term capital losses from sources outside the United States, which are not described in section 1(h)(4)(B)(i) or (iii). For the same taxable year, AA has $800 of long-term capital gains from sources within the United States that are taxed at a rate of 28 percent under section 1(h). AA also has $100 of long-term capital losses from sources within the United States, which are not described in section 1(h)(4)(B)(i) or (iii). AA also has $500 of ordinary income from sources within the United States. The highest tax rate in effect under section 1(h) for the taxable year with respect to long-term capital gains other than long-term capital gains described in section 1(h)(4)(A) or (h)(6) is 15 percent. Accordingly, AA's long-term capital losses are in the 15 percent rate group.
(ii) AA's items of ordinary income, capital gain and capital loss for the taxable year are summarized in the following table:
| U.S. source | Foreign source: passive | |
|---|---|---|
| 15% rate group | ($100) | $1,000 (700) |
| 28% rate group | 800 | |
| Ordinary income | 500 |
(iii) AA's capital gain net income from sources outside the United States ($300) does not exceed AA's capital gain net income from all sources ($1,000). Therefore, paragraph (a)(1) of this section does not require any reduction of AA's capital gain net income in the passive category.
(iv) In computing AA's taxable income from sources outside the United States in the numerator of the section 904(a) foreign tax credit limitation fraction for the passive category, AA's $300 of capital gain net income in the 15 rate group in the passive category must be adjusted as required under paragraph (c)(1) of this section. AA adjusts the $300 of capital gain net income using 15 percent as the alternative tax rate, as follows: $300 (15%/35%).
(v) In computing AA's entire taxable income in the denominator of the section 904(a) foreign tax credit limitation fraction, AA combines the $300 of capital gain net income from sources outside the United States and the $100 net capital loss from sources within the United States in the same rate group (15 percent). AA must adjust the resulting $200 ($300 − $100) of net capital gain in the 15 percent rate group as required under paragraph (c)(2) of this section, using 15 percent as the alternative tax rate, as follows: $200 (15%/35%). AA must also adjust the $800 of net capital gain in the 28 percent rate group, using 28 percent as the alternative tax rate, as follows: $800 (28%/35%). AA must also include ordinary income from sources outside the United States in the numerator, and ordinary income from all sources in the denominator, of the foreign tax credit limitation fraction.
(vi) AA's passive category foreign tax credit limitation fraction is $128.58/$1225.72, computed as follows:
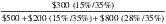
(i) BB, an individual, has the following items of ordinary income, capital gain, and capital loss for the taxable year:
| U.S. source | Foreign source | ||
|---|---|---|---|
| General | Passive | ||
| 15% rate group | $300 | ($500) | $100 |
| 25% rate group | 200 | ||
| 28% rate group | 500 | (300) | |
| Ordinary income | 1,000 | 500 | 500 |
(ii) BB's capital gain net income from sources outside the United States in the aggregate (zero, since losses exceed gains) does not exceed BB's capital gain net income from all sources ($300). Therefore, paragraph (a)(1) of this section does not require any reduction of BB's capital gain net income in the passive category.
(iii) In computing BB's taxable income from sources outside the United States in the numerators of the section 904(a) foreign tax credit limitation fractions for the passive and general limitation categories, BB must adjust capital gain net income from sources outside the United States in each separate category long-tem rate group and net capital losses from sources outside the United States in each separate category rate group as provided in paragraphs (c)(1) and (d) of this section.
(A) The $100 of capital gain net income in the 15 percent rate group in the passive category is adjusted under paragraph (c)(1) of this section as follows: $100 (15%/35%).
(B) BB must adjust the net capital losses in the 15 percent and 28 percent rate groups in the general limitation category in accordance with the ordering rules contained in paragraph (d)(2) of this section. Under paragraph (d)(2)(i) of this section, BB's net capital loss in the 15 percent rate group is netted against capital gain net income from sources outside the United States in other separate categories in the same rate group. Thus, $100 of the $500 net capital loss in the 15 percent rate group in the general limitation category offsets $100 of capital gain net income in the 15 percent rate group in the passive category. Accordingly, $100 of the $500 net capital loss is adjusted under paragraph (d)(1) of this section as follows: $100 (15%/35%).
(C) Next, under paragraph (d)(2)(iii)(A) of this section, BB's net capital losses from sources outside the United States in any separate category rate group are netted against capital gain net income in the same rate group from sources within the United States. Thus, $300 of the $500 net capital loss in the 15 percent rate group in the general limitation category offsets $300 of capital gain net income in the 15 percent rate group from sources within the United States. Accordingly, $300 of the $500 net capital loss is adjusted under paragraph (d)(1) of this section as follows: $300 (15%/35%). Similarly, the $300 of net capital loss in the 28 percent rate group in the general limitation category offsets $300 of capital gain net income in the 28 percent rate group from sources within the United States. The $300 net capital loss is adjusted under paragraph (d)(1) of this section as follows: $300 (28%/35%).
(D) Finally, under paragraph (d)(2)(iii)(B) of this section, the remaining net capital losses in a separate category rate group are netted against capital gain net income from other rate groups from sources within and outside the United States. Thus, the remaining $100 of the $500 net capital loss in the 15 percent rate group in the general limitation category offsets $100 of the remaining capital gain net income in the 28 percent rate group from sources within the United States. Accordingly, the remaining $100 of net capital loss is adjusted under paragraph (d)(1) of this section as follows: $100 (28%/35%).
(iv) In computing BB's entire taxable income in the denominator of the section 904(a) foreign tax credit limitation fractions, BB must adjust net capital gain by netting all of BB's capital gains and losses, from sources within and outside the United States, and adjusting any remaining net capital gains, based on rate group, under paragraph (c)(2) of this section. BB must also include foreign source ordinary income in the numerators, and ordinary income from all sources in the denominator, of the foreign tax credit limitation fractions. The denominator of BB's foreign tax credit limitation fractions reflects $2,000 of ordinary income from all sources, $100 of net capital gain taxed at the 28% rate and adjusted as follows: $100 (28%/35%), and $200 of net capital gain taxed at the 25% rate and adjusted as follows: $200 (25%/35%).
(v) BB's foreign tax credit limitation fraction for the general limitation category is $8.56/$2222.86, computed as follows:
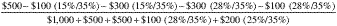
(vi) BB's foreign tax credit limitation fraction for the passive category is $542.86/$2222.86, computed as follows:
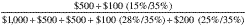
(i) CC, an individual, has the following items of ordinary income, capital gain, and capital loss for the taxable year:
| U.S. source | Foreign source | ||
|---|---|---|---|
| General | Passive | ||
| 15% rate group | $300 | ($720) | ($80) |
| 25% rate group | 200 | ||
| 28% rate group | 500 | (150) | 50 |
| Ordinary income | 1,000 | 1,000 | 500 |
(ii) CC's capital gain net income from sources outside the United States (zero, since losses exceed gains) does not exceed CC's capital gain net income from all sources ($100). Therefore, paragraph (a)(1) of this section does not require any adjustment.
(iii) In computing CC's taxable income from sources outside the United States in the numerators of the section 904(a) foreign tax credit limitation fractions for the passive and general limitation categories, CC must adjust capital gain net income from sources outside the United States in each separate category long-tem rate group and net capital losses from sources outside the United States in each separate category rate group as provided in paragraphs (c)(1) and (d) of this section.
(A) CC must adjust the $50 of capital gain net income in the 28 percent rate group in the passive category pursuant to paragraph (c)(1) of this section as follows: $50 (28%/35%).
(B) Under paragraph (d)(2)(i) of this section, $50 of CC's $150 net capital loss in the 28 percent rate group in the general limitation category offsets $50 of capital gain net income in the 28 percent rate group in the passive category. Thus, $50 of the $150 net capital loss is adjusted as follows: $50 (28%/35%). Next, under paragraph (d)(2)(iii)(A) of this section, the remaining $100 of net capital loss in the 28 percent rate group in the general limitation category offsets $100 of capital gain net income in the 28 percent rate group from sources within the United States. Thus, the remaining $100 of net capital loss is adjusted as follows: $100 (28%/35%).
(C) Under paragraphs (d)(2)(iii)(A) and (d)(2)(iv) of this section, the net capital losses in the 15 percent rate group in the passive and general limitation categories offset on a pro rata basis the $300 of capital gain net income in the 15 percent rate group from sources within the United States. The proportionate amount of the $720 net capital loss ($720/$800 of $300, or $270) is adjusted as follows: $270 (15%/35%). The proportionate amount of the $80 net capital loss ($80/$800 of $300, or $30) is adjusted as follows $30 (15%/35%).
(D) Of the remaining $500 of net capital loss in the 15 percent rate group in the general limitation and passive categories, $400 offsets the remaining $400 of capital gain net income in the 28 percent rate group from sources within the United States under paragraph (d)(2)(iii)(B)(3) of this section. The proportionate amount of the $720 net capital loss ($720/$800 of $400, or $360) is adjusted as follows: $360 (28%/35%). The proportionate amount of the $80 net capital loss ($80/$800 of $400, or $40) is adjusted as follows: $40 (28%/35%).
(E) Under paragraph (d)(2)(iii)(B)(3) of this section, the remaining $100 of net capital loss in the 15 percent rate group in the general limitation and passive limitation categories offsets $100 of capital gain net income in the 25 percent rate group from sources within the United States. The proportionate amount of the $720 net capital loss ($720/$800 of $100, or $90) is adjusted as follows: $90 (25%/35%). The proportionate amount of the $80 net capital loss ($80/$800 of $100 of $10) is adjusted as follows: $10 (25%/35%).
(iv) In computing CC's entire taxable income in the denominator of the section 904(a) foreign tax credit limitation fractions, CC must adjust capital gain net income by netting all of CC's capital gains and losses, from sources within and outside the United States, and adjusting any remaining net capital gains, based on rate group, under paragraph (c)(2) of this section. The denominator of CC's foreign tax credit limitation fractions reflects $2,500 of ordinary income from all sources and $100 of net capital gain taxed at the 25% rate and adjusted as follows: $100 (25%/35%).
(v) CC's foreign tax credit limitation fraction for the general limitation category is $412/$2571.42, computed as follows:
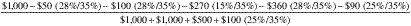
(vi) CC's foreign tax credit limitation fraction for the passive category is $488.00/$2571.42, computed as follows:
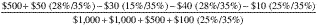
(i) DD, an individual, has the following items of ordinary income, capital gain and capital loss for the taxable year:
| U.S. source | Foreign source | |||
|---|---|---|---|---|
| General | Passive | |||
| 15% rate group | ($80) | ($100) | $300 | |
| Short-term | 500 | 100 | ||
| Ordinary income | 500 | |||
(ii) DD's capital gain net income from outside the United States ($800) exceeds DD's capital gain net income from all sources ($720). Pursuant to paragraph (a)(1)(ii)(A) of this section, DD must apportion the $80 of excess of capital gain net income from sources outside the United States between the general limitation and passive categories based on the amount of capital gain net income in each separate category. Thus, one-half ($400/$800 of $100, or $40) is apportioned to the general limitation category and one-half ($400/$800 of $80, or $40) is apportioned to the passive category. The $40 apportioned to the general limitation category reduces DD's $500 short-term capital gain in the general limitation category to $460. Pursuant to paragraph (a)(1)(ii)(B) of this section, the $40 apportioned to the passive category must be apportioned further between the capital gain net income in the short-term rate group and the 15 percent rate group based on the relative amounts of capital gain net income in each rate group. Thus, one-fourth ($100/$400 of $40 or $10) is apportioned to the short-term rate group and three-fourths ($300/$400 of $40 or $30) is apportioned to the 15 percent rate group. DD's passive category includes $90 of short-term capital gain and $270 of capital gain net income in the 15% rate group.
(iii) Because DD has a net long-term capital loss from sources within the United States ($80) and also has short-term capital gains, DD must apply the provisions of paragraph (c)(1)(ii) of this section to determine the amount of DD's $270 of capital gain net income in the 15% rate group that is subject to a rate differential adjustment under paragraph (c)(1) of this section. Under Step 1, the U.S. long-term capital loss adjustment amount is $50 ($80-$30). Under Step 2, the applicable rate differential amount is the excess of the remaining capital gain net income over the U.S. long-term adjustment amount. Thus, the applicable rate differential amount is $220 ($270 − $50). In computing DD's taxable income from sources outside the United States in the numerator of the section 904(a) foreign tax credit limitation fraction for the passive category, DD must adjust this amount as follows: $220 (15%/35%). DD does not adjust the remaining $50 of capital gain net income in the 15% rate group.
(iv) The amount of capital gain net income in the 15% rate group in the passive category, taking into account the adjustment pursuant to paragraph (a)(1) of this section and disregarding the adjustment pursuant to paragraph (c)(1) of this section, is $270. Under paragraphs (d)(2)(i) and (d)(2)(v) of this section, DD's $100 net capital loss in the 15% rate group in the general limitation category offsets capital gain net income in the 15% rate group in the passive category. Accordingly, the $100 of net capital loss is adjusted as follows: $100 (15%/35%).
(v) In computing DD's entire taxable income in the denominator of the section 904(a) foreign tax credit limitation fractions, DD must adjust capital gain net income by netting all of DD's capital gains and losses from sources within and outside the United States, and adjusting the remaining net capital gain in each rate group pursuant to paragraph (c)(2) of this section. The denominator of DD's foreign tax credit limitation fraction reflects $500 of ordinary income from all sources, $600 of short-term capital gain and $120 of net capital gain in the 15 percent rate group adjusted as follows: $120 (15%/35%).
(vi) DD's foreign tax credit limitation fraction for the general limitation category is $417.14/$1151.43, computed as follows:
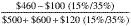
(vii) DD's foreign tax credit limitation fraction for the passive category is $234.29/$1151.43, computed as follows:
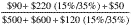
(i) EE, an individual, has the following items of ordinary income, capital gain and capital loss for the taxable year:
| U.S. source | Foreign source | |
|---|---|---|
| Passive | ||
| 15% rate group | ($150) | $300 |
| 28% rate group | 200 | |
| Short-term | 30 | 100 |
| Ordinary income | 500 |
(ii) EE's capital gain net income from sources outside the United States ($600) exceeds EE's capital gain net income from all sources ($480). Pursuant to paragraph (a)(1)(ii) of this section, the $120 of excess capital gain net income from sources outside the United States is allocated as a reduction to the passive category and must be apportioned pro rata to each rate group within the passive category with capital gain net income. Thus, $20 ($100/$600 of $120) is apportioned to the short-term rate group, $60 ($300/$600 of $120) is apportioned to the 15 percent rate group and $40 ($200/$600 of $120) is apportioned to the 28 percent rate group. After application of paragraph (a)(1) of this section, EE has $80 of capital gain net income in the short-term rate group, $240 of capital gain net income in the 15 percent rate group and $160 of capital gain net income in the 28 percent rate group.
(iii) Because EE has a net long-term capital loss from sources within the United States ($150) and also has short-term capital gains, EE must apply the provisions of paragraph (c)(1)(ii) of this section to determine the amount of EE's remaining $400 ($240 + $160) of capital gain net income in long-term rate groups in the passive category that is subject to a rate differential adjustment to a rate differential adjustment. Under Step 1, the U.S. long-term capital loss adjustment amount is $50 ($150-$100). Under Step 2, EE must apportion this amount pro rata to each long-term rate group within the passive category with capital gain net income. Thus, $30 ($240/$400 of $50) is apportioned to the 15 percent rate group and $20 ($160/$400 of $50) is apportioned to the 28 percent rate group. The applicable rate differential amount for the 15 percent rate group is $210 ($240 − $30). The applicable rate differential amount for the 28 percent rate group is $140 ($160 − $20).
(iv) Pursuant to paragraph (c)(1)(ii) of this section, EE must adjust $210 of the $240 capital gain in the 15 percent rate group as follows: $210 (15%/35%). EE does not adjust the remaining $30. Pursuant to paragraph (c)(1)(ii) of this section, EE must adjust $140 of the $160 capital gain in the 28 percent rate group as follows: $140 (28%/35%). EE does not adjust the remaining $20.
(v) In computing EE's entire taxable income in the denominator of the section 904(a) foreign tax credit limitation fractions, EE must adjust capital gain net income by netting all of EE's capital gains and losses from sources within and outside the United States, and adjusting the remaining net capital gain in each rate group pursuant to paragraph (c)(2) of this section. The denominator of EE's foreign tax credit limitation fraction reflects $500 of ordinary income from all sources, $130 of short-term capital gain, $150 of net capital gain in the 15 percent rate group adjusted as follows: $150 (15%/35%), and $200 of net capital gain in the 28 percent rate group adjusted as follows: $200 (28%/35%).
(vi) EE's foreign tax credit limitation fraction for the passive category is $332/$854.29, computed as follows:
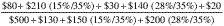
(i) W, an individual, has the following items of ordinary income, capital gain, and capital loss for the taxable year:
| U.S. source | Foreign source | ||
|---|---|---|---|
| General | Passive | ||
| 15% rate group | $500 | $100 | ($400) |
| Ordinary income | 900 | 100 | |
(ii) In computing W's taxable income from sources outside the United States for purposes of section 904 and this section, W must adjust the capital gain net income and net capital loss in each separate category as provided in paragraphs (c)(1) and (d) of this section. Thus, W must adjust the $100 of capital gain net income in the general limitation category and the $400 of net capital loss in the passive category as follows: $100 (15%/35%) and $400 (15%/35%).
(iii) After the adjustment to W's net capital loss in the passive category, W has a $171.43 separate limitation loss in the passive category. After the adjustment to W's capital gain in the general limitation category, W has $142.86 of foreign source taxable income in the general limitation category. Thus, $142.86 of the separate limitation loss reduces foreign source taxable income in the general limitation category. See section 904(f)(5)(B). W adds $142.86 to the separate limitation loss account for the passive category. The remaining $28.57 of the separate limitation loss reduces income from sources within the United States. See section 904(f)(5)(A). Thus, W adds $28.57 to the overall foreign loss account for the passive category.
(i) X, a corporation, has the following items of ordinary income, ordinary loss, capital gain and capital loss for the taxable year: foreign source:
| U.S. source | Foreign source: general | |
|---|---|---|
| Capital gain | ($500) | $700 |
| Ordinary income | 1100 | (1000) |
(ii) X's capital gain net income from sources outside the United States ($700) exceeds X's capital gain net income from all sources ($200). Pursuant to paragraph (a)(1) of this section, X must reduce the $700 capital gain in the general limitation category by $500. After the adjustment, X has $200 of capital gain net income remaining in the general limitation category. Thus, X has an overall foreign loss attributable to the general limitation category of $800.
(iii) For purposes of computing the amount of the addition to X's overall foreign loss account for the general limitation category, the $500 capital loss from sources within the United States is disregarded and X's taxable income from sources within the United States is $1100. Accordingly, X must increase its overall foreign loss account for the general limitation category by $800.
(i) Y, a corporation, has the following items of ordinary income, ordinary loss, capital gain and capital loss for the taxable year:
| U.S. source | Foreign source: passive | |
|---|---|---|
| Capital gain | ($100) | $200 |
| Ordinary income | (200) | 500 |
(ii) Y's capital gain net income from sources outside the United States ($200) exceeds Y's capital gain net income from all sources ($100). Pursuant to paragraph (a)(1) of this section, Y must reduce the $200 capital gain in the passive category by $100. Y has $100 of capital gain net income remaining in the passive category.
(iii) Y is not required to make adjustments pursuant to paragraph (c), (d) or (e) of this section. See paragraphs (b) and (e) of this section. Y's foreign source taxable income in the passive category after the adjustment pursuant to paragraph (a)(1) of this section is $600. Y's entire taxable income for the taxable year is $400.
(iv) Y's section 904(f)(5)(D) amount is the excess of Y's foreign source taxable income in all separate categories in the aggregate for the taxable year after taking into account the adjustment pursuant to paragraph (a)(1) of this section ($600) over Y's entire taxable income for the taxable year ($400). Therefore, Y's section 904(f)(5)(D) amount is $200 and Y's foreign source taxable income in the passive category is reduced to $400. See section 904(f)(5)(D).
(i) Z, an individual, has the following items of ordinary income, ordinary loss and capital gain for the taxable year:
| U.S. source | Foreign source: | ||
|---|---|---|---|
| General | Passive | ||
| 15% rate group | $100 | ||
| Ordinary income | (200) | $300 | $300 |
(ii) Z's foreign source taxable income in all of Z's separate categories in the aggregate for the taxable year is $600. (There are no adjustments to Z's foreign source taxable income pursuant to paragraph (a)(1), (c)(1), (d) or (e) of this section.)
(iii) In computing Z's entire taxable income in the denominator of the section 904(d) foreign tax credit limitation fractions, Z must adjust the $100 of net capital gain in the 15 percent rate group pursuant to paragraph (c)(2) of this section as follows: $100 (15%/35%). Thus, Z's entire taxable income for the taxable year, taking into account the adjustment pursuant to paragraph (c)(2) of this section, is $442.86.
(iv) Z's section 904(f)(5)(D) amount is the excess of Z's foreign source taxable income in all separate categories in the aggregate for the taxable year ($600) over Z's entire taxable income for the taxable year after the adjustment pursuant to paragraph (c)(2) of this section ($442.86). Therefore, Z's section 904(f)(5)(D) amount is $157.32. This amount must be allocated pro rata to the passive and general limitation categories in accordance with section 904(f)(5)(D).
(i) O, an individual, has the following items of ordinary income, ordinary loss and capital gain for the taxable year:
| U.S. source | Foreign source | ||
|---|---|---|---|
| General | Passive | ||
| 15% rate group | $1100 | ($500) | |
| Ordinary income | (1000) | 1000 | $500 |
(ii) In determining O's taxable income from sources outside the United States, O must reduce the $500 capital loss in the general limitation category to $214.29 ($500 × 15%/35%) pursuant to paragraph (d) of this section. Taking this adjustment into account, O's foreign source taxable income in all of O's separate categories in the aggregate is $1285.71 ($1000 − $214.29 + $500).
(iii) In computing O's entire taxable income in the denominator of the section 904(a) foreign tax credit limitation fraction, O must reduce the $600 of net capital gain for the year to $257.14 ($600 × 15%/35%) pursuant to paragraph (c)(2) of this section. Taking this adjustment into account, O's entire taxable income for the year is $757.14 ($500 + $257.14).
(iv) Therefore, O's section 904(f)(5)(D) amount is $528.57 ($1285.71 − $757.14). This amount must be allocated pro rata to O's $500 of income in the passive category and O's $785.71 of adjusted income in the general limitation category in accordance with section 904(f)(5)(D).
[T.D. 9141, 69 FR 43308, July 20, 2004; 69 FR 61761, Oct. 21, 2004]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 904 Limitation on credit
- § 1212 Capital loss carrybacks and carryovers
- § 1 Tax imposed
- § 1201 Repealed
- § 11 Tax imposed
- § 55 Alternative minimum tax imposed
- § 1250 Gain from dispositions of certain depreciable realty
- § 1222 Other terms relating to capital gains and losses
Regulations it cites
Cited by 6 other regulations
- § 1.904(b)-0 Outline of regulation provisions.
- § 1.904(b)-2 Special rules for application of section 904(b) to alternative minimum tax foreign tax credit.
- § 1.904(f)-1 Overall foreign loss and the overall foreign loss account.
- § 1.904(f)-7 Separate limitation loss and the separate limitation loss account.
- § 1.904(g)-1 Overall domestic loss and the overall domestic loss account.
- § 1.904(g)-2 Recapture of overall domestic losses.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended (69 FR 61761)
- Issued by T.D. 9141 (69 FR 43308)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Foreign tax credit
Nearby sections
- § 1.904-5 Look-through rules as applied to controlled foreign corporations and other entities.
- § 1.904-6 Allocation and apportionment of foreign income taxes.
- § 1.904-7 Transition rules.
- § 1.904(b)-0 Outline of regulation provisions.
- § 1.904(b)-1 Special rules for capital gains and losses.
- § 1.904(b)-2 Special rules for application of section 904(b) to alternative minimum tax foreign tax credit.
- § 1.904(b)-3 Disregard of certain dividends and deductions under section 904(b)(4).
- § 1.904(f)-0 Outline of regulation provisions.
- § 1.904(f)-1 Overall foreign loss and the overall foreign loss account.