
Treasury Regulations · 26 CFR
§ 1.907(c)-3. FOGEI and FORI taxes (for taxable years beginning after December 31, 1982).
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 907(c)
Cite as 26 CFR § 1.907(c)-3
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- March 15, 1991 by T.D. 8338
- Issued under
- 26 U.S.C. § 907(c)
- Length
- 2,774 words · about 12 min to read
- Cross-references
- cites 9 Code sections and 5 regulations; cited by 4
FOGEI taxes paid or accrued by the payor/Total foreign taxes paid or accrued by the payor.
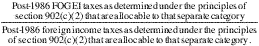
For purposes of these determinations, dividends are deemed to be paid first out of FOGEI and total accumulated profits that arose in taxable years beginning after December 31, 1986. See § 1.907(c)-2(d)(1)(i). See section 960(a)(3) and § 1.960-2 relating to distributions that are treated as dividends for purposes of section 902.
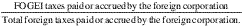
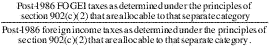
Taxes in the fraction in this paragraph (c)(2) include only those foreign taxes that may be deemed paid under section 960(a) by reason of such inclusion. See §§ 1.960-1(c)(3) and 1.960-2(c).
X, a domestic corporation, owns all of the stock of Y, a foreign corporation organized in country S. Y owns all of the stock of Z, a foreign corporation organized in country T. Each corporation used the calendar year as its taxable year. In 1983, X includes in its gross income an amount described in section 951(a) with respect to Z. Assume that the taxes deemed paid under section 902(a) by X by reason of such an inclusion is $70. Assume further that Z paid total taxes of $120, $80 of which is FOGEI tax. Under paragraph (c) of this section, the FOGEI tax deemed paid is $46.67 (i.e., $70 × $80/$120). This $46.67 is also FOGEI under § 1.907(c)-2(d)(5) because it must be included in X's gross income under section 78.
(i) Assume the same facts as in Example 1. Assume further that in 1983, Z distributes its entire earnings and profits to Y. Y has no earnings and profits during 1983 other than this dividend. Y paid a tax of $50 to S. Assume that Y is deemed under section 902(b)(1) to pay $50 of the tax paid by Z which was not deemed paid by X under section 960(a)(1) in 1983. In 1983, Y distributes its entire earnings and profits to X. Assume that X is deemed under section 902(a) to pay $100 of the taxes actually paid, and deemed paid, by Y.
(ii) Paragraph (b)(1) of this section applies to characterize the $50 tax of Z that Y is deemed to pay under section 902(b)(1). Y is deemed to pay $33.33 of FOGEI tax, i.e., the amount of the tax deemed paid by Y ($50) multiplied by a fraction. The numerator of the fraction is the amount of Z's FOGEI tax ($80) and the denominator is the total taxes paid by Z ($120).
(iii) Under paragraph (a)(8) of this section, a portion of the $50 tax actually paid by Y on the earnings and profits received from Z is FOGEI tax. The amount of tax actually paid by Y that is FOGEI tax depends on the amount of the distribution from Z that is FOGEI (see § 1.907(c)-2(d)(1) (i) and Example 2 (ii) under § 1.907(c)-2(d)(8)). This result does not depend upon whether a portion of the distribution from Z is described in section 959(b) and it follows even though a portion of Y's earnings and profits will be excluded from X's gross income under section 959(a)(1) when distributed by Y. Assume that $12.50 of the $50 tax actually paid by Y is FOGEI tax.
(iv) Under paragraph (b)(1) of this section, X is deemed to pay $45.83 of FOGEI tax by reason of the distribution from Y. This amount is determined by multiplying the total taxes deemed paid by X by reason of such distribution ($100) by a fraction. The numerator of the fraction is the FOGEI tax paid, and deemed paid, by Y ($45.83, i.e., $33.33 under paragraph (ii) of this example plus $12.50 under paragraph (iii) of this example). The denominator of the fraction is the total taxes paid, and deemed paid, by Y ($100). This $45.83 is FOGEI under § 1.907(c)-2(d)(5) because it is included in X's gross income as a section 78 dividend.
(i) X, a domestic corporation, has a concession with foreign country Y that gives it the exclusive right to extract and export the crude oil and natural gas owned by Y. The concession agreement and location of the oil and gas wells mandate that X construct a system of pipelines to transport the minerals that are extracted to a port where they are loaded onto tankers for export. X owns the transportation facilities. Y has an income tax system under which income from mineral operations is subject to a 50 percent tax rate. The taxation by Y of the mineral operations is a separate tax base under paragraph (a)(3) of this section. Under this system, Y imposes the tax at the port prior to export and it establishes a posted price of $12 per barrel. Y also collects royalties of $1.44 per barrel (i.e., 12 percent of this posted price) which is deductible in computing the petroleum tax. Y also allows X deductible lifting costs of $.20 per barrel and deductible transporting costs of $.80 per barrel. Y does not allow any credits against the mineral tax. Assume that X does not have any income in Y other than the mineral income. (In 1983, X extracts, transports, and exports 10,000,000 barrels of crude oil, but for convenience, all computations are in terms of one barrel). X pays foreign taxes of $4.78 per barrel, computed as follows:
| Sales | $12.00 | |
| Royalties | $1.44 | |
| Lifting | .20 | |
| Transporting | .80 | |
| 2.44 | (2.44) | |
| Income base | 9.56 | |
| Tax rate (percent) | .50 | |
| Tax | 4.78 |
Assume that these taxes are creditable taxes under section 901, that the fair market value of the oil at the port is $10 per barrel, and that under § 1.907(c)-1(b)(6) fair market value in the immediate vicinity of the oil wells is $9 per barrel. Thus, at the port, the excess of posted price ($12) over fair market value ($10) is $2.
(ii) The $4.78 foreign tax paid to Y is allocated to FOGEI and FORI in accordance with the rules in paragraph (a)(2) through (5) of this section.
(iii) Under paragraph (a)(3) of this section, FOGEI and FORI are subject to foreign taxation under one tax base. This foreign tax is allocated between FOGEI tax and FORI tax in accordance with paragraph (a)(4) and (5) of this section.
(iv) The modified gross income for FOGEI is $11, i.e., fair market value in the immediate vicinity of the well ($9) plus the excess at the port of posted price over fair market value ($2). The modified gross income for FORI is $1, i.e., value added to the oil beyond the well-head which is part of Y's tax base ($10-$9).
(v) The royalty deductions are all directly attributable to FOGEI.
(vi) Under paragraph (a)(4) of this section, the income of each class is determined as follows:
| FOGEI | FORI | |
|---|---|---|
| Modified gross income | $11.00 | $1.00 |
| Deductions: | ||
| Royalties | 1.44 | 0 |
| Lifting | .20 | 0 |
| Transporting | 0 | .80 |
| Total | 1.64 | .80 |
| Net Income | 9.36 | .20 |
(vii) Under paragraph (a)(4) of this section, the total tax paid to Y is allocated to FOGEI and FORI in proportion to the income in each class. The calculation is as follows:
FOGEI tax = $4.78 × $9.36/$9.56 = $4.68
FORI tax = $4.78 × $0.20/$9.56 = $0.10
Thus, for the 10,000,000 barrels, the FOGEI tax is $46,800,000 and the FORI tax is $1,000,000.
(viii) The allocation under paragraph (a)(4) of this section, rather than the direct application of stated foreign tax rates to foreign-law taxable income in each class of income (which would produce the same results in the facts of this example), is necessary when a foreign country taxes more than one class of income under a progressive rate structure. See Example 4 in this paragraph (e).
Assume the same facts as in Example 3 except that Y's tax is imposed at 40 percent for the first $20,000,000 of income and at 60 percent for all other income. The foreign taxes are allocated under paragraph (a)(4) of this section between FOGEI and FORI in the same manner as in paragraphs (vi) and (vii) of Example 3, as follows:
| (1) Taxable income | $95,600,000 |
| (2) Tax: | |
| (a) 40% of $20,000,000 | 8,000,000 |
| (b) 60% of $75,600,000 | 45,360,000 |
| (c) Total tax | 53,360,000 |
| (3) FOGEI tax (line 2(c) × $9.36/$9.56) | 52,243,680 |
| (4) FORI tax (line 2(c) × $0.20/$9.56) | 1,116,320 |
Assume the same facts as in Example 3. Assume further that X refines the crude oil into primary products prior to export and Y imposes its tax on the basis of crude oil equivalences of $12 per barrel, rather than the value of the primary products, to establish port prices. Assume that this arrangement is a pricing arrangement described in section 907(d). Thus, Y does not tax the refinery income. The results are the same as in Example 3 even if $12 per barrel is equal to, more than, or less than, the value of the primary products at the port. See paragraph (a)(5)(vi) of this section.
[T.D. 8338, 56 FR 11073, Mar. 15, 1991]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 907 Special rules in case of foreign oil and gas income
- § 901 Taxes of foreign countries and of possessions of United States
- § 903 Credit for taxes in lieu of income, etc., taxes
- § 959 Exclusion from gross income of previously taxed earnings and profits
- § 951 Amounts included in gross income of United States shareholders
- § 1248 Gain from certain sales or exchanges of stock in certain foreign corporations
- § 960 Deemed paid credit for subpart F inclusions
- § 78 Gross up for deemed paid foreign tax credit
- § 902 Repealed
Regulations it cites
- § 1.907(c)-1 Definitions relating to FOGEI and FORI (for taxable years beginning after December 31, 1982).
- § 1.907(b)-1 Reduction of creditable FORI taxes (for taxable years beginning after December 31, 1982).
- § 1.907(c)-2 Section 907(c)(3) items (for taxable years beginning after December 31, 1982).
- § 1.960-2 Foreign income taxes deemed paid under sections 960(a) and (d).
- § 1.960-1 Overview, definitions, and computational rules for determining foreign income taxes deemed paid under section 960(a), (b), and (d).
Cited by 4 other regulations
- § 1.907-0 Outline of regulation provisions for section 907.
- § 1.907(a)-0 Introduction (for taxable years beginning after December 31, 1982).
- § 1.907(b)-1 Reduction of creditable FORI taxes (for taxable years beginning after December 31, 1982).
- § 1.907(c)-2 Section 907(c)(3) items (for taxable years beginning after December 31, 1982).
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 8338 (56 FR 11073)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Foreign tax credit
Nearby sections
- § 1.907(a)-1 Reduction in taxes paid on FOGEI (for taxable years beginning after December 31, 1982).
- § 1.907(b)-1 Reduction of creditable FORI taxes (for taxable years beginning after December 31, 1982).
- § 1.907(c)-1 Definitions relating to FOGEI and FORI (for taxable years beginning after December 31, 1982).
- § 1.907(c)-2 Section 907(c)(3) items (for taxable years beginning after December 31, 1982).
- § 1.907(c)-3 FOGEI and FORI taxes (for taxable years beginning after December 31, 1982).
- § 1.907(d)-1 Disregard of posted prices for purposes of chapter 1 of the Code (for taxable years beginning after December 31, 1982).
- § 1.907(f)-1 Carryback and carryover of credits disallowed by section 907(a) (for amounts carried between taxable years that each begin after December 31, 1982).