
Treasury Regulations · 26 CFR
§ 1.9200-1. Deduction for motor carrier operating authority.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Cite as 26 CFR § 1.9200-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- March 6, 1984 by T.D. 7947
- Last amended
- March 29, 1984
- Length
- 2,760 words · about 12 min to read
- Defines
- 4 terms
- Cross-references
- cites 7 Code sections and 1 regulation; cited by 1
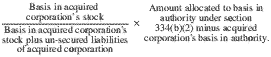
In addition, if the aggregate basis of the assets of the acquired corporation other than the authority as of July 1, 1980 (reduced by the liabilities secured by such assets) exceeds the qualified acquiring party's basis in the stock of the acquired corporation remaining after application of the preceding sentence, then the bases of such assets shall be reduced proportionately so that their aggregate basis as of such date (minus secured liabilities) is equal to such remaining stock basis. If the acquired corporation held the authority indirectly, appropriate basis reductions shall be made to reflect the transfers deemed to have occurred under paragraph (e)(iv) of this section.
(i) Corporation X acquired all the stock of corporation Y for $130,000 in 1970. Y's assets at the time of acquisition consisted of a motor carrier operating authority valued at $180,000 in which it has a basis of $60,000, trucks with a fair market value of $70,000 and an aggregate basis of $30,000, and goodwill valued at $30,000. Y has $50,000 of liabilities secured by the trucks and $100,000 of unsecured liabilities. Both X and Y use a June 30 fiscal year for tax purposes.
(ii) Y is the only taxpayer eligible to claim a deduction under § 1.9200-1(b). If X sold its Y stock to Z in October 1980 (other than pursuant to a binding contract in effect on July 1, 1980), Y would continue to be the only taxpayer eligible to claim the deduction. However, if Y sold the operating authority to W in February 1981, neither Y nor W would be eligible to claim the monthly deduction for the remainder of the 60-month period. Also, Y would realize gain or loss on the sale after reducing its basis in the authority by any amortization claimed for the period prior to the sale.
(iii) Y must begin the 60-month period in July 1980 unless it elects under paragraph (c)(1)(ii) of this section to begin the 60-month period with the first month of the first taxable year beginning after July 1, 1980, which in Y's case would be July 1981.
(iv) Y's allowable monthly deduction is equal to its adjusted basis in the operating authority of $60,000, divided by 60, or $1,000. However, Y may elect under § 1.9200-1(e)(2) to allocate to its basis in the authority a portion of X's basis in Y stock, since X is a qualified acquiring party under paragraph (e)(2)(i) of this section and Y is a member of an affiliated group of which X is a member. Assuming Y makes the election, Y may allocate to the basis of the authority the amount of X's basis in Y stock that would have been allocable under section 334(b)(2) if X had received the authority in a distribution of all of Y's assets in a complete liquidation of Y immediately after X acquired Y's stock.
Therefore, for purposes of the allocation, X's $130,000 cost basis in Y stock is deemed to be increased by Y's $100,000 of unsecured liabilities to $230,000. Of the $230,000 deemed basis, $180,000 is allocated to the authority, $30,000 to goodwill, and $20,000 to the trucks. Y's allowable monthly amortization deduction would be $180,000 divided by 60, or $3,000. X's $130,000 cost basis in its Y stock must be decreased to $62,174 as provided in paragraph (e)(2)(vi) of this section. Y's $30,000 aggregate basis in its trucks remains unchanged.
Assume the same facts as in Example (1), except that Y's aggregate basis in the trucks is $120,000. If Y makes the election under § 1.9200-1(e)(2), the same allocation as in Example (1) would occur. However, in addition to the decrease in X's basis in its Y stock to $62,174, the $120,000 aggregate basis in the trucks must be reduced to $112,174 (so that the $112,174 basis minus secured liabilities of $50,000 is equal to X's $62,174 remaining stock basis).
Assume the same facts as in Example (1), except that X pays a negotiated purchase price of $120,000 for the Y stock, in order to take into account an anticipated tax liability of $10,000, relating to potential section 1245 recapture. If Y makes the election under § 1.9200-1(e)(2), then for purposes of allocating X's basis in Y stock, X's cost basis is deemed to be increased by Y's $100,000 of unsecured liabilities as well as the $10,000 of potential tax liability resulting from section 1245 recapture, to $230,000. The $10,000 of potential recapture tax is treated as a general liability and the deemed basis is allocated among Y's assets as in Example (1). In order to take into account the potential recapture tax liability, such amount must be based on the same fair market values that are used to determine the amount of the stock basis allocable to the operating authority.
(Sec. 266, Economic Recovery Tax Act of 1981 (Pub. L. 97-34; 95 Stat. 265); sec. 517, Highway Revenue Act of 1982 (Pub. L. 97-424; 96 Stat. 2097); and sec. 7805, Internal Revenue Code of 1954 (68A Stat. 917; 26 U.S.C. 7805)
[T.D. 7947, 49 FR 8247, Mar. 6, 1984; 49 FR 12244, Mar. 29, 1984]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 381 Carryovers in certain corporate acquisitions
- § 1012 Basis of property—cost
- § 334 Basis of property received in liquidations
- § 1504 Definitions
- § 368 Definitions relating to corporate reorganizations
- § 1245 Gain from dispositions of certain depreciable property
- § 7805 Rules and regulations
Regulations it cites
Cited by 1 other regulation
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended (49 FR 12244)
- Issued by T.D. 7947 (49 FR 8247)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Tax Reform Act of 1969
Nearby sections
- § 1.9006 Statutory provisions; Tax Reform Act of 1969.
- § 1.9006-1 Interest and penalties in case of certain taxable years.
- § 1.9101-1 Permission to submit information required by certain returns and statements on magnetic tape.
- § 1.9200-1 Deduction for motor carrier operating authority.
- § 1.9200-2 Manner of taking deduction.
- § 1.9300-1 Reduction in taxable income for housing displaced individuals.