
Treasury Regulations · 26 CFR
§ 48.4216(b)-4. Constructive sale price; affiliated corporations.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 4216(b)
Cite as 26 CFR § 48.4216(b)-4
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- April 23, 1979 by T.D. 7613
- Last amended
- August 15, 1979
- Issued under
- 26 U.S.C. § 4216(b)
- Length
- 1,264 words · about 5 min to read
- Defines
- 2 terms
- Cross-references
- cites 3 Code sections and 2 regulations; cited by 0
Under such circumstances the constructive sale price for the article shall be an amount equal to 90 percent of the lowest price for which the distributor regularly sells the article in arm's-length transactions to such independent retailers. Once the constructive sale price has been determined, no adjustment shall be made for sections 4216 (a) and (f) inclusions or exclusions or section 6416(b)(1) price readjustments. If both section 4216(b)(3) and section 4216(b)(4) apply with respect to the sale of an article, the constructive sale price for such article shall be the lower of the prices computed under section 4216(b)(3) and section 4216(b)(4).
Section 4216(b)(4) applies with respect to articles taxable under section 4061(a) (relating to trucks, buses, etc.) only as to sales after December 31, 1969, and before January 1, 1971. Under section 4216(b)(4), the constructive sale price of such article shall be the median price at which the distributor, at the time of the sale by the manufacturer, resells the article to retail dealers, reduced by a percentage of such price equal to the percentage which:
For purposes of this paragraph, the “median price” for which an article is sold at a particular level of distribution is the price midway between the highest and lowest prices charged vendees at the particular level of distribution. Where only one price is charged at a level of distribution, “median price” is equivalent to “actual price”. All sale prices referred to in paragraphs (b), (c), (d), and (e) of this section are prices that must reflect the inclusions and exclusions set forth in sections 4216(a) and (f). However, once a constructive sale price has been determined under these paragraphs, no further adjustment of such price is allowed.
a corporation engaged in the manufacture of article X, sold 100 of such articles at $10.00 per article to a wholesale distributor N, a corporation engaged in the business of selling X articles to independent retail dealers. N is a member of the same affiliated group of corporations as M. M sells X articles only to N. The normal method of manufacturers' sales of X articles in the industry is to sell to independent wholesale distributors. N corporation sells X articles to retailers for $15.00 each. The price for which comparable X articles are sold to wholesale distributors in the ordinary course of trade by manufacturers thereof is $12.00 per article. Wholesale distributors sell X articles to retailers in the ordinary course of trade for $16.00 per article. Under the foregoing facts the constructive sale price determined under section 4216(b)(4) and this paragraph is $11.25, computed as follows:
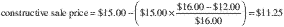
Under such circumstances the constructive sale price of such articles shall be 98 1/2 percent of the lowest price for which such distributor regularly sells the article in arms's-length transactions to the independent retail dealers. Once the constructive sale price has been determined, no adjustment shall be made for section 4216 (a) and (f) inclusions or exclusions or section 6416(b)(1) price readjustments.
[T.D. 7613, 44 FR 23826, Apr. 23, 1979; 44 FR 47767, Aug. 15, 1979]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
Regulations it cites
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended (44 FR 47767)
- Issued by T.D. 7613 (44 FR 23826)
Where it sits in 26 CFR
- Subchapter D Miscellaneous excise taxes
- Part 48 Manufacturers and retailers excise taxes
- Subpart M Special Provisions Applicable to Manufacturers Taxes
Nearby sections
- § 48.4216(a)-3 Other items relating to tax on sale price.
- § 48.4216(b)-1 Constructive sale price; scope and application.
- § 48.4216(b)-2 Constructive sale price; basic rules.
- § 48.4216(b)-3 Constructive sale price; special rule for arm's-length sales.
- § 48.4216(b)-4 Constructive sale price; affiliated corporations.
- § 48.4216(c)-1 Computation of tax on leases and installment sales.
- § 48.4216(d)-1 Sales of installment accounts.
- § 48.4216(e)-1 Exclusion of local advertising charges from sale price.
- § 48.4216(e)-2 Limitation on aggregate of exclusions and price readjustments.