
Treasury Regulations · 26 CFR
§ 6a.103A-2. Qualified mortgage bond.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 103A
Cite as 26 CFR § 6a.103A-2
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- July 1, 1981 by T.D. 7780
- Last amended
- June 18, 1993 by T.D. 8476
- Issued under
- 26 U.S.C. § 103A
- Length
- 12,934 words · about 56 min to read
- Defines
- 15 terms
- Cross-references
- cites 11 Code sections and 3 regulations; cited by 5
A qualified mortgage bond does not include any bond that is an industrial development bond under section 103(b).
This determination shall be based upon the most recent data availabe. The certification described in subdivision (iv)(C) shall satisfy the criteria set forth in subdivisions (C) and (D). A certification described in (iv)(D) shall satisfy the criteria set forth in subdivisions (A) and (B): Provided, That the majority of the households in the proposed area have incomes less than 80 percent of the median income for the standard metropolitan statistical area (SMSA) in which the proposed area is located or, if the proposed area is not within a SMSA, less than 80 percent of the median income for the State.
For purposes of subdivisions (ii) and (iii) of this subparagraph, in Alaska, the entire State, and in Louisiana, a parish, shall be treated in a manner similar to a county.
A contracts with B, a builder of single-family residences, for the purchase of a residence. Under the terms of the contract, B will deliver a residential unit to A that contains an uncompleted recreation room and an unfinished third floor and which lacks a garage. Normally, a completed recreation room, a finished third floor and a garage are provided as part of the residence built by B. The contract price for the residence is $58,000. At the same time, A contracts with C, an affiliate of B, to complete the recreation room and third floor and to construct the garage for a contract price of $10,000. C will perform this work after A receives title to the unit from B. Under § 6a.103A-2(b)(8)(i)(A), the acquisition cost of A's completed residential unit is $68,000, which represents the contract price of the residence plus the cost of completion of the recreation room and third floor and construction of the garage.
E owns a single-family residence which E has listed for sale. D contracts to purchase E's residence, and the contract provides for a selling price of $30,000. D also agrees to pay an unsecured debt in the amount of $5,000, which E owes to X, a local bank. D further agrees to purchase from E the refrigerator, stove, washer, and dryer located in E's residence for $500. Such amount is equal to the fair market value of such personalty. D also agrees to purchase the light fixtures, curtain rods, and wall-to-wall carpeting for a fair market value price of $700. Under § 6a.103A-2(b)(8)(i)(A), the acquisition cost of D's completed residential unit is $35,700. Such amount includes the $5,000 unsecured debt paid off by D. The $500 paid for the refrigerator, stove, washer, and dryer are not included because such items are not included within the definition of a residence under § 6a.103A-2(d)(4). Such definition does include, however, the light fixtures, curtain rods, and wall-to-wall carpeting purchased by D.
F contracts with G to purchase G's home for $40,000. After purchasing the residence, F pays a party unrelated to G $3,000 for painting, minor repairs, and refinishing the floors. Under § 6a.103A-2(b)(8)(i)(A), the acquisition cost of the residence is $40,000. Such fix-up expenses are not treated as part of the acquisition costs. If G had incurred such fix-up expenses, however, F may not reduce his acquisition cost of the residence by such amounts.
Then the allowable amount of the subsequent qualified home improvement loan shall be reduced by the amount, at origination, of any previous qualified home improvement loan, so that the sum of such loans does not exceed $15,000.
A and B jointly own a residence located in Town M. They obtain a qualified home improvement loan for $10,000 from Town M. A acquires B's interest in the residence. A applies to State X for a qualified home improvement loan. The maximum amount of a qualified home improvement loan which may be made by State X is $5,000, the amount that when added to the $10,000 previous loan from Town M does not exceed $15,000.
But only if the mortgagor to whom such financing is provided is the first resident of the residence after completion of the rehabilitation. Where there are two or more mortgagors of a rehabilitation loan, the first residency requirement is met if any of the mortgagors meets the first residency requirement.
State X issues obligations to be used to provide mortgages for owner-occupied residences. X contracts with bank M to originate and service the mortgages. The trust indenture and participation agreement require that the mortgages meet the mortgage eligibility requirements referred to in paragraph (c)(1). In addition, pursuant to procedures established by X, M obtains a signed affidavit from each applicant that the applicant intends to occupy the property as his or her principal residence within 60 days after the final closing and thereafter to maintain the property as his or her principal residence. Further, M obtains from each applicant copies certified by the Internal Revenue Service of the applicant's Federal tax returns for the preceding 3 years and examines each statement to determine whether the applicant has claimed a deduction for taxes on real property which was the applicant's principal residence pursuant to section 164(a)(1) or a deduction pursuant to section 163 for interest paid on a mortgage secured by real property which was the applicant's principal residence. Also in accordance with X's procedures, M obtains from each applicant a signed affidavit as to facts that are sufficient for M to determine whether the residence is located within X's jurisdiction and affidavits from the seller and the buyer that the purchase price and the new mortgage requirements have been met, and neither M nor X knows or has reason to believe that such affidavits are false. The mortgage instrument provides that the mortgage may not be assumed by another person unless X determines that the principal residence, 3-year, and purchase price requirements are met at the time of the assumption. These facts are sufficient evidence of the good faith of the issuer and meet the requirements of paragraph (c)(1)(i). Further, if 95 percent of the lendable proceeds are devoted to owner financing which according to these procedures meet the requirements of paragraphs (d), (e), (f), and (i), then the issue meets the requirements of paragraph (c)(1)(ii).
State Y issues obligations to be used to provide mortgages for owner-occupied residences. Y contracts with bank N to originate and service the mortgages. The trust indenture and participation agreement require that the mortgagor certify compliance with the requirements referred to in paragraph (c)(1). By itself, this certification is not sufficient evidence of the good faith of the issuer to meet the requirements referred to in paragraph (c)(1).
The facts are the same as in Example 1, except that M discovers through a verification procedure required by X that, at the time of closing, A fraudulently executed the residencey affidavit. Instead of occupying the property as a principal residence, A leased the property to B for one year. A did not use the property as his residence during the lease term. Thus, at the time that A's mortgage was executed the residence failed to meet the requirements of paragraph (d) of this section.
More than 95 percent of the lendable proceeds of the issue were devoted to residences which met all the requirements referred to in paragraph (c)(1) at the time the mortgages were executed. Furthermore, pursuant to a provision in the mortgage instrument M called the loan. Any failures with respect to other mortgages are corrected by M. Based on these facts, the issue meets the requirements of subparagraph (c)(1).
The facts are the same as in Example (1), except that the issuer requires copies of the applicant's signed tax returns that were filed with the Internal Revenue Service for the preceding 3 years but does not require that such returns be certified. If 95 percent of the lendable proceeds are devoted to owner financing which according to these procedures meet the requirements of paragraphs (d), (e), (f), and (i), then the issue meets the requirements of paragraph (c)(1)(ii).
City X issues obligations to finance owner-occupied residences. However, despite taking all reasonable steps to determine accurately the size of the market share limitation, as provided in paragraph (g)(3), the limit is exceeded because the amount of the mortgages originated in the area during the past 3 years is incorrectly computed as a result of mathematical error. Such facts are sufficient evidence of the good faith of the issuer to meet the requirements of paragraph (c)(2).
City Y issues $25 million of bonds to finance single-family, owner-occupied homes. Attorney A gives an opinion that the bonds satisfy the arbitrage requirements of § 6a.103A-2(i) and § 6a.103A-1(a)(3). In fact, however, the legal conclusion reached by A is erroneous, and the bonds do not meet the requirements of § 6a.103A-2(i). The issue does not meet the requirements of subparagraph (c)(2) because the erroneous opinion does not constitute inadvertent error.
A contracts to purchase a new residence from B. Since B is unable to move from the residence until 1 month after the scheduled closing date, A agrees to lease the residence to B for 1 month at a rent equal to the fair rental value. A applies for a mortgage to be provided from the proceeds of a qualified mortgage bond. In light of all the facts and circumstances in the case, the fact that A temporarily leases the residence to B does not prevent the residence from being considered as property that can reasonably be expected to be used as A's principal residence within a reasonable period of time after financing is provided.
C contracts to purchase a new residence located on 2 acres of land in city X. City X has a zoning regulation which prevents the subdividing of any lot in that part of the city for use as a private residence into parcels of less than 2 acres. In light of all the facts and circumstances in the case, the fact that the residence is located on 2 acres of land appurtenant to the residence does not prevent the entire property from being considered as property to be used by C as a residence.
D contracts to purchase a new residence located on 40 acres of land that D intends to farm. Any financing provided for the purchase of that portion of the property intended to be farmed will not be considered as financing provided for an owner-occupied residence.
The average area purchase price safe harbor limitation for new single-family residences published by the Treasury Department for the second half of 1981 for the jurisdiction of governmental unit X is $41,500. However, on July 1, 1981, X determines that its average area purchase price for new single-family residences is actually $43,000. Such determination is based on a comprehensive survey of residential housing sales in the jurisdiction over the previous calendar year. The data accumulated are based on records maintained by the county clerk's office in X's jurisdiction, which enables X to compute average area purchase prices separately for new and used residences and for one-, two-, three-, and four-family residences. X cannot reasonably update such data more often than once a year. X may use average area purchase prices computed from these data for mortgages made from July 1, 1981, through June 30, 1982, rather than the safe harbor published by the Treasury Department.
Only single-family owner-occupied residences (without regard to the definition of such term under § 6a.103A-1(b)(6)) may be used in determining the market limitation regardless of whether or not residences with up to four family units are to be financed by the program. First and second mortgages or mortgages used to refinance an existing mortgage shall be used in making such determination. Liens, special assessments, and similar encumbrances may not be taken into consideration.
Pursuant to the allocation rule provided in subparagraph (3), City Y determines that its maximum market limitation in 1981 is $15,000,000. This determination is based on records maintained by the county clerk's office from which data for the preceding 3 years have been accumulated by City Y as to the number of sales of single-family homes in City Y's jurisdiction, the purchase price in each such sales transaction, the number of such sales that were financed by mortgages and the volume of second mortgages and refinancing on previously purchased owner-occupied single-family residences. This information, combined with estimates made by City Y of the average mortgage-loan-to-purchase-price ratio and the ratio of sales of single-family, owner-occupied residences to all sales of single-family residences from a representative sample of sales transactions, enables Y to estimate the preceding 3 years' annual aggregate mortgage volume by using the following formula:
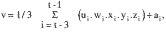
where
v = The preceding 3 years' average annual aggregate volume of mortgages on single-family, owner-occupied residences in City Y,
ui = Number of sales of single-family residences,
wi = Average purchase price of all sales,
xi = Percent of all sales transactions that were financed with mortgages,
yi = Estimated average mortgage-loan-to-purchase-price ratio,
zi = Estimated percent of sales that were owner-occupied residences,
ai = Total volume of second mortgages and refinancing on previously purchased owner-occupied, single-family residences,
i = The annual period of calculation, and
t = The current year.
City Y determines its applicable limit for 1981 based on the following formula:
L = 0.5 (v/s) r, where
L = Market limitation for City Y for the current year,
s = The preceding 3 years' average annual aggregate volume of mortgages on single-family, owner-occupied residences in State X, and
r = Ceiling for State X (i.e., r = the greater of .09s or $200,000,000).
City Y may use the Treasury estimate of s which will be published with the mortgage volume safe harbor limitation. City Y may rely on its determination of its market limitation for obligations issued during 1981.
If, on or before either date, the governor of any State exercises the authority to provide a different allocation, such allocation shall be effective until the date specified in (B).
Proceeds are considered first made available with respect to targeted area residences on the date on which any financing of mortgages with the lendable proceeds of an issue first becomes available. Reasonable diligence requires that the issuer and the loan originators use reasonable efforts in trying to place mortgages in targeted areas, such as by advertising that mortgage funds are available for targeted areas. Reasonable diligence is not shown by merely providing in the governing instruments that the required amount be set aside for targeted areas.

where
P = Required portion to be made available in targeted areas,
X = Average annual aggregate principal amount of mortgages executed during the immediately preceding 3 calendar years for single-family, owner-occupied residences within the State in which the issuing jurisdiction is located,
Y = The total population within the State, based on the most recent decennial census for which data are available, and
Z = The total population in the targeted areas located within the issuer's jurisdiction, based on the most recent decennial census for which data are available.
The issuing jurisdiction may use the Treasury Department estimate of X which will be published with the mortgage volume safe harbor limitation.
is not greater over the term of the issue than 1 percentage point.
Purchaser A contracts with seller B, who is represented by real estate agent C, for the purchase of B's residence for $65,000. A applies to County X for a mortgage provided by the proceeds of a qualified mortgage bond. County X requires that agent C provide it with a principal residence affidavit as well as verify the purchase price of the residence and the location of the purchasers previous residences. Due to the increased administrative burden imposed on agent C by County X, C charges B a real estate commission of 8 percent ($5,200), rather than 6 percent ($3,900). The normal real estate commission is 6 percent. Since the 8 percent commission charged by C and paid by B is in excess of the usual and reasonable real estate commission where owner financing is not provided through the use of qualified mortgage bonds, 2 percent ($1,300) shall be treated as borne by A and taken into account in calculating the effective rate of interest on the mortgage.
The expected maturity will be considered consistent with such prepayment assumption if all prepayments are assumed to be used to call bonds proportionately (i.e., a “strip” call). The preceding sentence shall not apply to prepayments of mortgages provided from original proceeds to the extent such prepayments are used to provide mortgages.
The amount subject to the maximum investment rule in subdivision (i)(A) of this subparagraph includes the original bond proceeds, investment proceeds and repayments of principal on the mortgages. For purposes of subdivision (B), the amount described in subdivision (A) shall be considered promptly and appropriately reduced if beginning in the first bond year after the expiration of the temporary period for original proceeds described in subdivision (ii)(A) of this subparagraph, such amount is reduced within 30 days of the beginning of each bond year by an amount equal to the difference between the average scheduled monthly mortgage receipts for the bond year (excluding any receipts that were scheduled with respect to mortgages that were discharged in the preceding bond year) and the average scheduled monthly mortgage receipts for the preceding bond year.
shall be paid or credited to the mortgagors as rapidly as practicable. Such amount may be disproportionately distributed to the mortgagors if the larger portion of such amount is distributed to lower income mortgagors. The determination of the excess described in subdivision (A) shall take into account any reinvestment of nonmortgage investment receipts and any gain or loss realized on the disposition of nonmortgage investments. In addition, where nonmortgage investments are retained by the issuer after retirement of an issue, any unrealized gains or losses as of the date of retirement of such issue must be taken into account, in calculating the amount to be rebated to the mortgagors. The amount described in subdivision (A)(2) is the amount that would have been earned if the investments in nonmortgage obligations were invested at a rate equal to the yield on the issue calculated in the same manner as provided in § 6a.103A-2(i)(2)(vi) and by using the same compounding method. For purposes of subdivision (B), any income attributable to the excess described in subdivision (A) shall be taken into account whether or not such income exceeds the yield on the bonds.
In 1981, County X issues obligations to provide mortgages for owner-occupied residences. The yield paid on the obligations is 10 percent, and the effective rate of interest on the mortgages provided by the proceeds of such obligations is 9.75 percent. X maintains a reasonably required reserve fund which is invested at 15 percent and intends to recover that additional amount computed in the manner described in subparagraph (4)(iv) which could have been earned from investment of the proceeds in mortgages with an effective interest rate of 11 percent from the arbitrage earned from the reserve fund nonmortgage assets. X plans to recover such amount from the arbitrage over a period of 3 years; thus, X will not recover such amount until 1984. X may not adjust the amount to be received to account for the time when such amount will be received.
shall not be treated as the acquisition or replacement of an existing mortgage. Generally, temporary initial financing is any financing which has a term of 24 months or less.
In June 1981 mortgagor A obtained a mortgage from a private lending institution in order to construct a house on land which A purchased without a mortgage in May 1981. In January 1982 A applies to obtain permanent financing on the residence from a program sponsored by State housing finance agency Y. Such program is funded with the proceeds of qualified mortgage bonds. If A meets the other requirements of this section, A qualifies for such permanent financing since the replacing of construction financing is not treated as the acquisition or replacement of an existing mortgage.
In June 1981 mortgagor B purchased a new residence in a targeted area but was unable to sell his former residence. Therefore, B obtained temporary financing for his new residence until his former residence was sold. In October 1981 B applies to County Z to obtain financing from a program funded with proceeds of qualified mortgage bonds. Such financing is needed by B to replace the temporary financing for his new residence. If B meets the other requirements of this section, the mortgage qualifies for such permanent financing since the permanent financing replaces temporary initial financing.
In 1979 mortgagor C purchased a residence but was unable to obtain financing from a program sponsored by County W because such program prohibited loans from the program which were in excess of 80 percent of the fair market value of the property. Therefore, in 1979 C obtained financing from a private lending institution with the intention of refinancing when he accumulated sufficient equity in the property. In 1981 C has accumulated sufficient equity in the property so as to comply with the requirements of the program. C applies to County W to refinance under the program, which is funded with the proceeds of qualified mortgage bonds. Even if C met the other requirements of this section, the mortgage would fail to meet the requirement of paragraph (j) since such a mortgage would replace an existing mortgage.
In 1969 mortgagor D purchased a residence and obtained financing from a private lending institution. In 1981 D applies to County U for a loan for the rehabilitation of the property and for the refinancing of the existing mortgage. The program is funded with qualified mortgage bonds. If D meets the other requirements of this section the mortgage qualifies for such permanent financing since the replacement of the mortgage is not treated as the replacement or acquisition of an existing mortgage.
In 1950 mortgagor E purchased a residence, obtaining a mortgage from a private lending institution to finance the purchase price. In 1980 E completed repaying the mortgage. In 1981 E applies for a loan from a program sponsored by State housing finance agency X and funded with the proceeds of qualified mortgage bonds. The mortgage does not meet the requirements of paragraph (j) since E had a previous mortgage on his residence, even though such mortgage was previously released.
(98 Stat. 901 (26 U.S.C. 103A(j) (3) and (4)); 68A Stat. 917 (26 U.S.C. 7805))
[T.D. 7780, 46 FR 34314, July 1, 1981, as amended by T.D. 7794, 46 FR 55514, Nov. 10, 1981; T.D. 7817, 47 FR 22361, May 24, 1982; T.D. 7819, 47 FR 24701, June 8, 1982; T.D. 7821, 47 FR 28094, June 29, 1982; T.D. 7995, 49 FR 48293, Dec. 12, 1984; T.D. 8023, 50 FR 19355, May 8, 1985; T.D. 8049, 50 FR 35547, Sept. 3, 1985; T.D. 8476, 58 FR 33553, June 18, 1993]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
- acquisition cost § 6a.103A-2(b)(8)(i)
- acquisition cost § 6a.103A-2(b)(8)(ii)
- area of chronic economic distress § 6a.103A-2(b)(5)(i)
- average area purchase price § 6a.103A-2(f)(3)
- census tract § 6a.103A-2(b)(4)(iii)
- constitutional home rule city § 6a.103A-2(b)(2)
- issue price § 6a.103A-2(i)(2)(vi)(B)
- qualified census tract § 6a.103A-2(b)(4)(i)
- qualified home improvement loan § 6a.103A-2(b)(9)(i)
- qualified mortgage bond § 6a.103A-2(b)(1)
- qualified rehabilitation § 6a.103A-2(b)(10)(ii)
- qualified rehabilitation loan § 6a.103A-2(b)(10)(i)
- residence § 6a.103A-2(d)(4)(i)
- statistical area § 6a.103A-2(b)(7)
- targeted area residence § 6a.103A-2(b)(3)
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 103 Interest on State and local bonds
- § 48 Energy credit
- § 1221 Capital asset defined
- § 6012 Persons required to make returns of income
- § 164 Taxes
- § 163 Interest
- § 280A Disallowance of certain expenses in connection with business use of home, rental of vacation homes, etc.
- § 216 Deduction of taxes, interest, and business depreciation by cooperative housing corporation tenant-stockholder
- § 25 Interest on certain home mortgages
- § 103A Repealed
- § 7805 Rules and regulations
Regulations it cites
- § 6a.103A-1 Interest on mortgage subsidy bonds.
- § 301.6103(c)-1 Disclosure of returns and return information to designee of taxpayer.
- § 1.103A-2 Qualified mortgage bond.
Cited by 5 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 8476 (58 FR 33553)
- Amended by T.D. 8049 (50 FR 35547)
- Amended by T.D. 8023 (50 FR 19355)
- Amended by T.D. 7995 (49 FR 48293)
- Amended by T.D. 7821 (47 FR 28094)
- Amended by T.D. 7819 (47 FR 24701)
- Amended by T.D. 7817 (47 FR 22361)
- Amended by T.D. 7794 (46 FR 55514)
- Issued by T.D. 7780 (46 FR 34314)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 6a Temporary regulations under title ii of the omnibus reconciliation act of 1980