
Treasury Regulations · 26 CFR
§ 1.1015-5. Increased basis for gift tax paid.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 1015
Cite as 26 CFR § 1.1015-5
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- December 3, 1963 by T.D. 6693
- Last amended
- August 22, 1995 by T.D. 8612
- Issued under
- 26 U.S.C. § 1015
- Length
- 4,043 words · about 18 min to read
- Cross-references
- cites 13 Code sections and 3 regulations; cited by 2
In 1938, A purchased a business building at a cost of $120,000. On September 2, 1958, at which time the property had an adjusted basis in A's hands of $60,000, he gave the property to his nephew, B. At the time of the gift to B, the property had a fair market value of $65,000 with respect to which A paid a gift tax in the amount of $7,545. The basis of the property in B's hands at the time of the gift, as determined under section 1015(a) and § 1.1015-1, would be the same as the adjusted basis in A's hands at the time of the gift, or $60,000. Under section 1015(d) and this section, the basis of the building in B's hands as of the date of the gift would be increased by the amount of the gift tax paid with respect to such gift, limited to an amount by which the fair market value of the property at the time of the gift exceeded the basis of the property in the hands of A at the time of gift, or $5,000. Therefore, the basis of the property in B's hands immediately after the gift, both for determining gain or loss on the sale of the property, would be $65,000.
C purchased property in 1938 at a cost of $100,000. On October 1, 1952, at which time the property had an adjusted basis of $72,000 in C's hands, he gave the property to his daughter, D. At the date of the gift to D, the property had a fair market value of $85,000 with respect to which C paid a gift tax in the amount of $11,745. On September 2, 1958, D still held the property which then had an adjusted basis in her hands of $65,000. Since the excess of the fair market value of the property at the time of the gift to D over the adjusted basis of the property in C's hands at such time is greater than the amount of gift tax paid, the basis of the property in D's hands would be increased as of September 2, 1958, by the amount of the gift tax paid, or $11,745. The adjusted basis of the property in D's hands, both for determining gain or loss on the sale of the property, would then be $76,745 ($65,000 plus $11,745).
On December 31, 1951, E gave to his son, F, 500 shares of common stock of the X Corporation which shares had been purchased earlier by E at a cost of $100 per share, or a total cost of $50,000. The basis in E's hands was still $50,000 on the date of the gift to F. On the date of the gift, the fair market value of the 500 shares was $80,000 with respect to which E paid a gift tax in the amount of $10,695. In 1956, the 500 shares of X Corporation stock were exchanged for 500 shares of common stock of the Y Corporation in a reorganization with respect to which no gain or loss was recognized for income tax purposes under section 354. F still held the 500 shares of Y Corporation stock on September 2, 1958. Under such circumstances, the 500 shares of X Corporation stock would not, for purposes of section 1015(d) and this section, be considered as having been sold, exchanged, or otherwise disposed of by F before September 2, 1958. Therefore, the basis of the 500 shares of Y Corporation stock held by F as of such date would, by reason of section 1015(d) and this section, be increased by $10,695, the amount of gift tax paid with respect to the gift to F of the X Corporation stock.
On November 15, 1953, G gave H property which had a fair market value of $53,000 and a basis in the hands of G of $20,000. G paid gift tax of $5,250 on the transfer. On November 16, 1956, H gave the property to J who still held it on September 2, 1958. The value of the property on the date of the gift to J was $63,000 and H paid gift tax of $7,125 on the transfer. Since the property was not sold, exchanged, or otherwise disposed of by J before September 2, 1958, and the gift tax paid on the transfer to J did not exceed $43,000 ($63,000, fair market value of property at time of gift to J, less $20,000, basis of property in H's hands at that time), the basis of property in his hands is increased on September 2, 1958, by $7,125, the amount of gift tax paid by H on the transfer. No increase in basis is allowed for the $5,250 gift tax paid by G on the transfer to H, since H had sold, exchanged, or otherwise disposed of the property before September 2, 1958.
[Amount of the gift (C) / Total taxable gifts, plus specific exemption allowed (D)] × Total gift tax paid (B)
For purposes of the ratio stated in the preceding sentence, the amount of the gift referred to as factor “C” is the value of the gift reduced by any portion excluded or deducted under section 2503(b) (annual exclusion), 2522 (charitable deduction), or 2523 (marital deduction) of the Code or the corresponding provisions of prior revenue laws. In making the computations described in this paragraph, the values to be used are those finally determined for purposes of the gift tax.
Prior to 1959 H made no taxable gifts. On July 1, 1959, he made a gift to his wife, W, of land having a value for gift purposes of $60,000 and gave to his son, S, certain securities valued at $60,000. During the year 1959, H also contributed $5,000 in cash to a charitable organization described in section 2522. H filed a timely gift tax return for 1959 with respect to which he paid gift tax in the amount of $6,000, computed as follows:
| Value of land given to W | $60,000 | ||
| Less: Annual exclusion | $3,000 | ||
| Marital deduction | 30,000 | 33,000 | |
| Included amount of gift | $27,000 | ||
| Value of securities given to S | 60,000 | ||
| Less: Annual exclusion | 3,000 | ||
| Included amount of gift | 57,000 | ||
| Gift to charitable organization | 5,000 | ||
| Less: Annual exclusion | 3,000 | ||
| Charitable deduction | 2,000 | 5,000 | |
| Included amount of gift | 0 | ||
| Total included gifts | 84,000 | ||
| Less: Specific exemption allowed | 30,000 | ||
| Taxable gifts for 1959 | 54,000 | ||
| Gift tax on $54,000 | 6,000 |
In determining the gift tax paid with respect to the land given to W, amount C of the ratio set forth in subparagraph (1)(ii) of this paragraph is $60,000, value of property given to W, less $33,000 (the sum of $3,000, the amount excluded under section 2503(b), and $30,000, the amount deducted under section 2523), or $27,000. Amount D of the ratio is $84,000 (the amount of taxable gifts, $54,000, plus the gift tax specific exemption, $30,000). The gift tax paid with respect to the land given to W is $1,928.57, computed as follows:
$27,000(C) ÷ $84,000(D) × $6,000(B)
The facts are the same as in example (1) except that H made his gifts to W and S on July 1, 1971, and that prior to 1971, H made no taxable gifts. Furthermore, H made his charitable contribution on August 12, 1971. These were the only gifts made by H during 1971. H filed his gift tax return for the third quarter of 1971 on November 15, 1971, as required by section 6075(b). With respect to the above gifts H paid a gift tax in the amount of $6,000 on total taxable gifts of $54,000 for the third quarter of 1971. The gift tax paid with respect to the land given to W is $1,928.57. The computations for these figures are identical to those used in example (1).
On January 15, 1956, A made a gift to his nephew, N, of land valued at $86,000, and on June 30, 1956, gave N securities valued at $40,000. On July 1, 1956, A gave to his sister, S, $46,000 in cash. A and his wife, B, were married during the entire calendar year 1956. The amount of A's taxable gifts for prior years was zero although in arriving at that amount A had used in full the specific exemption authorized by section 2521. B did not make any gifts before 1956. A and B elected under section 2513 to have all gifts made by either during 1956 treated as made one-half by A and one-half by B. Pursuant to that election, A and B each filed a gift tax return for 1956. A paid gift tax of $11,325 and B paid gift tax of $5,250, computed as follows:
| A | B | |
|---|---|---|
| Value of land given to N | $43,000 | $43,000 |
| Less: exclusion | 3,000 | 3,000 |
| Included amount of gift | 40,000 | 40,000 |
| Value of securities given to N | 20,000 | 20,000 |
| Less: exclusion | None | None |
| Included amount of gift | 20,000 | 20,000 |
| Cash gift to S | 23,000 | 23,000 |
| Less: exclusion | 3,000 | 3,000 |
| Included amount of gift | 20,000 | 20,000 |
| Total included gifts | 80,000 | 80,000 |
| Less: specific exemption | None | 30,000 |
| Taxable gifts for 1956 | 80,000 | 50,000 |
| Gift tax for 1956 | 11,325 | 5,250 |
The amount of the gift tax paid by A with respect to the land given to N is computed as follows:
$40,000(C) / $80,000(D) × $11,325(B) = $5,662.50
The amount of the gift tax paid by B with respect to the land given to N is computed as follows:
$40,000(C) / $80,000(D) × $5,250(B) = $2,625
The amount of the gift tax paid with respect to the land is $5,662.50 plus $2,625, or $8,287.50. Computed in a similar manner, the amount of gift tax paid by A with respect to the securities given to N is $2,831.25, and the amount of gift tax paid by B with respect thereto is $1,312.50, or a total of $4,143.75.
The facts are the same as in example (3) except that A gave the land to N on January 15, 1972, the securities to N on February 3, 1972, and the cash to S on March 7, 1972. As in example (3), the amount of A's taxable gifts for taxable years prior to 1972 was zero, although in arriving at that amount A had used in full the specific exemption authorized by section 2521. B did not make any gifts before 1972. Pursuant to the election under section 2513, A and B treated all gifts made by either during 1972 as made one-half by A and one-half by B. A and B each filed a gift tax return for the first quarter of 1972 on May 15, 1972, as required by section 6075(b). A paid gift tax of $11,325 on taxable gifts of $80,000 and B paid gift tax of $5,250 on taxable gifts of $50,000. The amount of the gift tax paid by A and B with respect to the land given to N is $5,662.50 and $2,625, respectively. The computations for these figures are identical to those used in example (3).
(i) Prior to 1995, X exhausts X's gift tax unified credit available under section 2505. In 1995, X makes a gift to X's child Y, of a parcel of real estate having a fair market value of $100,000. X's adjusted basis in the real estate immediately before making the gift was $70,000. Also in 1995, X makes a gift to X's child Z, of a painting having a fair market value of $70,000. X timely files a gift tax return for 1995 and pays gift tax in the amount of $55,500, computed as follows:
| Value of real estate transferred to Y | $100,000 | |
| Less: Annual exclusion | 10,000 | |
| Included amount of gift (C) | $90,000 | |
| Value of painting transferred to Z | $70,000 | |
| Less: annual exclusion | 10,000 | |
| Included amount of gift | 60,000 | |
| Total included gifts (D) | $150,000 | |
| Total gift tax liability for 1995 gifts (B) | $55,500 |
(ii) The gift tax paid with respect to the real estate transferred to Y, is determined as follows:
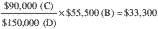
(iii)(A) The amount by which Y's basis in the real property is increased is determined as follows:
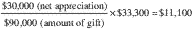
(B) Y's basis in the real property is $70,000 plus $11,100, or $81,100. If X had not exhausted any of X's unified credit, no gift tax would have been paid and, as a result, Y's basis would not be increased.
(i) X dies in 1995. X's spouse, Y, is not a United States citizen. In order to obtain the marital deduction for property passing to X's spouse, X established a QDOT in X's will. In 1996, the trustee of the QDOT makes a distribution of principal from the QDOT in the form of shares of stock having a fair market value of $70,000 on the date of distribution. The trustee's basis in the stock (determined under section 1014) is $50,000. An estate tax is imposed on the distribution under section 2056A(b)(1)(A) in the amount $38,500, and is paid. Y's basis in the shares of stock is increased by a portion of the section 2056A estate tax paid determined as follows:
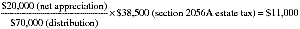
(ii) Y's basis in the stock is $50,000 plus $11,000, or $61,000.
[T.D. 6693, 28 FR 12818, Dec. 3, 1963, as amended by T.D. 7238, 37 FR 28715, Dec. 29, 1972; T.D. 7910, 48 FR 40372, Sept. 7, 1983; T.D. 8612, 60 FR 43537, Aug. 22, 1995]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 1015 Basis of property acquired by gifts and transfers in trust
- § 368 Definitions relating to corporate reorganizations
- § 354 Exchanges of stock and securities in certain reorganizations
- § 2521 Repealed
- § 2503 Taxable gifts
- § 2513 Gift by husband or wife to third party
- § 2523 Gift to spouse
- § 6075 Time for filing estate and gift tax returns
- § 2522 Charitable and similar gifts
- § 2505 Unified credit against gift tax
- § 2056A Qualified domestic trust
- § 1014 Basis of property acquired from a decedent
- § 1016 Adjustments to basis
Regulations it cites
- § 1.1015-1 Basis of property acquired by gift after December 31, 1920.
- § 25.2502-1 Rate of tax.
- § 1.1016-5 Miscellaneous adjustments to basis.
Cited by 2 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 8612 (60 FR 43537)
- Amended by T.D. 7910 (48 FR 40372)
- Amended by T.D. 7238 (37 FR 28715)
- Issued by T.D. 6693 (28 FR 12818)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Basis Rules of General Application
Nearby sections
- § 1.1015-1 Basis of property acquired by gift after December 31, 1920.
- § 1.1015-2 Transfer of property in trust after December 31, 1920.
- § 1.1015-3 Gift or transfer in trust before January 1, 1921.
- § 1.1015-4 Transfers in part a gift and in part a sale.
- § 1.1015-5 Increased basis for gift tax paid.
- § 1.1016-1 Adjustments to basis; scope of section.
- § 1.1016-2 Items properly chargeable to capital account.
- § 1.1016-3 Exhaustion, wear and tear, obsolescence, amortization, and depletion for periods since February 28, 1913.
- § 1.1016-4 Exhaustion, wear and tear, obsolescence, amortization, and depletion; periods during which income was not subject to tax.