
Treasury Regulations · 26 CFR
§ 1.1441-3. Determination of amounts to be withheld.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 1441
Cite as 26 CFR § 1.1441-3
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- November 26, 1960 by T.D. 6500
- Issued under
- 26 U.S.C. § 1441
- Length
- 5,177 words · about 23 min to read
- Cross-references
- cites 12 Code sections and 20 regulations; cited by 15
(i) Facts. Corporation X, a publicly traded corporation with both U.S. and foreign shareholders and a calendar year taxpayer, has an accumulated deficit in earnings and profits at the close of 2000. In 2001, Corporation X generates $1 million of current earnings and profits each month and makes an $18 million distribution, resulting in a $12 million dividend. Corporation X plans to make an additional $18 million distribution on October 1, 2002. Approximately one month before that date, Corporation X's management receives an internal report from its legal and accounting department concerning Corporation X's estimated current earnings and profits. The report states that Corporation X should generate only $5.1 million of current earnings and profits by the close of the third quarter due to costs relating to substantial organizational and product changes, but these changes will enable Corporation X to generate $1.3 million of earnings and profits monthly for the last quarter of the 2002 fiscal year. Thus, the total amount of current and earnings and profits for 2002 is estimated to be $9 million.
(ii) Analysis. Based on the facts in paragraph (i) of this Example, including the fact that earnings and profits estimate was made within a reasonable time before the distribution, Corporation X can rely on the estimate under paragraph (c)(2)(ii)(A) of this section. Therefore, Corporation X may treat $9 million of the $18 million of the October 1, 2002, distribution to foreign shareholders as a non-dividend distribution.
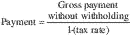
College X awards a qualified scholarship within the meaning of section 117(b) to foreign student, FS, who is in the United States on an F visa. FS is a resident of a country that does not have an income tax treaty with the United States. The scholarship is $20,000 to be applied to tuition, mandatory fees and books, plus benefits in kind consisting of room and board and roundtrip air transportation. College X agrees to pay any U.S. income tax owed by FS with respect to the scholarship. The fair market value of the room and board measured by the amount College X charges non-scholarship students is $6,000. The cost of the roundtrip air transportation is $2,600. Therefore, the total fair market value of the scholarship received by FS is $28,600. However, the amount taxable is limited to the fair market value of the benefits in kind ($8,600) because the portion of the scholarship amount for tuition, fees, and books is not included in gross income under section 117. The applicable rate of withholding is 14 percent under section 1441(b). Therefore, under the gross-up formula, College X is deemed to make a payment of $10,000 ($8,600 divided by (1-.14). The U.S. tax that must be deducted and withheld from the payment under section 1441(b) is $1,400 (.14 × $10,000). College X reports scholarship income of $30,000 and $1,400 of U.S. tax withheld on Forms 1042 and 1042-S.
[T.D. 6500, 25 FR 12074, Nov. 26, 1960]
For Federal Register citations affecting § 1.1441-3, see the List of CFR Sections Affected, which appears in the Finding Aids section of the printed volume and at www.govinfo.gov.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 1441 Withholding of tax on nonresident aliens
- § 871 Tax on nonresident alien individuals
- § 6045 Returns of brokers
- § 6042 Returns regarding payments of dividends and corporate earnings and profits
- § 852 Taxation of regulated investment companies and their shareholders
- § 897 Disposition of investment in United States real property
- § 856 Definition of real estate investment trust
- § 1445 Withholding of tax on dispositions of United States real property interests
- § 562 Rules applicable in determining dividends eligible for dividends paid deduction
- § 1442 Withholding of tax on foreign corporations
- § 301 Distributions of property
- § 117 Qualified scholarships
Regulations it cites
- § 1.1441-1 Requirement for the deduction and withholding of tax on payments to foreign persons.
- § 1.1441-4 Exemptions from withholding for certain effectively connected income and other amounts.
- § 1.1441-2 Amounts subject to withholding.
- § 1.1474-6 Coordination of chapter 4 with other withholding provisions.
- § 1.61-7 Interest.
- § 1.6045-1 Returns of information of brokers and barter exchanges.
- § 1.1461-1 Payment and returns of tax withheld.
- § 31.3406(b)(2)-4 Reportable dividend payment.
- § 1.1461-2 Adjustments for overwithholding or underwithholding of tax.
- § 1.1464-1 Refunds or credits.
- § 1.1445-5 Special rules concerning distributions and other transactions by corporations, partnerships, trusts, and estates.
- § 1.1445-1 Withholding on dispositions of U.S. real property interests by foreign persons: In general.
- § 1.1445-8 Special rules regarding publicly traded partnerships, publicly traded trusts and real estate investment trusts (REITs).
- § 1.1471-2 Requirement to deduct and withhold tax on withholdable payments to certain FFIs.
- § 31.3406(h)-2 Special rules.
- § 1.988-1 Certain definitions and special rules.
- § 1.6302-2 Deposit rules for tax withheld on nonresident aliens and foreign corporations.
- § 1.881-3 Conduit financing arrangements.
- § 1.1441-7 General provisions relating to withholding agents.
- § 1.871-15 Treatment of dividend equivalents.
Cited by 15 other regulations
- § 1.871-15 Treatment of dividend equivalents.
- § 1.874-1 Allowance of deductions and credits to nonresident alien individuals.
- § 1.881-3 Conduit financing arrangements.
- § 1.897(l)-1 Exception for interests held by foreign pension funds.
- § 1.1441-0 Outline of regulation provisions for section 1441.
- § 1.1441-1 Requirement for the deduction and withholding of tax on payments to foreign persons.
- § 1.1441-2 Amounts subject to withholding.
- § 1.1441-5 Withholding on payments to partnerships, trusts, and estates.
- § 1.1441-7 General provisions relating to withholding agents.
- § 1.1445-5 Special rules concerning distributions and other transactions by corporations, partnerships, trusts, and estates.
- § 1.1451-1 Tax-free covenant bonds issued before January 1, 1934.
- § 1.1461-1 Payment and returns of tax withheld.
- § 1.1462-1 Withheld tax as credit to recipient of income.
- § 1.1473-1 Section 1473 definitions.
- § 1.1474-6 Coordination of chapter 4 with other withholding provisions.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 6500 (25 FR 12074)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Withholding of Tax on Nonresident Aliens and Foreign Corporations and Tax-Free Covenant Bonds
Nearby sections
- § 1.1441-0 Outline of regulation provisions for section 1441.
- § 1.1441-1 Requirement for the deduction and withholding of tax on payments to foreign persons.
- § 1.1441-2 Amounts subject to withholding.
- § 1.1441-3 Determination of amounts to be withheld.
- § 1.1441-4 Exemptions from withholding for certain effectively connected income and other amounts.
- § 1.1441-5 Withholding on payments to partnerships, trusts, and estates.
- § 1.1441-6 Claim of reduced withholding under an income tax treaty.
- § 1.1441-7 General provisions relating to withholding agents.