
Treasury Regulations · 26 CFR
§ 1.163-10T. Qualified residence interest (temporary).
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 163
Cite as 26 CFR § 1.163-10T
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- December 22, 1987 by T.D. 8168
- Issued under
- 26 U.S.C. § 163
- Length
- 12,462 words · about 54 min to read
- Defines
- 7 terms
- Cross-references
- cites 23 Code sections and 2 regulations; cited by 2
(a) Table of contents.
(b) Treatment of qualified residence interest.
(c) Determination of qualified residence interest when secured debt does not exceed the adjusted purchase price.
(1) In general.
(2) Examples.
(d) Determination of qualified residence interest when secured debt exceeds adjusted purchase price—Simplified method.
(1) In general.
(2) Treatment of interest paid or accrued on secured debt that is not qualified residence interest.
(3) Example.
(e) Determination of qualified residence interest when secured debt exceeds adjusted purchase price—Exact method.
(1) In general.
(2) Determination of applicable debt limit.
(3) Example.
(4) Treatment of interest paid or accrued with respect to secured debt that is not qualified residence interest.
(i) In general.
(ii) Example.
(iii) Special rule of debt is allocated to more than one expenditure.
(iv) Example.
(f) Special rules.
(1) Special rules for personal property.
(i) In general.
(ii) Example.
(2) Special rule for real property.
(i) In general.
(ii) Example.
(g) Selection of method.
(h) Average balance.
(1) Average balance defined.
(2) Average balance reported by lender.
(3) Average balance computed on a daily basis.
(i) In general.
(ii) Example.
(4) Average balance computed using the interest rate.
(i) In general.
(ii) Points and prepaid interest.
(iii) Examples.
(5) Average balance computed using average of beginning and ending balance.
(i) In general.
(ii) Example.
(6) Highest principal balance.
(7) Other methods provided by the Commissioner.
(8) Anti-abuse rule.
(i) [Reserved]
(j) Determination of interest paid or accrued during the taxable year.
(1) In general.
(2) Special rules for cash-basis taxpayers.
(i) Points deductible in year paid under section 461(g)(2).
(ii) Points and other prepaid interest described in section 461(g)(1).
(3) Examples.
(k) Determination of adjusted purchase price and fair market value.
(1) Adjusted purchase price.
(i) In general.
(ii) Adjusted purchase price of a qualified residence acquired incident to divorce.
(iii) Examples.
(2) Fair market value.
(i) In general.
(ii) Examples.
(3) Allocation of adjusted purchase price and fair market value.
(l) [Reserved]
(m) Grandfathered amount.
(1) Substitution for adjusted purchase price.
(2) Determination of grandfathered amount.
(i) In general.
(ii) Special rule for lines of credit and certain other debt.
(iii) Fair market value limitation.
(iv) Examples.
(3) Refinancing of grandfathered debt.
(i) In general.
(ii) Determination of grandfathered amount.
(4) Limitation on terms of grandfathered debt.
(i) In general.
(ii) Special rule for nonamortizing debt.
(iii) Example.
(n) Qualified indebtedness (secured debt used for medical and educational purposes).
(1) In general.
(i) Treatment of qualified indebtedness.
(ii) Determination of amount of qualified indebtedness.
(iii) Determination of amount of qualified indebtedness for mixed-use debt.
(iv) Example.
(v) Prevention of double counting in year of refinancing.
(vi) Special rule for principal payments in excess of qualified expenses.
(2) Debt used to pay for qualified medical or educational expenses.
(i) In general.
(ii) Special rule for refinancing.
(iii) Other special rules.
(iv) Examples.
(3) Qualified medical expenses.
(4) Qualified educational expenses.
(o) Secured debt.
(1) In general.
(2) Special rule for debt in certain States.
(3) Time at which debt is treated as secured.
(4) Partially secured debt.
(i) In general.
(ii) Example.
(5) Election to treat debt as not secured by a qualified residence.
(i) In general.
(ii) Example.
(iii) Allocation of debt secured by two qualified residences.
(p) Definition of qualified residence.
(1) In general.
(2) Principal residence.
(3) Second residence.
(i) In general.
(ii) Definition of residence.
(iii) Use as a residence.
(iv) Election of second residence.
(4) Allocations between residence and other property.
(i) In general.
(ii) Special rule for rental of residence.
(iii) Examples.
(5) Residence under construction.
(i) In general.
(ii) Example.
(6) Special rule for the time-sharing arrangements.
(q) Special rules for tenant-stockholders in cooperative housing corporations.
(1) In general.
(2) Special rule where stock may not be used to secure debt.
(3) Treatment of interest expense of the cooperative described in section 216(a)(2).
(4) Special rule to prevent tax avoidance.
(5) Other definitions.
(r) Effective date.
T purchases a qualified residence in 1987 for $65,000. T pays $6,500 in cash and finances the remainder of the purchase with a mortgage of $58,500. In 1988, the average balance of the mortgage is $58,000. Because the average balance of the mortgage is less than the adjusted purchase price of the residence ($65,000), all of the interest paid or accrued during 1988 on the mortgage is qualified residence interest.
The facts are the same as in example (1), except that T incurs a second mortgage on January 1, 1988, with an initial principal balance of $2,000. The average balance of the second mortgage in 1988 is $1,900. Because the sum of the average balance of the first and second mortgages ($59,900) is less than the adjusted purchase price of the residence ($65,000), all of the interest paid or accrued during 1988 on both the first and second mortgages is qualified residence interest.
P borrows $50,000 on January 1, 1988 and secures the debt by a qualified residence. P pays the interest on the debt monthly, but makes no principal payments in 1988. There are no other debts secured by the residence during 1988. On December 31, 1988, the adjusted purchase price of the residence is $40,000. The average balance of the debt in 1988 is $50,000. Because the average balance of the debt exceeds the adjusted purchase price ($10,000), some of the interest on the debt is not qualified residence interest. The portion of the total interest that is qualified residence interest must be determined in accordance with the rules of paragraph (d) or paragraph (e) of this section.
R's principal residence has an adjusted purchase price on December 31, 1988, of $105,000. R has two debts secured by the residence, with the following average balances and interest payments:
| Debt | Date secured | Average balance | Interest |
|---|---|---|---|
| Debt 1 | June 1983 | $80,000 | $8,000 |
| Debt 2 | May 1987 | 40,000 | 4,800 |
| Total | 120,000 | 12,800 |
The amount of qualified residence interest is determined under the simplified method by multiplying the total interest ($12,800) by a fraction (expressed as a decimal amount) equal to the adjusted purchase price ($105,000) of the residence divided by the combined average balances ($120,000). For 1988, this fraction is equal to 0.875 ($105,000/$120,000). Therefore, $11,200 ($12,800 × 0.875) of the total interest is qualified residence interest. The remaining $1,600 in interest ($12,800 − $11,200) is personal interest, even if (under the rules of § 1.163-8T) such remaining interest would be allocated to some other category of interest.
For purposes of paragraph (e)(2)(ii) of this section, the average balance of a debt shall be treated as not exceeding the applicable debt limit of such debt. See paragraph (n)(1)(i) of this section for the rule that increases the adjusted purchase price in paragraph (e)(2)(i)(B) of this section by the amount of any qualified indebtedness (certain medical and educational debt). See paragraph (f) of this section for special rules relating to the determination of the fair market value of the qualified residence.
| Debt | Date secured | Fair market value | Average balance | Interest |
|---|---|---|---|---|
| Debt 1 | June 1983 | $100,000 | $80,000 | $8,000 |
| Debt 2 | May 1987 | 140,000 | 40,000 | 4,800 |
| Total | 120,000 | 12,800 |
the interest expense that is not qualified residence interest may be allocated among such expenditures, to the extent of such expenditures, in any manner selected by the taxpayer.
B has a line of credit secured by a qualified residence for the entire taxable year. The interest rate on the debt is 10 percent throughout the taxable year. The principal balance on the debt changes throughout the year. B pays the accrued interest on the debt monthly. B pays $2,500 in interest on the debt during the taxable year. The average balance of the debt ($25,000) may be computed by dividing the total interest paid by the interest rate ($25,000 = $2,500/0.10).
Assume the same facts as in example 1, except that the residence is a qualified residence, and the debt is outstanding, for only one-half of the taxable year and B pays only $1,250 in interest on the debt during the taxable year. The average balance of the debt may be computed by first dividing the total interest paid by the interest rate ($12,500 = $1,250/0.10). Second, because the residence is not a qualified residence for the entire taxable year, the average balance must be determined by dividing this amount ($12,500) by the portion of the year that the residence is qualified (0.50). The average balance is therefore $25,000 ($12,500/0.50).
the average balance of the debt may be determined by adding the principal balance as of the first day of the taxable year that the debt is secured by the qualified residence and the principal balance as of the last day of the taxable year that the debt is secured by the qualified residence and dividing the sum by 2. If the debt is secured by a qualified residence for less than the entire period during the taxable year that the residence is a qualified residence, the average balance may be determined by multiplying the average balance determined under the preceding sentence by a fraction, the numerator of which is the number of days during the taxable year that the debt is secured by the qualified residence and the denominator of which is the number of days during the taxable year that the residence is a qualified residence. For purposes of this paragraph (h)(5)(i), the determination of whether payments are level shall disregard the fact that the amount of the payments may be adjusted from time to time to take into account changes in the applicable interest rate.
Balance on first day of the year: $9,652
Balance on last day of the year: $9,450
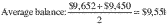
T designates a vacation home as a qualified residence as of October 1, 1987. The home is encumbered by a mortgage during the entire taxable year. For purposes of determining the amount of qualified residence interest for 1987, T may take into account the interest paid or accrued on the secured debt from October 1, 1987, through December 31, 1987.
R purchases a principal residence on June 17, 1987. As part of the purchase price, R obtains a conventional 30-year mortgage, secured by the residence. At closing, R pays 2 1/2 points on the mortgage and interest on the mortgage for the period June 17, 1987 through June 30, 1987. The points are actually paid by R and are not merely withheld from the loan proceeds. R incurs no additional secured debt during 1987. Assuming that the points satisfy the requirements of section 461(g) (2), the entire amount of points and the interest paid at closing are qualified residence interest.
(i) On July 1, 1987, W borrows $120,000 to purchase a residence to use as a vacation home. W secures the debt with the residence. W pays 2 points, or $2,400. The debt has a term of 10 years and requires monthly payments of principal and interest. W is permitted to amortize the points at the rate of $20 per month over 120 months. W elects to treat the residence as a second residence. W has no other debt secured by the residence. The average balance of the debt in each taxable year is less than the adjusted purchase price of the residence. W sells the residence on June 30, 1990, and pays off the remaining balance of the debt.
(ii) W is entitled to treat the following amounts of the points as interest paid on a debt secured by a qualified residence—
| 1987 | $120 = $20 × 6 months; |
| 1988 | $240 = $20 × 12 months; |
| 1989 | $120 = $20 × 6 months. |
| Total | $480 |
All of the interest paid on the debt, including the allocable points, is qualified residence interest. Upon repaying the debt, the remaining $1,920 ($2,400−$480) in unamortized points is treated as interest paid in 1990 and, because the average balance of the secured debt in 1990 is less than the adjusted purchase price, is also qualified residence interest.
X purchases a residence for $120,000. X's basis, as determined under section 1012, is the cost of the property, or $120,000. Accordingly, the adjusted purchase price of the residence is initially $120,000.
Y owns a principal residence that has a basis of $30,000. Y sells the residence for $100,000 and purchases a new principal residence for $120,000. Under section 1034, Y does not recognize gain on the sale of the former residence. Under section 1034(e), Y's basis in the new residence is reduced by the amount of gain not recognized. Therefore, under section 1034(e), Y's basis in the new residence is $50,000 ($120,000−$70,000). For purposes of section 163(h), however, the adjusted purchase price of the residence is not adjusted under section 1034(e). Therefore, the adjusted purchase price of the residence is initially $120,000.
For purposes of this paragraph (m)(2)(ii), a taxpayer shall not be considered to have borrowed any additional amount with respect to a debt merely because accrued interest is added to the principal balance of the debt, so long as such accrued interest is paid by the taxpayer no less often than quarterly.
As of August 16, 1986, T has one debt secured by T's principal residence. The debt is a conventional self-amortizing mortgage and, on August 16, 1986, it has an outstanding principal balance of $75,000. In 1987, the average balance of the mortgage is $73,000. The adjusted purchase price of the residence as of the end of 1987 is $50,000. Because the mortgage was incurred and secured on or before August 16, 1986 and T has not borrowed any additional amounts with respect to the mortgage, the grandfathered amount is the average balance, $73,000. Because the grandfathered amount exceeds the adjusted purchase price ($50,000), T may treat the grandfathered amount as the adjusted purchase price in determining the amount of qualified residence interest.
(i) The facts are the same as in example (1), except that in May 1986, T also obtains a home equity line of credit that, on August 16, 1986, has a principal balance of $40,000. In November 1986, T borrows an additional $10,000 on the home equity line, increasing the balance to $50,000. In December 1986, T repays $5,000 of principal on the home equity line. The average balance of the home equity line in 1987 is $45,000.
(ii) Because T has borrowed additional amounts on the line of credit after August 16, 1986, the grandfathered amount for that debt must be determined under the rules of paragraph (m)(2)(ii) of this section. Accordingly, the grandfathered amount for the line of credit is equal to the lesser of $45,000, the average balance of the debt in 1987, and $35,000, the principal balance on August 16, 1986, reduced by all principal payments between August 17, 1986, and December 31, 1986 ($40,000-$5,000). The sum of the grandfathered amounts with respect to the residence is $108,000 ($73,000 + $35,000). Because the sum of the grandfathered amounts exceeds the adjusted purchase price ($50,000), T may treat the sum as the adjusted purchase price in determining the qualified residence interest for 1987.
the grandfathered amount of the replacement debt is the average balance of the replacement debt. For purposes of the preceding sentence, the fact that proceeds of a replacement debt are used to pay costs of obtaining the replacement debt (including points or other closing costs) shall be disregarded in determining whether the entire proceeds of the replacement debt have been used to refinance one or more original debts.
| Average balance | $9,500 | |
| Amount of debt used to pay for qualified medical expenses | $4,000 | |
| Less payments of principal before 1988 | $0 | |
| Net qualified expenses | $4,000 |
The amount of qualified indebtedness for 1988 is, therefore, $4,000 (lesser of $9,500 average balance or $4,000 net qualified expenses). This amount may be added to the adjusted purchase price of C's principal residence under paragraph (e)(2)(i)(B) of this section for purposes of computing the applicable debt limit for this debt and any other debt subsequently secured by the principal residence.
| Average balance | $8,500 | |
| Amount of debt used to pay for qualified medical expenses | $4,000 | |
| Less payments of principal before 1988 | $1,000 | |
| Net qualified expenses | $3,000 |
The amount of qualified indebtedness for 1989 is, therefore, $3,000 (lesser of $8,500 average balance or $3,000 net qualified expenses).
A pays a $5,000 qualified educational expense from a checking account that A maintains at Bank 1 on November 9, 1987. On January 1, 1988, A incurs a $20,000 debt that is secured by A's residence and places the proceeds of the debt in a savings account that A also maintains at Bank 1. A pays another $5,000 qualified educations expense on March 15 from a checking account that A maintains at Bank 2. Under paragraph (n)(2) of this section, the debt proceeds are used to pay for both educational expenses, regardless of other deposits to, or expenditures from, the accounts, because both expenditures are made within 90 days before or after the debt was incurred.
B pays a $5,000 qualified educational expense from a checking account on November 1, 1987. On November 30, 1987, B incurs a debt secured by B's residence, and the lender disburses the debt proceeds directly to a person who sells B a new car. Although the educational expense is paid within 90 days of the date the debt is incurred, the proceeds of the debt are not used to pay for the educational expense because the proceeds are directly allocable to the purchase of the new car under § 1.163-8T(c)(3).
On November 1, 1987, C borrows $5,000 from C's college. The proceeds of this debt are not disbursed to C, but rather are used to pay tuition fees for C's attendance at the college. On November 30, 1987, C incurs a second debt and secures the debt by C's residence. Although the $5,000 educational expense is paid within 90 days before the second debt is incurred, the proceeds of the second debt are not used to pay for the educational expense, because the proceeds of the first debt are directly allocable to the educational expense under § 1.163-8T(c)(3).
On January 1, 1988, D incurs a $20,000 debt secured by a qualified residence. D places the proceeds of the debt in a separate account (i.e., the proceeds of the debt are the only deposit in the account). D makes payments of $5,000 each for qualified educational expenses on September 1, 1988, September 1, 1989, September 1, 1990, and September 1, 1991. Because the debt proceeds are allocated to educational expenses as of the date the expenses are paid, under the rules of § 1.163-8T(c)(4), the following amounts of the debt proceeds are used to pay for qualified educational expenses as of the end of each year:
1988: $5,000
1989: $10,000
1990: $15,000
1991: $20,000
During 1987 E incurs a $10,000 debt secured by a principal residence. E uses (within the meaning of paragraph (n)(2)(i) of this section) all of the proceeds of the debt to pay for qualified educational expenses. On August 20, 1988, at which time the balance of the debt is $9,500, E incurs a new debt in the amount of $9,500 secured by E's principal residence and uses all of the proceeds of the new debt to repay the original debt. Under paragraph (n)(2)(ii) of this section, all of the proceeds of the new debt are used to pay for qualified educational expenses.
A debt will not be considered to be secured by a qualified residence if it is secured solely by virtue of a lien upon the general assets of the taxpayer or by a security interest, such as a mechanic's lien or judgment lien, that attaches to the property without the consent of the debtor.
A taxpayer cannot have more than one second residence at any time.
D, a dentist, uses a room in D's principal residence as an office which qualifies under section 280A(c)(1)(B) as a portion of the dwelling unit used exclusively on a regular basis as a place of business for meeting with patients in the normal course of D's trade or business. D's adjusted purchase price of the property is $65,000; $10,000 of which is allocable under paragraph (o)(4)(i) of this section to the room used as an office. For purposes of this section, D's residence does not include the room used as an office. The adjusted purchase price of the residence is, accordingly, $55,000. Similarly, the fair market value of D's residence must be allocated between the office and the remainder of the property.
J rents out the basement of property that is otherwise used as J's principal residence. The basement is a self-contained residential unit, with sleeping space and toilet and cooking facilities. The adjusted purchase price of the property is $100,000; $15,000 of which is allocable under paragraph (o)(4)(i) of this section to the basement. For purposes of this section, J's residence does not include the basement and the adjusted purchase price of the residence is $85,000. Similarly, the fair market value of the residence must be allocated between the basement unit and the remainder of the property.
[T.D. 8168, 52 FR 48410, Dec. 22, 1987]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 461 General rule for taxable year of deduction
- § 216 Deduction of taxes, interest, and business depreciation by cooperative housing corporation tenant-stockholder
- § 163 Interest
- § 263A Capitalization and inclusion in inventory costs of certain expenses
- § 469 Passive activity losses and credits limited
- § 263 Capital expenditures
- § 264 Certain amounts paid in connection with insurance contracts
- § 265 Expenses and interest relating to tax-exempt income
- § 266 Carrying charges
- § 267 Losses, expenses, and interest with respect to transactions between related taxpayers
- § 465 Deductions limited to amount at risk
- § 1277 Deferral of interest deduction allocable to accrued market discount
- § 1282 Deferral of interest deduction allocable to accrued discount
- § 6050H Returns relating to mortgage interest received in trade or business from individuals
- § 1012 Basis of property—cost
- § 1016 Adjustments to basis
- § 1033 Involuntary conversions
- § 1034 Repealed
- § 1015 Basis of property acquired by gifts and transfers in trust
- § 213 Medical, dental, etc., expenses
- § 152 Dependent defined
- § 170 Charitable, etc., contributions and gifts
- § 280A Disallowance of certain expenses in connection with business use of home, rental of vacation homes, etc.
Regulations it cites
- § 1.163-8T Allocation of interest expense among expenditures (temporary).
- § 1.163-9T Personal interest (temporary).
Cited by 2 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 8168 (52 FR 48410)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Itemized Deductions for Individuals and Corporations
Nearby sections
- § 1.163-6T Reduction of deduction where section 25 credit taken (temporary).
- § 1.163-7 Deduction for OID on certain debt instruments.
- § 1.163-8T Allocation of interest expense among expenditures (temporary).
- § 1.163-9T Personal interest (temporary).
- § 1.163-10T Qualified residence interest (temporary).
- § 1.163-11 Allocation of certain prepaid qualified mortgage insurance premiums.
- § 1.163-12 Deduction of original issue discount on instrument held by related foreign person.
- § 1.163-13 Treatment of bond issuance premium.
- § 1.163-15 Debt proceeds distributed from any taxpayer account or from cash.