
Treasury Regulations · 26 CFR
§ 1.408-11. Net income calculation for returned or recharacterized IRA contributions.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 408
Cite as 26 CFR § 1.408-11
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- May 5, 2003 by T.D. 9056
- Issued under
- 26 U.S.C. § 408
- Length
- 933 words · about 4 min to read
- Defines
- 4 terms
- Cross-references
- cites 2 Code sections and 1 regulation; cited by 2
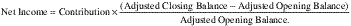
(i) On May 1, 2004, when her IRA is worth $4,800, Taxpayer A makes a $1,600 regular contribution to her IRA. Taxpayer A requests that $400 of the May 1, 2004, contribution be returned to her pursuant to section 408(d)(4). Pursuant to this request, on February 1, 2005, when the IRA is worth $7,600, the IRA trustee distributes to Taxpayer A the $400 plus attributable net income. During this time, no other contributions have been made to the IRA and no distributions have been made.
(ii) The adjusted opening balance is $6,400 [$4,800 + $1,600] and the adjusted closing balance is $7,600. Thus, the net income attributable to the $400 May 1, 2004, contribution is $75 [$400 × ($7,600−$6,400) ÷ $6,400]. Therefore, the total to be distributed on February 1, 2005, pursuant to § 408(d)(4) is $475.
(i) Beginning in January 2004, Taxpayer B contributes $300 on the 15th of each month to an IRA for 2004, resulting in an excess regular contribution of $600 for that year. Taxpayer B requests that the $600 excess regular contribution be returned to her pursuant to section 408(d)(4). Pursuant to this request, on March 1, 2005, when the IRA is worth $16,000, the IRA trustee distributes to Taxpayer B the $600 plus attributable net income. The excess regular contributions to be returned are deemed to be the last two made in 2004: the $300 December 15 contribution and the $300 November 15 contribution. On November 15 the IRA was worth $11,000 immediately prior to the contribution. No distributions or transfers have been made from the IRA and no contributions or transfers, other than the monthly contributions (including $300 in January and February 2005), have been made.
(ii) As of the beginning of the computation period (November 15), the adjusted opening balance is $12,200 [$11,000 + $300 + $300 + $300 + $300] and the adjusted closing balance is $16,000. Thus, the net income attributable to the excess regular contributions is $187 [$600 × ($16,000 − $12,200) ÷ $12,200]. Therefore, the total to be distributed as returned contributions on March 1, 2005, to correct the excess regular contribution is $787 [$600 + $187].
[T.D. 9056, 68 FR 23588, May 5, 2003]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
Regulations it cites
Cited by 2 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 9056 (68 FR 23588)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
Nearby sections
- § 1.408-5 Annual reports by trustees or issuers.
- § 1.408-6 Disclosure statements for individual retirement arrangements.
- § 1.408-7 Reports on distributions from individual retirement plans.
- § 1.408-8 Distribution requirements for individual retirement plans.
- § 1.408-11 Net income calculation for returned or recharacterized IRA contributions.
- § 1.408(q)-1 Deemed IRAs in qualified employer plans.
- § 1.408A-0 Roth IRAs; table of contents.
- § 1.408A-1 Roth IRAs in general.
- § 1.408A-2 Establishing Roth IRAs.