
Treasury Regulations · 26 CFR
§ 1.408A-5. Recharacterized contributions.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 408A
Cite as 26 CFR § 1.408A-5
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- February 4, 1999 by T.D. 8816
- Last amended
- May 5, 2003 by T.D. 9056
- Issued under
- 26 U.S.C. § 408A
- Length
- 3,597 words · about 16 min to read
- Defines
- 3 terms
- Cross-references
- cites 3 Code sections and 1 regulation; cited by 8
This section sets forth the following questions and answers that provide rules regarding recharacterizing IRA contributions:
Q-1. Can an IRA owner recharacterize certain contributions (i.e., treat a contribution made to one type of IRA as made to a different type of IRA) for a taxable year?
A-1. (a) Yes. In accordance with section 408A(d)(6), except as otherwise provided in this section, if an individual makes a contribution to an IRA (the FIRST IRA) for a taxable year and then transfers the contribution (or a portion of the contribution) in a trustee-to-trustee transfer from the trustee of the FIRST IRA to the trustee of another IRA (the SECOND IRA), the individual can elect to treat the contribution as having been made to the SECOND IRA, instead of to the FIRST IRA, for Federal tax purposes. A transfer between the FIRST IRA and the SECOND IRA will not fail to be a trustee-to-trustee transfer merely because both IRAs are maintained by the same trustee. For purposes of section 408A(d)(6), redesignating the FIRST IRA as the SECOND IRA will be treated as a transfer of the entire account balance from the FIRST IRA to the SECOND IRA.
Q-2. What is the proper treatment of the net income attributable to the amount of a contribution that is being recharacterized?
A-2. (a) The net income attributable to the amount of a contribution that is being recharacterized must be transferred to the SECOND IRA along with the contribution.
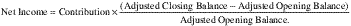
(i) On March 1, 2004, when her Roth IRA is worth $80,000, Taxpayer A makes a $160,000 conversion contribution to the Roth IRA. Subsequently, Taxpayer A discovers that she was ineligible to make a Roth conversion contribution in 2004 and so she requests that the $160,000 be recharacterized to a traditional IRA pursuant to section 408A(d)(6). Pursuant to this request, on March 1, 2005, when the IRA is worth $225,000, the Roth IRA trustee transfers to a traditional IRA the $160,000 plus allocable net income. No other contributions have been made to the Roth IRA and no distributions have been made.
(ii) The adjusted opening balance is $240,000 [$80,000 + $160,000] and the adjusted closing balance is $225,000. Thus the net income allocable to the $160,000 is − $10,000 [$160,000 × ($225,000 − $240,000) ÷ $240,000]. Therefore, in order to recharacterize the March 1, 2004, $160,000 conversion contribution on March 1, 2005, the Roth IRA trustee must transfer from Taxpayer A's Roth IRA to her traditional IRA $150,000 [$160,000 − $10,000].
(i) On April 1, 2004, when her traditional IRA is worth $100,000, Taxpayer B converts the entire amount, consisting of 100 shares of stock in ABC Corp. and 100 shares of stock in XYZ Corp., by transferring the shares to a Roth IRA. At the time of the conversion, the 100 shares of stock in ABC Corp. are worth $50,000 and the 100 shares of stock in XYZ Corp. are also worth $50,000. Taxpayer B decides that she would like to recharacterize the ABC Corp. shares back to a traditional IRA. However, B may choose only by dollar amount the contribution or portion thereof that is to be recharacterized. On the date of transfer, November 1, 2004, the 100 shares of stock in ABC Corp. are worth $40,000 and the 100 shares of stock in XYZ Corp. are worth $70,000. No other contributions have been made to the Roth IRA and no distributions have been made.
(ii) If B requests that $50,000 (which was the value of the ABC Corp. shares at the time of conversion) be recharacterized, the net income allocable to the $50,000 is $5,000 [$50,000 × ($110,000 − $100,000) ÷ $100,000]. Therefore, in order to recharacterize $50,000 of the April 1, 2004, conversion contribution on November 1, 2004, the Roth IRA trustee must transfer from Taxpayer B's Roth IRA to a traditional IRA assets with a value of $55,000 [$50,000 + $5,000].
(iii) If, on the other hand, B requests that $40,000 (which was the value of the ABC Corp. shares on November 1) be recharacterized, the net income allocable to the $40,000 is $4,000 [$40,000 × ($110,000 − $100,000) ÷ $100,000]. Therefore, in order to recharacterize $40,000 of the April 1, 2004, conversion contribution on November 1, 2004, the Roth IRA trustee must transfer from Taxpayer B's Roth IRA to a traditional IRA assets with a value of $44,000 [$40,000 + $4,000].
(iv) Regardless of the amount of the contribution recharacterized, the determination of that amount (or of the net income allocable thereto) is not affected by whether the recharacterization is accomplished by the transfer of shares of ABC Corp. or of shares of XYZ Corp.
Q-3. What is the effect of recharacterizing a contribution made to the FIRST IRA as a contribution made to the SECOND IRA?
A-3. The contribution that is being recharacterized as a contribution to the SECOND IRA is treated as having been originally contributed to the SECOND IRA on the same date and (in the case of a regular contribution) for the same taxable year that the contribution was made to the FIRST IRA. Thus, for example, no deduction would be allowed for a contribution to the FIRST IRA, and any net income transferred with the recharacterized contribution is treated as earned in the SECOND IRA, and not the FIRST IRA.
Q-4. Can an amount contributed to an IRA in a tax-free transfer be recharacterized under A-1 of this section?
A-4. No. If an amount is contributed to the FIRST IRA in a tax-free transfer, the amount cannot be recharacterized as a contribution to the SECOND IRA under A-1 of this section. However, if an amount is erroneously rolled over or transferred from a traditional IRA to a SIMPLE IRA, the contribution can subsequently be recharacterized as a contribution to another traditional IRA.
Q-5. Can an amount contributed by an employer under a SIMPLE IRA Plan or a SEP be recharacterized under A-1 of this section?
A-5. No. Employer contributions (including elective deferrals) under a SIMPLE IRA Plan or a SEP cannot be recharacterized as contributions to another IRA under A-1 of this section. However, an amount converted from a SEP IRA or SIMPLE IRA to a Roth IRA may be recharacterized under A-1 of this section as a contribution to a SEP IRA or SIMPLE IRA, including the original SEP IRA or SIMPLE IRA.
Q-6. How does a taxpayer make the election to recharacterize a contribution to an IRA for a taxable year?
A-6. (a) An individual makes the election described in this section by notifying, on or before the date of the transfer, both the trustee of the FIRST IRA and the trustee of the SECOND IRA, that the individual has elected to treat the contribution as having been made to the SECOND IRA, instead of the FIRST IRA, for Federal tax purposes. The notification of the election must include the following information: the type and amount of the contribution to the FIRST IRA that is to be recharacterized; the date on which the contribution was made to the FIRST IRA and the year for which it was made; a direction to the trustee of the FIRST IRA to transfer, in a trustee-to-trustee transfer, the amount of the contribution and net income allocable to the contribution to the trustee of the SECOND IRA; and the name of the trustee of the FIRST IRA and the trustee of the SECOND IRA and any additional information needed to make the transfer.
Q-7. If an amount is initially contributed to an IRA for a taxable year, then is moved (with net income attributable to the contribution) in a tax-free transfer to another IRA (the FIRST IRA for purposes of A-1 of this section), can the tax-free transfer be disregarded, so that the initial contribution that is transferred from the FIRST IRA to the SECOND IRA is treated as a recharacterization of that initial contribution?
A-7. Yes. In applying section 408A(d)(6), tax-free transfers between IRAs are disregarded. Thus, if a contribution to an IRA for a year is followed by one or more tax-free transfers between IRAs prior to the recharacterization, then for purposes of section 408A(d)(6), the contribution is treated as if it remained in the initial IRA. Consequently, an individual may elect to recharacterize an initial contribution made to the initial IRA that was involved in a series of tax-free transfers by making a trustee-to-trustee transfer from the last IRA in the series to the SECOND IRA. In this case the contribution to the SECOND IRA is treated as made on the same date (and for the same taxable year) as the date the contribution being recharacterized was made to the initial IRA.
Q-8. If a contribution is recharacterized, is the recharacterization treated as a rollover for purposes of the one-rollover-per-year limitation of section 408(d)(3)(B)?
A-8. No, recharacterizing a contribution under A-1 of this section is never treated as a rollover for purposes of the one-rollover-per-year limitation of section 408(d)(3)(B), even if the contribution would have been treated as a rollover contribution by the SECOND IRA if it had been made directly to the SECOND IRA, rather than as a result of a recharacterization of a contribution to the FIRST IRA.
Q-9. If an IRA owner converts an amount from a traditional IRA to a Roth IRA and then transfers that amount back to a traditional IRA in a recharacterization, may the IRA owner subsequently reconvert that amount from the traditional IRA to a Roth IRA?
A-9. (a)(1) Except as otherwise provided in paragraph (b) of this A-9, an IRA owner who converts an amount from a traditional IRA to a Roth IRA during any taxable year and then transfers that amount back to a traditional IRA by means of a recharacterization may not reconvert that amount from the traditional IRA to a Roth IRA before the beginning of the taxable year following the taxable year in which the amount was converted to a Roth IRA or, if later, the end of the 30-day period beginning on the day on which the IRA owner transfers the amount from the Roth IRA back to a traditional IRA by means of a recharacterization (regardless of whether the recharacterization occurs during the taxable year in which the amount was converted to a Roth IRA or the following taxable year). Thus, any attempted reconversion of an amount prior to the time permitted under this paragraph (a)(1) is a failed conversion of that amount. However, see § 1.408A-4 A-3 for a remedy available to an individual who makes a failed conversion.
Q-10. Are there examples to illustrate the rules in this section?
A-10. The rules in this section are illustrated by the following examples:
In 1998, Individual C converts the entire amount in his traditional IRA to a Roth IRA. Individual C thereafter determines that his modified AGI for 1998 exceeded $100,000 so that he was ineligible to have made a conversion in that year. Accordingly, prior to the due date (plus extensions) for filing the individual's Federal income tax return for 1998, he decides to recharacterize the conversion contribution. He instructs the trustee of the Roth IRA (FIRST IRA) to transfer in a trustee-to-trustee transfer the amount of the contribution, plus net income, to the trustee of a new traditional IRA (SECOND IRA). The individual notifies the trustee of the FIRST IRA and the trustee of the SECOND IRA that he is recharacterizing his IRA contribution (and provides the other information described in A-6 of this section). On the individual's Federal income tax return for 1998, he treats the original amount of the conversion as having been contributed to the SECOND IRA and not the Roth IRA. As a result, for Federal tax purposes, the contribution is treated as having been made to the SECOND IRA and not to the Roth IRA. The result would be the same if the conversion amount had been transferred in a tax-free transfer to another Roth IRA prior to the recharacterization.
In 1998, an individual makes a $2,000 regular contribution for 1998 to his traditional IRA (FIRST IRA). Prior to the due date (plus extensions) for filing the individual's Federal income tax return for 1998, he decides that he would prefer to contribute to a Roth IRA instead. The individual instructs the trustee of the FIRST IRA to transfer in a trustee-to-trustee transfer the amount of the contribution, plus attributable net income, to the trustee of a Roth IRA (SECOND IRA). The individual notifies the trustee of the FIRST IRA and the trustee of the SECOND IRA that he is recharacterizing his $2,000 contribution for 1998 (and provides the other information described in A-6 of this section). On the individual's Federal income tax return for 1998, he treats the $2,000 as having been contributed to the Roth IRA for 1998 and not to the traditional IRA. As a result, for Federal tax purposes, the contribution is treated as having been made to the Roth IRA for 1998 and not to the traditional IRA. The result would be the same if the conversion amount had been transferred in a tax-free transfer to another traditional IRA prior to the recharacterization.
The facts are the same as in Example 2, except that the $2,000 regular contribution is initially made to a Roth IRA and the recharacterizing transfer is made to a traditional IRA. On the individual's Federal income tax return for 1998, he treats the $2,000 as having been contributed to the traditional IRA for 1998 and not the Roth IRA. As a result, for Federal tax purposes, the contribution is treated as having been made to the traditional IRA for 1998 and not the Roth IRA. The result would be the same if the contribution had been transferred in a tax-free transfer to another Roth IRA prior to the recharacterization, except that the only Roth IRA trustee the individual must notify is the one actually making the recharacterization transfer.
In 1998, an individual receives a distribution from traditional IRA 1 and contributes the entire amount to traditional IRA 2 in a rollover contribution described in section 408(d)(3). In this case, the individual cannot elect to recharacterize the contribution by transferring the contribution amount, plus net income, to a Roth IRA, because an amount contributed to an IRA in a tax-free transfer cannot be recharacterized. However, the individual may convert (other than by recharacterization) the amount in traditional IRA 2 to a Roth IRA at any time, provided the requirements of § 1.408A-4 A-1 are satisfied.
[T.D. 8816, 64 FR 5605, Feb. 4, 1999, as amended by T.D. 9056, 68 FR 23589, May 5, 2003]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 408A Roth IRAs
- § 408 Individual retirement accounts
- § 6012 Persons required to make returns of income
Regulations it cites
Cited by 8 other regulations
- § 1.408-11 Net income calculation for returned or recharacterized IRA contributions.
- § 1.408A-0 Roth IRAs; table of contents.
- § 1.408A-2 Establishing Roth IRAs.
- § 1.408A-3 Contributions to Roth IRAs.
- § 1.408A-4 Converting amounts to Roth IRAs.
- § 1.408A-6 Distributions.
- § 1.408A-7 Reporting.
- § 1.408A-8 Definitions.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9056 (68 FR 23589)
- Issued by T.D. 8816 (64 FR 5605)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes