
Treasury Regulations · 26 CFR
§ 1.613-4. Gross income from the property in the case of minerals other than oil and gas.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 613
Cite as 26 CFR § 1.613-4
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- March 15, 1972 by T.D. 7170
- Issued under
- 26 U.S.C. § 613
- Length
- 11,158 words · about 49 min to read
- Defines
- 21 terms
- Cross-references
- cites 3 Code sections and 5 regulations; cited by 6
If the taxpayer sells his ore or mineral in more than one form, and if only mining processes are applied to the ore or mineral, gross income from mining is the actual amount for which the various forms of the ore or mineral are sold, after any adjustments required by paragraph (e)(1) of this section. For example, if, at his mine or quarry, a taxpayer sells several sizes of crushed gypsum and also sells gypsum fines produced as an incidental byproduct of his crushing operations, without applying any nonmining processes, gross income from mining will ordinarily be the total amount for which such crushed gypsum and fines are actually sold. See paragraphs (f) and (g) of this section for provisions defining mining and nonmining processes for various minerals.
Fine distinctions between various grades of minerals are to be avoided unless those distinctions are clearly shown to have genuine commercial significance.
(b) The proportionate profits method is more appropriate than the method being used under (a) if, under the particular facts and circumstances, the method being used under (a) consistently fails to clearly reflect gross income from mining and the proportionate profits method more clearly reflects gross income from mining for the taxable year.
(c) An alternative method (a method other than the method being used under (a) (if any) and the proportionate profits method) is more appropriate than the method being used under (a) (if any) and the proportionate profits method if, under the particular facts and circumstances, the latter methods consistently fail to clearly reflect gross income from mining, and the alternative method being considered more clearly reflects gross income from mining on a consistent basis than the method being used under (a) (if any) and the proportionate profits method. When determining whether a method of computation clearly reflects gross income from mining, it is relevant to compare the gross income from mining produced by such method with the gross income from mining, on an equivalent amount of production, which results from the computation methods used by competitors. When determining the acceptability of proposed alternative methods, primary consideration will be given to computation methods based upon representative charges for ores, minerals, products, or services. See paragraph (c) of this section for principles determining the representative character of a charge.
(d) Application for permission to compute gross income from mining by use of an alternative method shall be made by submitting a request to the Commissioner of Internal Revenue, Attention: Assistant Commissioner (Technical), Washington, DC 20224.
(e) Among the alternative methods of computation to which consideration will be given, provided that the requirements of this subdivision (ii) are met, are the methods listed in subparagraphs (5), (6), and (7) of this paragraph. The order in which these methods are listed is not significant, and the listing of these methods does not preclude a request to make use of a method which is not listed.
(a) The costs attributable to containers, bags, packages, pallets, and similar items as well as the costs of materials and labor attributable to bagging, packaging, palletizing, or similar operations shall be considered as nonmining costs.
(b) The costs attributable to the bulk loading of manufactured products shall be considered as nonmining costs.
(c) The costs attributable to the operation of warehouses or distribution terminals for manufactured products shall be considered as nonmining costs
Accordingly, all profits attributable thereto are treated as nonmining profits.
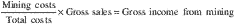
(b) In the case of sales between members of a controlled group as to which the district director has exercised his authority under section 482 and the regulations thereunder and has determined the appropriate price with respect to specific sales transactions, that price shall be deemed, for those transactions, to be the actual amount for which the first marketable product or group of products is sold for purposes of this subdivision (v). In the case of all other sales between members of a controlled group, and in the case of constructive sales, the prices for such sales shall be determined by use of the principles set forth in paragraph (c) of this section, subject to the adjustments required by paragraph (e) of this section. In the case of constructive sales, see paragraph (c)(4) of this section for rules relating to information to be furnished by the taxpayer.
(a) Facts. A is engaged in the mining of a mineral to which section 613 applies and in the application thereto of nonmining processes. During 1968, A incurred extraction costs of $35,000; other mining costs of $56,000; $150,000 for manufacturing costs; $46,000 for other nonmining processes; and $14,000 for the company president's salary and similiar costs resulting from both nonmining and mining processes. During that year, A produced and sold 70,000 tons of his first marketable product for an actual gross sales price of $420,000, after the adjustments required by paragraph (e) of this section. A representative market or field price for A's mineral before the application of nonmining processes cannot be established.
(b) Computation. (1) The computation of A's gross income from mining by use of the proportionate profits method involves two steps. The first step is to apportion A's costs to mining and to nonmining. A apportions the company president's salary and similiar costs to mining and to nonmining in the manner described in the second and third sentences of subdivision (iii) of this subparagraph, and apportions his remaining costs as follows:
| Cost | Mining | Nonmining | Total |
|---|---|---|---|
| Extraction | $35,000 | $35,000 | |
| Other mining processes | 56,000 | 56,000 | |
| Manufacturing | $150,000 | 150,000 | |
| Other nonmining processes | 46,000 | 46,000 | |
| Subtotal | 91,000 | 196,000 | 287,000 |
| President's salary and similar costs | 4,439 | 9,561 | 14,000 |
| Total costs | 95,439 | 205,561 | 301,000 |
(2) The second step is to apply the proportionate profits fraction so as to compute A's gross income from mining. To do this, A first computes his gross sales of his first marketable group of products, in this case $420,000. A multiplies his actual gross sales of $420,000 by the proportionate profits fraction, whose numerator consists of his total mining costs ($95,439) and whose denominator consists of his total costs ($301,000). Thus, A's gross income from mining is $133,170 (i.e., 95,439/301,000ths of A's actual gross sales of $420,000).
B, who leases a mineral property from C, is engaged in the mining of a mineral to which section 613 applies and in the application thereto of nonmining processes. Pursuant to the terms of the lease, B is required to pay C 10 cents for each ton of mineral which B mines. During 1971, B extracted 100,000 tons of mineral. He sold his first marketable product for an actual gross sales price of $225,000 after the adjustments required by paragraph (e) of this section. A representative market or field price for B's mineral before the application of nonmining processes cannot be established. During 1971, with respect to the 100,000 tons of mineral extracted, B incurred mining costs of $50,000 and nonmining costs of $100,000, and paid $10,000 to C as C's royalty. Since the royalty payment is considered to be C's share of the gross income from mining under section 613(a), it is not considered to be either a mining cost or a nonmining cost of B. B's gross income from mining is $65,000 under the proportionate profits method, determined as follows: The $225,000 gross receipts must be multiplied by the proportionate profits fraction which is $50,000 mining costs over $150,000 total costs ($50,000 + $100,000 nonmining costs). Since the resulting $75,000 is the total gross income from mining with respect to the property, it must be allocated between B's lease interest and C's royalty interest. The $10,000 paid to C must be subtracted from the $75,000 leaving $65,000 which represents B's gross income from mining. C's gross income from mining is the royalty he received or $10,000.
(a) Which is not performed in conveyances owned or leased directly or indirectly, in whole or in part, by the taxpayer,
(b) Which is performed solely to deliver the taxpayer's minerals or mineral products to the customer, rather than to transport such minerals or products for packaging or other additional processing by the taxpayer (other than incidental storage or handling), and
(c) With respect to which the taxpayer ordinarily does not earn any profit
For purposes of the preceding sentence, transportation which is performed by a person controlling or controlled by the taxpayer (within the meaning of paragraph (j)(1) of this section) shall be deemed to have been performed in conveyances owned or leased by the taxpayer unless it is established by the taxpayer that the price charged by the controlling or controlled person for such transportation constitutes an arm's-length charge (under the standard described in paragraph (b)(1) of § 1.482-1). The term purchased transportation to the customer includes transportation to a warehouse, terminal, or distribution facility owned or operated by the taxpayer, provided that such transportation is performed under the conditions described in the first sentence of this subdivision. A taxpayer will not be deemed ordinarily to earn a profit on transportation merely because charges for the transportation are included in the stated selling price, rather than being separately stated or segregated from other billing. A taxpayer will not be deemed ordinarily to earn a profit on transportation if the rates for the transportation constitute an arm's-length charge ordinarily paid by shippers of the same product in similar circumstances. If a taxpayer computes gross income from mining under the provisions of paragraph (d) of this section, the term purchased transportation to the customer refers to transportation which conforms to the other requirements of this subdivision and which is performed to transport the taxpayer's first marketable product or group of products (as defined in paragraph (d)(4)(iv) of this section) rather than to transport minerals or mineral products which do not yet constitute the taxpayer's first marketable product or group of products.
A is engaged in the mining of an ore of mineral M and in the production and sale of M concentrate. A retains a portion of his concentrate for use in his own nonmining operations. During 1968, A sold 100,000 tons of M concentrate of ore mined and processed by him, which sales constituted a significant portion of his total production. Eighty thousand tons of that concentrate were sold by A on the basis of a representative price (after adjustments required by subparagraph (1) of this paragraph) of $30 per ton f.o.b. mine or plant, resulting in gross income from mining of $2,400,000. The remaining 20,000 tons were sold by A, both directly and through terminals, on the basis of a delivered price (after adjustments required by subparagraph (1) of this paragraph) at City X of $40 per ton. The delivered price included $15 per ton cost of purchased transportation from the mine or plant to customers in City X. The representative market or field price of the concentrate sold by A on the basis of a delivered price is $25 per ton, determined by subtracting the cost of the purchased transportation to the customer ($15 per ton) from the delivered price for the concentrate ($40 per ton). Accordingly, A's gross income from mining with respect to the 20,000 tons of M concentrate sold on a delivered basis is $500,000. The representative market or field price for the concentrate retained by A and used in his own nonmining operations may be computed by reference to the weighted average price for both A's f.o.b. mine and A's delivered sales of concentrate, with the delivered sales prices reduced in the manner described above. On this basis, the representative market or field price for the retained concentrate is $29 per ton.
B is engaged in the mining of an ore of mineral N and in the production of N concentrate. B retained all but an insignificant amount of his concentrate for use in his own nonmining operations. Other producers in B's marketing area sell significant amounts of N concentrate of like kind and grade, both on an f.o.b. mine or plant basis and on a delivered basis. In this case, the prices for both the f.o.b. and the delivered sales made by other producers (after any adjustments required by subparagraph (1) of this paragraph), after reduction of the delivered prices by the cost of purchased transportation to the customer, shall, if such prices are otherwise representative, be taken into account in establishing the representative market or field price for the N concentrate produced and used by B.
(a) In the case of coal—cleaning, breaking, sizing, dust allaying, treating to prevent freezing, and loading for shipment;
(b) In the case of sulfur recovered by the Frasch process—cleaning, pumping to vats, cooling, breaking, and loading for shipment;
(c) In the case of iron ore, bauxite, ball and sagger clay, rock asphalt, and ores or minerals which are customarily sold in the form of a crude mineral product (as defined in subparagraph (3)(iv) of this paragraph):
(d) In the case of lead, zinc, copper, gold, silver, uranium, or fluorspar ores, potash, and ores or minerals which are not customarily sold in the form of the crude mineral product—crushing, grinding, and beneficiation by concentration (gravity, flotation, amalgamation, electrostatic, or magnetic), cyanidation, leaching, crystallization, precipitation (but not including electrolytic deposition, roasting, thermal or electric smelting, or refining), or by substantially equivalent processes or combination of processes used in the separation or extraction of the product or products from the ore or the mineral or minerals from other material from the mine or other natural deposit; and
(e) In the case of the following ores or minerals:
(a) For taxable years beginning after December 31, 1960, in the case of calcium carbonates and other minerals when used in making cement—all processes (other than preheating the kiln feed) applied prior to the introduction of the kiln feed into the kiln, but not including any subsequent process;
(b) For taxable years beginning after December 31, 1960, and before November 14, 1966, in the case of clay to which former section 613(b)(5)(B) applied, and for taxable years beginning after November 13, 1966, in the case of clay to which section 613(b) (5) or (6) (B) applies—crushing, grinding, and separating the clay from waste, but not including any subsequent process;
(c) For taxable years beginning after October 9, 1969, in the case of minerals (other than sodium chloride) extracted from brines pumped from a saline perennial lake (as defined in paragraph (b) of § 1.613-2)—the extraction of such minerals from the brines, but in no case including any further processing or refining of such extracted minerals; and
(d) For taxable years beginning after December 30, 1969, in the case of oil shale (as defined in paragraph (b) of § 1.613-2)—extraction from the ground, crushing, loading into the retort, and retorting, but in no case hydrogenation, refining, or any other process subsequent to retorting.
[T.D. 7170, 37 FR 5374, Mar. 15, 1972]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
- blending with other materials § 1.613-4(g)(6)(vi)
- calcining § 1.613-4(g)(6)(i)
- concentrating § 1.613-4(f)(3)(i)
- concentration § 1.613-4(f)(4)
- controlled § 1.613-4(j)(1)
- fine pulverization § 1.613-4(g)(6)(v)
- first marketable product or group of products § 1.613-4(d)(4)(iv)
- group § 1.613-4(j)(2)
- mining § 1.613-4(f)(1)
- mining § 1.613-4(f)(2)(iv)
- mining processes § 1.613-4(f)(2)(i)
- polishing § 1.613-4(g)(6)(iv)
- purchased transportation to the customer § 1.613-4(e)(2)(iii)
- purchased transportation to the customer § 1.613-4(e)(2)(iii)
- purchased transportation to the customer § 1.613-4(e)(2)(iii)
- refining § 1.613-4(g)(6)(iii)
- sintering § 1.613-4(f)(3)(ii)
- sorting § 1.613-4(f)(3)(i)
- thermal action § 1.613-4(g)(6)(viii)
- thermal smelting § 1.613-4(g)(6)(ii)
- treatment effecting a chemical change § 1.613-4(g)(6)(vii)
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 613 Percentage depletion
- § 482 Allocation of income and deductions among taxpayers
- § 381 Carryovers in certain corporate acquisitions
Regulations it cites
- § 1.613-3 Gross income from the property.
- § 1.446-1 General rule for methods of accounting.
- § 1.613-5 Taxable income from the property.
- § 1.482-1 Allocation of income and deductions among taxpayers.
- § 1.613-2 Percentage depletion rates.
Cited by 6 other regulations
- § 1.381(c)(18)-1 Depletion on extraction of ores or minerals from the waste or residue of prior mining.
- § 1.613-2 Percentage depletion rates.
- § 1.613-5 Taxable income from the property.
- § 1.993-3 Definition of export property.
- § 1.7704-4 Qualifying income—mineral and natural resources.
- § 601.201 Rulings and determinations letters.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 7170 (37 FR 5374)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Natural Resources
Nearby sections
- § 1.612-5 Charges to capital and to expense in case of geothermal wells.
- § 1.613-1 Percentage depletion; general rule.
- § 1.613-2 Percentage depletion rates.
- § 1.613-3 Gross income from the property.
- § 1.613-4 Gross income from the property in the case of minerals other than oil and gas.
- § 1.613-5 Taxable income from the property.
- § 1.613-6 Statement to be attached to return when depletion is claimed on percentage basis.
- § 1.613-7 Application of percentage depletion rates provided in section 613(b) to certain taxable years ending in 1954.
- § 1.613A-0 Limitations on percentage depletion in the case of oil and gas wells; table of contents.