
Treasury Regulations · 26 CFR
§ 1.613A-3. Exemption for independent producers and royalty owners.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 613A
Cite as 26 CFR § 1.613A-3
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- May 13, 1991 by T.D. 8348
- Last amended
- February 1, 1993
- Issued under
- 26 U.S.C. § 613A
- Length
- 13,048 words · about 57 min to read
- Defines
- 1 term
- Cross-references
- cites 16 Code sections and 8 regulations; cited by 7
A, a calendar year taxpayer, owns an oil producing property with 100,000 barrels of production to which income was attributable for 1975 and a gas producing property with 1,200,000,000 cubic feet of production to which income was attributable for 1975. Under section 613A(c)(4), the oil equivalent of 1,200,000,000 cubic feet of gas is 200,000 barrels, bringing A's total production of oil and gas to which income was attributable for 1975 to the equivalent of 300,000 barrels of oil. A's average daily production was 821.92 barrels (300,000 barrels ÷ 365 days) which is less than the depletable oil quantity (2,000 barrels) before reduuction for any election by A under section 613A(c)(4). Accordingly, A may make an election with respect to A's entire gas production and thereby be entitled to percentage depletion with respect to A's entire 1975 income from production of oil and gas. A's allowable depletion pursuant to section 613A(c) and A's oil and gas properties would be the amount determined under section 613(a) computed at the 22 percent rate specified in section 613A(c)(5), as in effect prior to the Revenue Reconciliation Act 1990, for 1975.
B, a calendar year taxpayer, owns oil producing properties with 365,000 barrels of production to which income was attributable for 1975. B was a retailer of oil and gas for only the last 3 months of 1975. B's average daily production for 1975 was 1,000 barrels (365,000 barrels ÷ 365 days).
C, a calendar year taxpayer, owns property X with 500,000 barrels of primary production to which income was attributable for 1975 and property Y with 200,000 barrels of primary production to which income was attributable for 1975. Property Y had been transferred to C on January 1, 1975, on which date it was a proven property. Therefore, the exemption under section 613A(c)(1) does not apply to C with respect to production from property Y. In determining C's depletable oil quantity for the year, the production from property Y is not taken into account. Thus, C's average daily prduction for 1975 was 1,369.86 barrels (500,000 barrels ÷ 365).
D owns an oil property with producing wells X and Y on it. In 1975 D converts well X into an injection well. Prior to the application of the secondary process, it is estimated that without the application of the process the annual production from well X would have been 50x barrels of oil and from well Y would have been 100x barrels of oil. For the taxable year in which injection is commenced production from well X is 10x barrels and from well Y is 180x barrels. Fortyx barrels of oil [190x barrels of oil (actual production from the property)—150x barrels (estimate of primary production from the property)] qualify as secondary production.
E, a calendar year taxpayer, owns a domestic oil well which produced 100,000 barrels of oil in 1980. The proceeds from the sale of 15,000 barrels of that production are not includible in E's income until 1981. The 15,000 barrels produced in 1980 are included in E's average daily production for 1981 and excluded from such production for 1980. The tentative quantity and the percentage depletion rate for 1981 are applicable to the 15,000 barrels of oil.
| In the case of production after 1974 and to which gross income from the property is attributable for the calendar year: | The tentative quantity in barrels per day is: |
|---|---|
| 1975 | 2,000 |
| 1976 | 1,800 |
| 1977 | 1,600 |
| 1978 | 1,400 |
| 1979 | 1,200 |
| 1980 and thereafter | 1,000 |
| In the case of production after 1974 and to which gross income from the property is attributable for the calendar year: | The applicable percentage is: |
|---|---|
| 1975 | 22 |
| 1976 | 22 |
| 1977 | 22 |
| 1978 | 22 |
| 1979 | 22 |
| 1980 | 22 |
| 1981 | 20 |
| 1982 | 18 |
| 1983 | 16 |
| 1984 and thereafter | 15 |
A owns Y and Z oil producing properties. With respect to properties Y and Z, the percentage depletion allowable pursuant to section 613(a) (computed as if section 613 applied to all of the production at the rate specified in section 613A(c)(5)) for 1975 was $100x and $200x, respectively. A's average daily production for 1975 was 4,000 barrels. A's allowable depletion pursuant to section 613A(c) with respect to property Y was $50x ($100x depletion × 2,000 depletable oil quantity/ 4,000 average daily production). A's allowable depletion pursuant to section 613A(c) with respect to property Z was $100x ($200x depletion × 2,000 depletable oil quantity/ 4,000 average daily production).
B owns gas producing properties which had secondary gas production for 1975 of 3,285,000,000 cubic feet, which under section 613A(c)(4) is equivalent to 547,500 barrels of oil. B's average daily secondary production of gas for 1975 was equivalent to 1,500 barrels (547,500 barrels ÷ 365). B elected to have section 613A(c)(4) apply to the gas production. With respect to the production, the percentage depletion allowable pursuant to section 613(a) (computed at the rate specified in section 613A(c)(6)(A), as in effect prior to the Revenue Reconciliation Act of 1990) was $150x. B also owns an oil producing property which had primary oil production for 1975 of 365,000 barrels. B's average daily production of oil for 1975 was 1,000 barrels (365,000 ÷ 365). With respect to the oil property, the percentage depletion allowable pursuant to section 613(a) (computed as if section 613 applied to all of the production at the rate specified in section 613A(c)(5), as in effect prior to the Revenue Reconciliation Act of 1990) was $100x. B's depletable oil quantity for 1975 was 500 barrels (2,000 barrels tentative quantity −1,500 barrels average daily secondary production). B's allowable depletion pursuant to section 613A(c) with respect to the oil property was $50x ($100x depletion × 500 depletable oil quantity/ 1,000 average daily production).
Assume the same facts as in Example 2 except that B's primary production was 6,000,000 cubic feet of natural gas daily rather than its equivalent under section 613A(c)(4) of 1,000 barrels of oil and that B elected to have that section apply to such gas. B's allowable depletion pursuant to section 613A(c) with respect to B's primary production is $50x, the same as in example 2.
C is a partner with a one-third interest in Partnerships CDE and CFG with each partnership owning a single oil property. C's percentage depletion allowable under section 613(a) (computed as if section 613 applied to all of the production at the rate specified in section 613A(c)(5), as in effect prior to the Revenue Reconciliation Act of 1990) for 1975 was $20x with respect to 495,000 barrels (his allocable share of Partnership CDE production) and $40x with respect to 600,000 barrels (his allocable share of Partnership CFG production). C's average daily production is 3,000 barrels (1,095,000 total production ÷ 365 days). C's allowable depletion pursuant to section 613A(c) with respect to C's share of the production of Partnership CDE is $13.33x ($20x depletion × 2,000 depletable oil quantity/ 3,000 average daily production). C's allowable depletion pursuant to section 613A(c) with respect to C's share of the production of Partnership CFG is $26.67x ($40x depletion × 2,000 depletable oil quantity/ 3,000 average daily production). See § 1.613A-3(e) for the rules on computing depletion in the case of a partnership.
H owns a property which, during H's fiscal year which began on June 1, 1975, and ended on May 31, 1976, produced gas qualifying under section 613A(b) and oil qualifying under section 613A(c). For the fiscal year H's gross income from the property was $400x, of which $100x was from gas and $300x was from oil. For the oil his gross income from the property for the period beginning June 1, 1975, and ending December 31, 1975, was $100x and for the 1976 portion of the fiscal year was $200x. The percentage depletion allowance (before applying the 50 percent limitation of section 613(a) or the 65 percent limitation of section 613A(d)(1)) was $22x for the gas, $22x for the oil in 1975, and $44x for the oil in 1976. H's taxable income from the property for the fiscal year was $100x. In accordance with paragraph (d)(3) of this section, the taxable income from the property is allocated $25x to the gas:
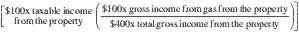
$25x to the 1975 oil:
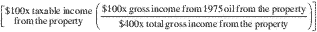
and $50x to the 1976 oil:
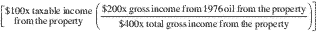
With the application of the 50 percent of taxable income from the property limitation, the allowable percentage depletion (computed without reference to section 613A) is limited to $12.50x for the gas, $12.50x for the oil in 1975, and $25x for the oil in 1976.
If the requirements of paragraph (e)(2)(ii) (A) and (B) of this section are met, a partner's proportionate share is determined in accordance with his or her proportionate interest in partnership income. The partners' shares of adjusted basis are determined on a property-by-property basis. Accordingly, the basis of one property may be allocated in proportion to capital and the basis of another property may be allocated in proportion to income. See §§ 1.613A-3(e)(5) and 1.704-1(b)(4)(v) for special rules concerning allocation of the adjusted basis of oil and gas properties.
A, B, and C have equal interests in capital in Partnership ABC. On January 1, 1992, the partnership acquired a producing domestic oil property. The partnership's basis in the property was $90x. The partnership allocated the adjusted basis of the property to each partner in proportion to the partner's interest in partnership capital. Accordingly, each partner was allocated an adjusted basis of $30x. Each partner must separately compute his or her depletion allowance. The amount of percentage depletion allowable for each partner for 1992 was $10x. On January 1, 1993, each partner's adjusted basis in the property was $20x ($30x minus $10x). On January 1, 1993, the oil property was sold for $150x. Each partner's gain was $30x ($50x allocable share of amount realized minus the partner's adjusted basis of $20x). Each partner must adjust the partner's adjusted basis in his or her partnership interest to reflect the gain.
The facts are the same as in Example 1 except that on January 1, 1993, the property was not sold but transferred by the partnership to partner A. A's basis in the property was $60x (the sum of A's, B's, and C's adjusted bases in the property).
The facts are the same as in Example 1 with the exception that in 1992 C was a retailer of oil and gas and was only entitled to a cost depletion deduction of $5x. C's gain from the sale of the mineral property on January 1, 1993, was $25x ($50x allocable share of amount realized minus C's adjusted basis of $25x ($30x minus $5x)).
D, a calendar year taxpayer, is a partner in Partnership DEF which owns a domestic producing oil property. On January 1, 1993, the partnership's adjusted basis in the property was $900x. On January 1, 1993, D's adjusted basis in D's partnership interest was $300x and D's adjusted basis in the partnership's oil property was $300x. D's allowable percentage depletion for 1993 with respect to production from the oil property was $50x. On January 1, 1994, D's adjusted basis in D's partnership interest was $250x and D's adjusted basis in the partnership's oil property was $250x ($300x minus $50x).
On January 1, 1990, G has an adjusted basis of $5x in partnership GH's proven domestic oil property, which is the sole asset of the partnership. On January 1, 1990 G sells G's partnership interest to I for $100x when the election under section 754 is in effect. I has a special basis adjustment for the oil property of $95x (the difference between I's basis, $100x, and I's share of the basis of the partnership property, $5x). I is not entitled to percentage depletion with respect to I's distributive share of the oil property income because I is a transferee of an interest in a proven oil property. However, I is entitled to cost depletion and for this purpose I's interest in the oil property has an adjusted basis to I of $100x ($5x, plus I's special basis adjustment of $95x).
On January 1, 1960, Partnership JK acquired a domestic producing oil property. On January 1, 1990, the partnership's adjusted basis in the property was zero. On January 1, 1990, L is admitted as a partner to the partnership. Since the partnership's adjusted basis in the oil property is zero, L's proportionate share of the basis in the property is also zero. L is not entitled to percentage depletion because L is a transferee of a proven oil property (see paragraph (g) of this section). Since the property's basis is zero, L is also not entitled to any cost depletion with respect to production from the property.
(i) O and P have equal interests in capital in Partnership OP. On January 1, 1991, the partnership acquired an unproven domestic oil property X the basis of which is $200x to the partnership. The partnership allocates $100x of the basis of the property to each partner in accordance with each partner's proportionate interest in partnership capital. For the 1991 taxable year, O has a $10x cost depletion allowance and P has a $25x percentage depletion allowance. Accordingly, at the end of the 1991 taxable year, O's adjusted basis in the property is $90x, and P's adjusted basis in the property is $75x. On January 1, 1992, Q is admitted as an equal partner. The partnership does not use written data from the partners and must therefore assume that each partner was entitled to $25x depletion based on the assumptions provided in § 1.613A-3(e)(3)(iii). This would result in a $50x combined depletion allowance for the partners and an aggregate adjusted basis in the oil property of $150x. Accordingly, the partnership allocates $50x of the basis of the property to Q, one-third of the aggregate adjusted basis determined by the partnership. O and P must each reduce their basis in the property by one-third. Accordingly, after the admission of Q, O's adjusted basis in the property is $60x ($90x minus $30x), and P's adjusted basis in the property is $50x ($75x minus $25x).
(ii) Assume the same facts as in paragraph (i) of this Example 7 except that O informs the partnership that its adjusted basis in the property is $90x (determined without regard to section 613A(d)(1)). The partnership uses the written data provided by O and determines the aggregate adjusted basis in the property to be $165x ($90x + $75x). Accordingly, the partnership allocates $55x ( 1/3 of $165x) of the basis of the property to Q, and O and P must each reduce their adjusted basis in the property by one-third, as in paragraph (i) of this Example 7. Thus, after the admission of Q, O's adjusted basis in the property is $60x and P's adjusted basis in the property is $50x.
A is the income beneficiary of a trust the only asset of which is a domestic producing oil property. The trust instrument requires that an amount which equals 10 percent of the gross income from the property be set aside annually as a reserve for depletion. In 1975 the property a had production of 1,095,000 barrels of oil. The trust's gross income from the property in 1975 was $30,000x. In that year, after setting aside $3,000x of income for the reserve for depletion, the trustee distributed the remaining income to A which represented 80 percent of the trust's net income. The percentage depletion computed by the trust with respect to the production (computed as if section 613 applied to all of the production at the rate specified in section 613A(c)(5), as in effect prior to the Revenue Reconciliation Act of 1990) for 1975 was $6,600x. The trust's average daily production for 1975 was 3,000 barrels (1,095,000 ÷ 365 days). The trust's allowable depletion pursuant to section 613A(c) with respect to the production was $4,400x:
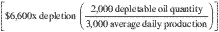
Pursuant to § 1.611-1(c)(4)(ii), the percentage depletion of $4,400x was apportioned between the trustee and A so that the trustee received $3,000x (an amount equal to the amount of income set aside for the reserve for depletion) and A received $1,400x of the depletion deduction. The $1,400x depletion received by A is attributable to 80 percent of the trust's depletable oil quantity, i.e., 1,600 barrels per day.
B, a retailer of oil and gas, is the income beneficiary of a trust the only asset of which is a domestic producing oil property. In 1975 the trustee distributed one-half of the trust's net income and accumulated the other one-half for the benefit of the remainderman. One-half of the percentage depletion computed by the trust with respect to the production from the property was apportioned to B. Since B is a retailer of oil and gas, B is not entitled to deduct any of the percentage depletion apportioned to B. However, B is entitled to take cost depletion with respect to one-half of the production from the oil property, notwithstanding the fact that depletion was computed at the trust level on the basis of percentage depletion.
A owns 50 percent of the stock of Corporation M and 50 percent of the stock of Corporation N. Both corporations are calendar year taxpayers. For 1975 Corporation M's production of domestic crude oil was 8,000,000 barrels (365,000 of which was secondary production) and Corporation N's was 2,000,000 barrels (all of which was primary production). The tentative quantity (2,000 barrels per day) determined under the table in section 613A (c)(3)(B) (as in effect prior to the Revenue Reconciliation Act of 1990) must be allocated between the two corporations in proportion to their respective barrels of production of domestic crude oil during the taxable year. Corporation M's allocable share of the tentative quantity is 1,600 barrels:

and Corporation N's allocable share is 400 barrels:

With respect to M's primary production, M's depletable oil quantity is 600 barrels (1,600 barrels − 1,000 barrels [365,000 secondary production ÷ 365 days]). N's depletable oil quantity, unaffected by M's secondary production, is 400 barrels.
Assume the same facts as in Example 1 except that Corporation M is a retailer and Corporation N is not selling its oil through Corporation M. Because Corporation M is a retailer, no portion of the tentative quantity is allocated to Corporation M. Accordingly, Corporation N's depletable oil quantity is the entire 2,000 barrels per day because section 613A (c), which contains the allocation requirements, is inapplicable to retailers.
Corporations O and P are members of a controlled group and are treated as one taxpayer as provided in paragraph (h)(1) of this section. Corporation O owns oil properties A and B. Property A had primary production for 1975 of 800,000 barrels of oil. Property B had secondary production for 1975 of 365,000 barrels of oil. Corporation P owns oil property C which had primary production of 660,000 barrels for 1975. The allowable percentage depletion with respect to property B's secondary production was $360x. The controlled group's average daily production was 4,000 barrels [(800,000 + 660,000) ÷ 365]. The controlled group's depletable oil quantity was 1,000 barrels [2,000 tentative quantity − 1,000 average daily secondary production (365,000 ÷ 365)]. The allowable percentage depletion pursuant to section 613 (a) (computed as if section 613 applied to all of the production at the rate specified in section 613A (c)(5), as in effect prior to the Revenue Reconciliation Act of 1990) was $800x with respect to production from property A and $660x with respect to production from property C.
Corporation O's allowable depletion pursuant to section 613A (c) with respect to property B's secondary production (for which depletion is allowable before primary production) for 1975 was $360x. Corporation O's allowable depletion pursuant to section 613A (c) with respect to property A was $200x:
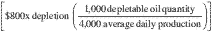
Therefore, Corporation O's allowable depletion pursuant to section 613A (c) was $560x ($360x relating to property B plus $200x relating to property A). Corporation P's allowable depletion pursuant to section 613A (c) with respect to property C was $165x:
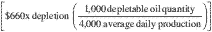
On January 1, 1975, Individual A transfers proven oil properties to Corporation M in an exchange to which section 351 applies for shares of its stock. Since there is no allocation requirement pursuant to section 613A(c)(8) between A (the transferor) and Corporation M (the transferee), the transfer of the proven properties by A is a transfer for purposes of section 613A(c)(9) (as in effect prior to the Revenue Reconciliation Act of 1990) and percentage depletion is not allowable to Corporation M with respect to such properties.
On January 1, 1975, Corporation N sells proven oil property to Corporation O, its wholly-owned subsidiary. Because the transfer was made between corporations which are members of the same controlled group of corporations, Corporation O is entitled to percentage depletion with respect to production from the property so long as the tentative oil quantity is allocated between the two corporations. If Corporation N were a retailer, the tentative oil quantity would not be required to be allocated between the two corporations (see example 2 of § 1.613A-3(h)(5)), and Corporation O would not be entitled to percentage depletion on the production from the property.
B, owner of a proven oil property, died on January 1, 1975. Pursuant to the provisions of B's will, B's estate transferred the oil property on April 1, 1975, into a trust. On July 1, 1976, pursuant to a requirement in B's will, the trustee distributed the oil property to C. The transfer of the oil property by the estate to the trust and the later distribution of the property by the trust to C are transfers at death. Therefore, the trust was entitled to compute percentage depletion with respect to the production from the oil property when the property was owned by the trust and C is entitled to percentage depletion with respect to production from the oil property after the trust distributes the property to C.
On January 1, 1975, property which produces oil resulting from secondary processes was transferred to D. The exemption under section 613A(c) applies to D because section 613A(c)(9) (relating to transfers of oil or gas property), as in effect in 1975, does not apply with respect to secondary production. In addition, even if at the time of the transfer the production from the property was primary and D applied secondary processes to the property transferred and obtained secondary production, D would be entitled to percentage depletion with respect to the secondary production.
On July 1, 1975, E and F entered into a contract whereby F is given the privilege of drilling a well on E's unproven property, and if F does so F is to own the entire working interest in the property until F has recoverd all the costs of drilling, equipping, and operating the well. Thereafter, 50 percent of the working interest would revert to E. In accordance with the contract, 50 percent of the working interest reverted to E on July 1, 1976. F is entitled to percentage depletion because the transfer of the working interest to F occurred when the property was unproven on July 1, 1975, which is the date of the contract establishing F's right to the working interest. E is entitled to percentage depletion with respect to this working interest since the reversion of such interest with respect to which E was eligible for percentage depletion is not a transfer. However, if on the date of the contract E's property was proven (although not proven when E acquired the property), F would not be entitled to claim percentage depletion with respect to any of the working interest income. Nonetheless, E would still be entitled to percentage depletion with respect to E's working interest since the reversion of the interest is not a transfer.
On January 1, 1975, G subleased an oil property to H, retaining a 1/8 royalty interest with the option to convert G's royalty into a 50-percent working interest. On July 1, 1975, the property was proven and on July 1, 1976, G exercised G's option. G is entitled to claim percentage depletion with respect to G's working interest since the conversion of the royalty interest which is eligible for percentage depletion pursuant to section 613A(c) into an interest which constituted part of an interest previously owned by G is not a transfer pursuant to § 1.613A-7(n)(8).
I and J (both of whom are minors) are beneficiaries of a trust which owned a proven oil property. The oil property was transferred to the trust on January 1, 1975, by the father of I and J. For 1975, the trustee allocated all the income from the oil property to I. For 1976, the trustee allocated all the income from such property to J. On January 1, 1977, the trustee distributed the property to I and J as equal tenants in common. Since I, J, and their father are members of the same family within the meaning of section 613A(c)(8)(C), the transfer of the property to the trust by the father, the shifting of income between I and J, and the distribution of the oil property by the trust to I and J are not transfers for purposes of section 613A(c)(9) (as in effect prior to the Revenue Reconciliation Act of 1990). However, the distribution of the oil property will constitute a transfer to each distributee on the date on which the distributee reaches majority under state law.
In 1975, K transferred a proven oil property productive at 5,000 feet to L. Subsequent to the transfer, L drilled new wells on the property finding another reservoir at 10,000 feet. The two zones were combined under section 614 as a single property. L is not entitled to percentage depletion on the gross income attributable to the production from the productive zone at 5,000 feet, but is entitled to percentage depletion on the gross income attributable to the production from the productive zone at 10,000 feet because that zone was not part of the proven property until the date of development expenses by L, which is after the date of the transfer. Accordingly, L's maximum allowable percentage depletion deduction for 1975 would be zero percent of gross income from the property with respect to the production from 5,000 feet, plus 22 percent of gross income from the property with respect to the production from 10,000 feet. This maximum deduction would be subject to the limitation provided for in section 613(a), i.e.,50 percent of “taxable income from the property (computed without allowance for depletion),” such taxable income being the overall taxable income resulting from the sale of production from both zones, and would also be subject to the limitations provided in section 613A. The production from the productive zone at 5,000 feet is not taken into account in determining K's depletable oil quantity for the year.
On July 1, 1975, M transferred an oil property with a fair market value of $100x to N. On February 1, 1976, N commenced production of oil from the property. The fair market value of the property on February 1, 1976, as reduced by actual costs incurred by N for equipment and intangible drilling and development costs, was $300x. Because the value of the property on transfer was not 50 percent or more of the value on February 1, 1976, the property transferred to N was not a proven property (see § 1.613A-7(p)). However, if there had been only marginal production from the property so that the fair market value of the property on February 1, 1976, was $40x rather than $300x, the property transferred to N would have been a proven property provided the other requirements of a proven property were met.
O is the owner of a remainder interest in a trust created January 1, 1970. On that date, the trust held oil and gas properties. On January 1, 1976, O's interest for the first time entitled O to the trust's income from oil and gas production from the properties. The reversion of the remainder interest to O is not a transfer (see § 1.613A-7(n)(7)). Accordingly, the transfer of the interest in oil and gas property to O is deemed to have occurred on January 1, 1970, the date O's interest was created.
On January 1, 1976, P, Q, and R entered into a partnership for the acquisition of oil and gas leases. It was agreed that the sharing of income will be divided equally among P, Q, and R. However, it was further agreed that with respect to the first production obtained from each property acquired P will receive 80 percent thereof and Q and R each will receive 10 percent thereof until $100x has been received by P. Assume these allocations have substantial economic effect under section 704 of the Code and the regulations thereunder. On February 1, 1976, Partnership PQR acquired an unproven property and production therefrom was shared pursuant to the partnership agreement. P is entitled to percentage depletion with respect to the production allocated to him since the transfer of right to the production is deemed to have been made on the date the partnership agreement became applicable to the specific property, at which time the property was unproven. See § 1.613A-7(n) for rules relating to the definition of transfer. Similarly, when $100x has been obtained and Q and R each commence receiving 33 1/3 percent of the revenue, Q and R are entitled to percentage depletion with respect to their entire interests. However, if the property had been proven when acquired by the partnership, P, Q, and R would not be entitled to claim any percentage depletion with respect to production from the property.
On December 30, 1960, S placed producing oil property in trust for the benefit of S's nephew, T, and executed a trust agreement which required the trustee of the trust to transfer the oil property to T on January 1, 1975. The trustee's transfer of the oil property to T on January 1, 1975, is deemed to have occurred on December 30, 1960 (see § 1.613A-7(n)). Since the transfer is deemed to have occurred before January 1, 1975, section 613A(c) applies with respect to the production from the oil property. Moreover, if the trustee was not required to transfer the oil property on a specific date but was given discretion to select the date of transfer, the transfer of such property would still be deemed to have occurred on December 30, 1960. However, the result would be different if the trust agreement had provided that the trustee, at the trustee's discretion, may transfer the oil property to T on January 1, 1975, but is not under any obligation to transfer the property to T on January 1, 1975, or on any other date. Since the transfer was discretionary, the date of the actual transfer governs.
On January 1, 1974, U acquired an oil property. On February 1, 1974, U granted V an option to purchase the oil property. V exercised V's option on March 2, 1975, and subsequently the oil property was conveyed to V. The date of the transfer was March 2, 1975, the day V exercised V's option (on which date both parties were bound).
On July 1, 1974, W executed a deed conveying oil and gas property to X. W delivered the deed to X on January 1, 1975. Under state law, the mere execution of the deed without delivery did not give X any rights in the property. Title to the oil property passed to X on the date of delivery. Therefore, the date of transfer was January 1, 1975.
Y, owner of a proven oil property, transferred Y's interest therein on July 25, 1975, to a revocable trust of which Y is treated as the owner under section 676. Y is not deemed a transferee and section 613A(c) applies to Y because immediately preceding the transfer Y was entitled to percentage depletion on the production from the property.
On January 1, 1975, a proven oil property was transferred to Z; therefore, section 613A(c)(1) did not apply with respect to the production from such property. After Z's death, neither Z's estate nor its beneficiaries are entitled to percentage depletion with respect to the decedent's oil property since Z was a transferee of proven property.
Partnership ABC, owner of proven oil and gas properties, admitted D as a partner in 1975 in consideration of cash. The shares of Partners A, B, and C of the partnership income were proportionately reduced so that D had a 25 percent interest in the income. D is not entitled to percentage depletion with respect to D's share of partnership oil and gas income because D is a transferee for purposes of section 613A(c)(9) (as in effect prior to the Revenue Reconciliation Act of 1990). See § 1.613A-7(n).
On January 1, 1975, E and F formed Partnership EF to which E contributed proven oil property. For 1975, pursuant to the partnership agreement 70 percent of the mineral income from the property was allocated to E and 30 percent of the mineral income from the property was allocated F. F is not entitled to percentage depletion with respect to production from the property because F is a transferee of an interest in proven property. However, E is not a transferee of an interest in proven property because E was entitled to percentage depletion on the oil produced with respect to the property immediately before the transfer. Therefore, E is entitled to percentage depletion with respect to the income allocated to E. However, if in 1976 the partnership agreement were revised so that E's interest in the income was increased by 10 percent, E would not be entitled to percentage depletion with respect to the additional 10 percent interest because E is a transferee with respect thereto.
G is the owner of a 1/3 interest in a partnership owning a proven oil property, and as such is entitled to 1/3 of the income from the property. G received a distribution on July 1, 1975, from the partnership of a 1/3 interest in the proven oil property. Although the transfer of such interest is a transfer for purposes of section 613A(c)(9) (as in effect prior to the Revenue Reconciliation Act of 1990), G is still entitled to percentage depletion with respect to the 1/3 interest in the oil production from the property since G was entitled to percentage depletion on such production with respect to such property immediately before the transfer. If the entire property were distributed to G, G's percentage depletion allowance would still be based on only 1/3 of the oil produced.
H and I contributed property X and property Y respectively to Partnership HI. The partnership agreement provides that all the gross income from property X is to be allocated to H and all the gross income from property Y is to be allocated to I. Assume these allocations have substantial economic effect under section 704 of the Code and the regulations thereunder. For 1975 H and I each received $100x gross income. Although the contributions of the properties by H and I are transfers for purposes of section 613A(c)(9) (as in effect prior to the Revenue Reconciliation Act of 1990), both H and I are entitled to percentage depletion with respect to the $100x income received since each was entitled to a percentage depletion allowance with respect to the property contributed immediately before the transfer. However, if no special allocation of income were made but H and I are to share equally in the income from both properties, each would be entitled to a depletion allowance based on only one-half of the production with respect to the property he had contributed. If property X produces $100x of gross income from the property and property Y produces $200x of gross income from the property, H would be entitled to percentage depletion but only with respect to $50x (50 percent of $100x) of gross income from the property and I would be entitled to percentage depletion with respect to $100x (50 percent of $200x) of gross income from the property.
On December 31, 1991, A transfers a proven oil property to B. B may claim percentage depletion with respect to production from the property regardless of whether production from the property was eligible for percentage depletion in A's hands (even if A were a retailer or refiner of oil or gas).
On October 10, 1990, A transfers a proven oil property to B. B may not claim percentage depletion with respect to production from the property.
On January 1, 1990, C purchases a proven oil property. Because C is a transferee of a proven property, production from the property is not eligible for percentage depletion in C's hands. On December 31, 1991, C contributes the property to Corporation M, an S corporation in which C owns 100 percent of the stock. The contribution of the property is a transfer, but C is not a transferee with respect to the property in the hands of the corporation. Accordingly, C may not claim percentage depletion with respect to production from the property. However, if prior to the contribution C had been entitled to claim percentage depletion with respect to production from the property, C would be entitled to claim percentage depletion with respect to production from the property after the contribution.
On December 31, 1991, C contributes a proven oil property (with respect to which C is not entitled to claim percentage depletion) to Corporation N, an S corporation in which C owns 30 percent and D owns 70 percent of the stock. The contribution of the property is a transfer, but C is not a transferee with respect to the property in the hands of the corporation. Accordingly, C may not claim percentage depletion with respect to C's share of the production from the property. D is a transferee with respect to the property in the hands of Corporation N, and may claim percentage depletion with respect to D's share of production from the property.
On December 31, 1991, D transfers a proven oil property (with respect to which D is not entitled to claim percentage depletion) to DE, an equal partnership between D and E. E is a transferee with respect to the property and may claim percentage depletion with respect to production from the property allocated to E under the DE partnership agreement. D is not a transferee with respect to the property, and may not claim percentage depletion with respect to production from the property allocated to D under the DE partnership agreement. However, if D had been entitled to claim percentage depletion with respect to production from the property, then D would be entitled to claim percentage depletion with respect to production from the property in the hands of DE.
On January 1, 1990, Corporation P contributes a proven property to Corporation O, its wholly owned subsidiary. Under § 1.613A-7(n)(4), the contribution is not treated as a transfer, but only for so long as the tentative quantity is required under section 613A(c)(8) to be allocated between P and O. On December 31, 1991, P sells 90% of the O stock to an unrelated person; accordingly, the tentative quantity is no longer required under section 613A(c)(8) to be allocated between P and O. After the sale of O stock, production from the property in O's hands is eligible for percentage depletion because a transfer of a proven property is deemed to occur upon the transfer of the stock.
On October 10, 1990, G transfers a proven oil property to his minor son, H. G had been entitled to claim percentage depletion with respect to production from the property. Under § 1.613A-7(n)(5), H is permitted to claim percentage depletion for so long as G and H are related persons under section 613A(c)(8)(C). On December 31, 1991, H reaches majority and is no longer related to G under section 613A(c)(8)(C). H is entitled to continue to claim percentage depletion on production from the property because the property is treated as being transferred to H on December 31, 1991.
On December 31, 1991, I sells a proven property to J, her husband. I had not been entitled to claim percentage depletion with respect to production from the property. Under § 1.613A-7(n)(5), the sale is not a transfer because it is made between persons related under section 613A(c)(8). Accordingly, J may not claim percentage depletion with respect to production from the property. If, however, I had been entitled to claim percentage depletion with respect to production from the property, J would be entitled to claim percentage depletion with respect to production from the property.
On December 31, 1991, L inherits a proven property from K. K had not been entitled to claim percentage depletion with respect to production from the property. Under § 1.613A-7(n)(1), the inheritance is not a transfer. Accordingly, L may not claim percentage depletion with respect to production from the property. If, however, K had been entitled to claim percentage depletion with respect to production from the property, L would be entitled to claim percentage depletion with respect to production from the property.
On December 31, 1991, Corporation R, a calendar year taxpayer, made an S election effective for the taxable year beginning January 1, 1992 and succeeding taxable years. Since Corporation R is deemed to have transferred its oil and gas properties on January 1, 1992, the shareholders of Corporation R are eligible to claim percentage depletion with respect to the production from the properties.
Assume the same facts as in Example 10 except that Corporation R makes the S election on December 31, 1989, effective for the taxable year beginning January 1, 1990 and succeeding taxable years. Since Corporation R is deemed to have transferred its oil and gas properties on January 1, 1990, the shareholders of Corporation R are not eligible to claim percentage depletion with respect to the production from the properties.
[T.D. 8348, 56 FR 21939, May 13, 1991; 57 FR 4913, Feb. 10, 1992; 57 FR 9599, Mar. 19, 1992, as amended by T.D. 8437, 57 FR 43900, Sept. 23, 1992; 57 FR 60474, Dec. 21, 1992; 58 FR 6678, Feb. 1, 1993]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 613A Limitations on percentage depletion in case of oil and gas wells
- § 611 Allowance of deduction for depletion
- § 613 Percentage depletion
- § 743 Special rules where section 754 election or substantial built-in loss
- § 263 Capital expenditures
- § 704 Partner’s distributive share
- § 1016 Adjustments to basis
- § 705 Determination of basis of partner’s interest
- § 751 Unrealized receivables and inventory items
- § 754 Manner of electing optional adjustment to basis of partnership property
- § 732 Basis of distributed property other than money
- § 734 Adjustment to basis of undistributed partnership property where section 754 election or substantial basis reduction
- § 351 Transfer to corporation controlled by transferor
- § 614 Definition of property
- § 61 Gross income defined
- § 6501 Limitations on assessment and collection
Regulations it cites
- § 1.613A-4 Limitations on application of § 1.613A-3 exemption.
- § 1.613A-7 Definitions.
- § 1.613A-2 Exemption for certain domestic gas wells.
- § 1.704-1 Partner's distributive share.
- § 1.705-1 Determination of basis of partner's interest.
- § 1.611-1 Allowance of deduction for depletion.
- § 1.613-2 Percentage depletion rates.
- § 1.612-3 Depletion; treatment of bonus and advanced royalty.
Cited by 7 other regulations
- § 1.612-3 Depletion; treatment of bonus and advanced royalty.
- § 1.613A-0 Limitations on percentage depletion in the case of oil and gas wells; table of contents.
- § 1.613A-2 Exemption for certain domestic gas wells.
- § 1.613A-4 Limitations on application of § 1.613A-3 exemption.
- § 1.613A-7 Definitions.
- § 1.702-1 Income and credits of partner.
- § 1.743-1 Optional adjustment to basis of partnership property.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended (58 FR 6678)
- Amended (57 FR 60474)
- Amended by T.D. 8437 (57 FR 43900)
- Amended (57 FR 9599)
- Amended (57 FR 4913)
- Issued by T.D. 8348 (56 FR 21939)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Natural Resources
Nearby sections
- § 1.613-7 Application of percentage depletion rates provided in section 613(b) to certain taxable years ending in 1954.
- § 1.613A-0 Limitations on percentage depletion in the case of oil and gas wells; table of contents.
- § 1.613A-1 Post-1974 limitations on percentage depletion in case of oil and gas wells; general rule.
- § 1.613A-2 Exemption for certain domestic gas wells.
- § 1.613A-3 Exemption for independent producers and royalty owners.
- § 1.613A-4 Limitations on application of § 1.613A-3 exemption.
- § 1.613A-5 Election under section 613A(c)(4).
- § 1.613A-6 Recordkeeping requirements.
- § 1.613A-7 Definitions.