
Treasury Regulations · 26 CFR
§ 1.72-17A. Special rules applicable to employee annuities and distributions under deferred compensation plans to self-employed individuals and owner-employees.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 72
Cite as 26 CFR § 1.72-17A
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- August 10, 1979 by T.D. 7636
- Last amended
- March 14, 2019 by T.D.9849
- Issued under
- 26 U.S.C. § 72
- Length
- 4,619 words · about 20 min to read
- Defines
- 3 terms
- Cross-references
- cites 9 Code sections and 6 regulations; cited by 1
For purposes of this paragraph the term “consideration paid or contributed for the contract” has the same meaning as under subparagraphs (1), (2), and (3) of paragraph (c) of this section.
The cost of such insurance protection will be considered to be a reasonable net premium cost, as determined by the Commissioner, for the appropriate period.
If an amount is not included in the amounts referred to in subdivision (i)(A) of this subparagraph solely by reason of the owner-employee's becoming disabled and if a penalty would otherwise be applicable with respect to all or a portion of such amount, then for the owner-employee's taxable year in which such amount is received, there must be submitted with his income tax return a doctor's statement as to the impairment, and a statement by the owner-employee with respect to the effect of such impairment upon his substantial gainful activity and the date such impairment occurred. For taxable years which are subsequent to the first taxable year with respect to which the statements referred to in the preceding sentence are submitted, the owner-employee may, in lieu of such statements, submit a statement declaring the continued existence (without substantial diminution) of the impairment and its continued effect upon his substantial gainful activity.
(1) A was a member of the X partnership, consisting of partners A through I, and a participant in the partnership's qualified profit-sharing plan which was established on January 1, 1972. A's taxable years, the X partnership's taxable years, the plan years, and other relevant years are all calendar years at all relevant times. For the three calendar years, 1972 through 1974, A was an owner-employee in the X partnership. On January 1, 1975, new partners J and K became partners in the X partnership, and as of that date, each of partners A through K held a 1/11 interest in the capital and profits of the X partnership. On that date, A became a partner who was not an owner-employee. A continued in this status for the 2 calendar years 1975 and 1976. On January 1, 1977, when A was 50 years old and not disabled, he liquidated his interest in the X partnership and became an employee of an unrelated employer. On that date, A received a distribution representing his entire interest in the X partnership's plan of $54,000 cash in violation of the plan provision required by section 401(d)(4)(B). As of that date, the distribution was attributable to the following sources and times, computed by the plan in a manner consistent with the subparagraph:
| Calendar years | A | B | C | D |
|---|---|---|---|---|
| X contributions on behalf of A deductible under sec. 404 | A's contributions made as an employee | Increments in value attributable to column A yearly contributions | Increments in value attributable to column B yearly contributions | |
| 1977 | 0 | 0 | 0 | 0 |
| 1976 | $7,500 | $2,500 | $900 | $300 |
| 1975 | 7,500 | 2,500 | 4,000 | 1,300 |
| 1974 | 7,500 | 2,500 | 1,800 | 700 |
| 1973 | 2,500 | 2,500 | 1,200 | 1,200 |
| 1972 | 2,500 | 2,500 | 1,300 | 1,300 |
| Totals | 27,500 | 12,500 | 9,200 | 4,800 |
(2) The amount of the $54,000 distribution to which subdivision (i)(A) of this subparagraph applies is $20,000, computed as follows:
| X contributions on behalf of A made in years A was an owner-employee: | |
| 1974 | $7,500 |
| 1973 | 2,500 |
| 1972 | 2,500 |
| Total | 12,500 |
| Increments in value attributable to such contributions: | |
| 1974 | 1,800 |
| 1973 | 1,200 |
| 1972 | 1,300 |
| Total | 4,300 |
| Increments in value attributable to contributions made by A as an employee for years in which he was an owner-employee: | |
| 1974 | 700 |
| 1973 | 1,200 |
| 1972 | 1,300 |
| Total | 3,200 |
| Grand total | 20,000 |
In this example, the $20,000 amount computed above would be includible in A's gross income for 1977 and would be subject to the 10 percent tax described in subparagraph (1)(i) of this paragraph.
(3) Subdivision (i)(A) of this subparagraph does not apply to the contributions made by X on behalf of A for 1976 and 1975 ($7,500 each year, totaling $15,000) nor to the increments in value attributable to those contributions ($900 for 1976 and $4,000 for 1975, totaling $4,900), because A was not an owner-employee with respect to these two years, 1976 and 1975, on account of which these employer contributions were made. For the same reason, subdivision (i)(A) of this subparagraph does not apply to the increments in value attributable to A's contributions for 1976 and 1975 ($300 and $1,300, respectively, totaling $1,600).
See section 4972(c) for the amount of employee contributions which is permitted to be contributed by an owner-employee (as an employee) without subjecting an owner-employee to the tax on excess contributions.
(4) Subdivision (i)(A) of this subparagraph does not apply to the contributions made by A, as an employee during the years when he was an owner-employee ($2,500 during each of the years 1972, 1973, and 1974, totaling $7,500), because the distribution was received in a taxable year of A ending after September 2, 1974; see subparagraph (3) of this paragraph. Furthermore, because the distribution of the amount of A's contributions ($12,500) constitutes consideration for the contract paid by A for purposes of section 72, the $7,500 amount described in the preceding sentence is not includible in his gross income, and that amount is not subject to the rules of this subparagraph; see subdivision (i) of this subparagraph, and paragraphs (b) and (c) of this section.
B was a member of the XYZ Partnership and a participant in the partnership's profit-sharing plan which was created in 1973. Until the end of 1977, B's interest in the partnership was less than 10 percent. On January 1, 1978, B obtained an interest in excess of 10 percent in the partnership and continued to participate in the profit-sharing plan until 1982. During 1982, prior to the time he attained the age of 59 1/2 years and during a time when he was not disabled, B, who had not received any prior plan distributions, withdrew his entire interest in the profit-sharing plan. At the time his interest was $15,000, $9,600 contributions and $5,400 increment attributable to the contributions. The portion of the increment attributable to contributions while B was an owner-employee is $667.80, determined as follows:
| A | B | C | |
|---|---|---|---|
| Contribution | Number of years contribution was in trust | Contribution weighted for years in trust (A × B) | |
| 1982 | $1,000 | 0 | 0 |
| 1981 | 800 | 1 | 800 |
| 1980 | 1,200 | 2 | 2,400 |
| 1979 | 600 | 3 | 1,800 |
| 1978 | 200 | 4 | 800 |
| 1977 | 400 | 5 | 2,000 |
| 1976 | 2,000 | 6 | 12,000 |
| 1975 | 1,000 | 7 | 7,000 |
| 1974 | 1,500 | 8 | 12,000 |
| 1973 | 900 | 9 | 8,100 |
| Total | 9,600 | 46,900 |
Total weighted contributions as owner-employee (1978-1982) = $5,800.
Total weighted contributions = $46,900.
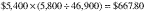
For purposes of (iii) of this subdivision, the time of contributions made on the basis of any employer taxable year shall take into account the rule specified in section 404(a)(6), relating to time when contributions deemed made.
The existence of one or more of the impairments described in this subparagraph (or of an impairment of greater severity) will not, however, in and of itself always permit a finding that an individual is disabled as defined in section 72(m)(7). Any impairment, whether of lesser or greater severity, must be evaluated in terms of whether it does in fact prevent the individual from engaging in his customary or any comparable substantial gainful activity.
[T.D. 7636, 44 FR 47049, Aug. 10, 1979, as amended by T.D. 8894, 65 FR 46591, July 31, 2000; T.D.9849, 84 FR 9233, Mar. 14, 2019]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 72 Annuities; certain proceeds of endowment and life insurance contracts
- § 401 Qualified pension, profit-sharing, and stock bonus plans
- § 408 Individual retirement accounts
- § 404 Deduction for contributions of an employer to an employees’ trust or annuity plan and compensation under a deferred-payment plan
- § 501 Exemption from tax on corporations, certain trusts, etc.
- § 403 Taxation of employee annuities
- § 4972 Tax on nondeductible contributions to qualified employer plans
- § 2001 Imposition and rate of tax
- § 402 Taxability of beneficiary of employees’ trust
Regulations it cites
- § 1.72-16 Life insurance contracts purchased under qualified employee plans.
- § 1.72-6 Investment in the contract.
- § 1.72-13 Special rule for employee contributions recoverable in three years.
- § 1.72-11 Amounts not received as annuity payments.
- § 1.72(p)-1 Loans treated as distributions.
- § 1.72-17 Special rules applicable to owner-employees.
Cited by 1 other regulation
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D.9849 (84 FR 9233)
- Amended by T.D. 8894 (65 FR 46591)
- Issued by T.D. 7636 (44 FR 47049)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Items Specifically Included in Gross Income
Nearby sections
- § 1.72-14 Exceptions from application of principles of section 72.
- § 1.72-15 Applicability of section 72 to accident or health plans.
- § 1.72-16 Life insurance contracts purchased under qualified employee plans.
- § 1.72-17 Special rules applicable to owner-employees.
- § 1.72-17A Special rules applicable to employee annuities and distributions under deferred compensation plans to self-employed individuals and owner-employees.
- § 1.72-18 Treatment of certain total distributions with respect to self-employed individuals.
- § 1.72(e)-1T Treatment of distributions where substantially all contributions are employee contributions (temporary).
- § 1.72(p)-1 Loans treated as distributions.
- § 1.73-1 Services of child.