
Treasury Regulations · 26 CFR
§ 1.911-4. Determination of housing cost amount eligible for exclusion or deduction.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 911
Cite as 26 CFR § 1.911-4
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- January 23, 1985 by T.D. 8006
- Issued under
- 26 U.S.C. § 911
- Length
- 2,972 words · about 13 min to read
- Defines
- 3 terms
- Cross-references
- cites 8 Code sections and 2 regulations; cited by 4
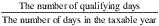
For purposes of the above fraction, the number of qualifying days is determined in accordance with § 1.911-3(d)(3).
B, a U.S. citizen is a calendar year taxpayer who was a bona fide resident of and whose tax home was located in foreign country G for the entire taxable year 1982. B receives an $80,000 salary from B's employer for services performed in G. B incurs no business expenses. B receives housing provided by B's employer with a fair rental value of $15,000. The value of the housing furnished by B's employer is not excluded from gross income under section 119. B pays $10,000 for housing expenses. B's gross income and foreign earned income for 1982 is $95,000. B elects the foreign earned income exclusion of section 911(a)(1) and the housing cost amount exclusion of section 911(a)(2). B must first compute his housing cost amount exclusion. B's housing cost amount is $18,650 determined by reducing B's housing expenses, $25,000 ($15,000 fair rental value of housing and $10,000 of other expenses), by the base housing amount of $6,350 (($39,689 × .16) × 365/365). Because B has no income from self-employment, the entire amount is attributable to employer provided amounts and therefore, is excludable. B's section 911(a)(1) limitation is $75,000. That is the lesser of $75,000 × 365/365 or $95,000−18,650. B's total exclusion for 1982 under section 911(a)(1) and (2) is $93,650.
The facts are the same as in example 1 except that B's salary for 1982 is $70,000. B's foreign earned income for 1982 is $85,000. B's housing cost amount is $18,650, all of which is attributable to employer provided amounts. B's housing cost amount is excludable to the extent of the lesser of B's housing cost amount attributable to employer provided amounts, $18,650, or the foreign earned income for the taxable year, $85,000. Thus, B excludes $18,650 under section 911(a)(2). B's section 911(a)(1) limitation for 1982 is $66,350 (the lesser of $75,000 × 365/365 or $85,000−18,650). B's total exclusion for 1982 under section 911(a)(1) and (2) is $85,000.
The facts are the same as in example 2 except that in 1983, B receives $5,000 attributable to services performed in 1982. B may exclude the entire $5,000 in 1983 because such amount would have been excludable under § 1.911-3(d)(1) had it been received in 1982.
C is a U.S. citizen self-employed and a calendar year and cash basis taxpayer. C arrived in foreign country H on October 3, 1982, and departed from H on March 8, 1984. C's tax home was located in H throughout that period. C was physically present for 330 full days during the twelve consecutive month period August 30, 1982, through August 29, 1983. The number of C's qualifying days in 1982 is 124. During 1982 C had $35,000 of foreign earned income, none of which was attributable to employer provided amounts and $8,000 of reasonable housing expenses. C's housing cost amount is $5,843 ($8,000−((39,689 × .16) × 124/365)). C elects to exclude her foreign earned income under § 1.911-3(d)(1). C's section 911(a)(1) limitation for 1982 is $25,479 (the lesser of C's foreign earned income for the taxable year ($35,000) or the annual rate for the taxable year multiplied by the number of C's qualifying days over the number of days in the taxable year ($75,000 × 124/365 = $25,479). C may not claim the housing cost amount exclusion under section 911(a)(2) because no portion of the housing cost amount is attributable to employer provided amounts. C may deduct the lesser of her housing cost amount ($5,843) or her foreign earned income in excess of amounts excluded under section 911(a) ($35,000−25,479 = $9,521). Thus, C's housing cost amount deduction is $5,843.
The facts are the same as in example 4 except that C had $30,000 of foreign earned income for 1982, none of which was attributable to employer provided amounts. C elects to exclude $25,479 under § 1.911-3(d)(1). C may only deduct $4,521 of her housing cost amount under paragraph (e)(1) of this section because her foreign earned income in excess of amounts excluded under section 911(a) is $4,521($30,000−25,479). The $1,322 of unused housing cost amount deduction may be carried over to the subsequent taxable year.
The facts are the same as in example 4 except that C had $15,000 of foreign earned income of 1982, none of which was attributable to employer provided amounts. C elects to exclude the entire $15,000 under § 1.911-3(d)(1). C is not entitled to a housing cost amount deduction for 1982 since she has no foreign earned income in excess of amounts excluded under section 911(a). C may carry over her entire housing cost amount deduction to 1983.
The facts are the same as in example 6. In addition, during taxable year 1983 C had $115,000 of foreign earned income, none of which was attributable to employer provided amounts, and $40,000 of reasonable housing expenses C elects to exclude her foreign earned income under § 1.911-3(d)(1). C's section 911(a)(1) limitation is the lesser of $115,000 or $80,000 ($80,000 × 365/365). C's housing cost amount for 1983 is $33,650 (40,000−(39,689 × .16) × 365/365). Since no portion of that amount is attributable to employer provided amounts, C may not claim a housing cost amount exclusion. C may deduct the lesser of her housing cost amount ($33,650) or her foreign earned income in excess of amounts excluded under section 911(a) ($115,000−80,000 = 35,000). Thus, C may deduct her $33,650 housing cost amount in 1983. In addition, C may deduct $1,350 of the housing cost amount deduction carried over from taxable year 1982.
(($115.000−80,000)−33,650 = $1,350). The remaining $4,493 ($5,843−1,350) of the housing cost amount deduction carried over from taxable year 1982 may not be deducted in 1983 or carried over to 1984.
D is a U.S. citizen and a calendar year and cash basis taxpayer. D is a bona fide resident of and maintains his tax home in foreign country J for all of taxable year 1984. In 1984, D earns $80,000 of foreign earned income, $60,000 of which is an employer provided amount and $20,000 of which is a non-employer provided amount. D's total housing cost amount for 1984 is $25,000. D elects to exclude, under section 911(a)(2), the portion of his housing cost amount that is attributable to employer provided amounts. D's excludable housing cost amount is $18,750; that is the total housing cost amount ($25,000) multiplied by employer provided amounts for the taxable year ($60,000) over foreign earned income for the taxable year ($80,000). D also elects to exclude his foreign earned income under § 1.911-3(d)(1). D's section 911(a)(1) limitation for 1984 is $61,250 (the lesser of $80,000−$18,750 or $80,000 × 366/366). D's total exclusion for 1984 under section 911(a)(1) and (2) is $80,000. D cannot claim a housing cost amount deduction in 1984 because D has no foreign earned income in excess of his foreign earned income and housing cost amount excluded from gross income for the taxable year under § 1.911-3 and this section. D may carry over his housing cost amount deduction of $6,250, the total housing cost amount less the portion attributable to employer provided amounts ($25,000−18,750), to taxable year 1985.
(Sec. 911 (95 Stat. 194; 26 U.S.C. 911) and sec. 7805 (68A Stat. 917; 26 U.S.C. 7805) of the Internal Revenue Code of 1954)
[T.D. 8006, 50 FR 2970, Jan. 23, 1985]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 7701 Definitions
- § 912 Exemption for certain allowances
- § 163 Interest
- § 216 Deduction of taxes, interest, and business depreciation by cooperative housing corporation tenant-stockholder
- § 119 Meals or lodging furnished for the convenience of the employer
- § 217 Moving expenses
- § 911 Citizens or residents of the United States living abroad
- § 7805 Rules and regulations
Regulations it cites
- § 1.911-2 Qualified individuals.
- § 1.911-3 Determination of amount of foreign earned income to be excluded.
Cited by 4 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 8006 (50 FR 2970)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Earned Income of Citizens or Residents of United States
Nearby sections
- § 1.909-6 Pre-2011 foreign tax credit splitting events.
- § 1.911-1 Partial exclusion for earned income from sources within a foreign country and foreign housing costs.
- § 1.911-2 Qualified individuals.
- § 1.911-3 Determination of amount of foreign earned income to be excluded.
- § 1.911-4 Determination of housing cost amount eligible for exclusion or deduction.
- § 1.911-5 Special rules for married couples.
- § 1.911-6 Disallowance of deductions, exclusions, and credits.
- § 1.911-7 Procedural rules.
- § 1.911-8 Former deduction for certain expenses of living abroad.