
Treasury Regulations · 26 CFR
§ 1.911-6. Disallowance of deductions, exclusions, and credits.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 911
Cite as 26 CFR § 1.911-6
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- January 23, 1985 by T.D. 8006
- Issued under
- 26 U.S.C. § 911
- Length
- 3,639 words · about 16 min to read
- Defines
- 1 term
- Cross-references
- cites 4 Code sections and 5 regulations; cited by 3
Any amount included in income under paragraph (b)(4)(ii) of this section is not foreign earned income.
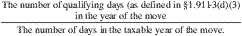
The portion of the moving expense deduction treated as attributable to the year succeeding or preceding the move shall be determined by subtracting the portion of the moving expense deduction that is attributable to the year of the move from the total moving expense deduction. The allocation of a portion of the moving expense deduction to a succeeding or preceding taxable year does not affect the time for claiming the allowable moving expense deduction. The portion of the moving expense deduction that is disallowed shall be determined by multiplying the moving expense deduction attributable to the year of the move or the succeeding or preceding year, as the case may be, by a fraction the numerator of which is amounts excluded under section 911(a) for that year and the denominator of which is foreign earned income for that year.
In 1982 A, an architect, operates his business as a sole proprietorship in which capital is not a material income producing factor. A receives $1,000,000 in gross receipts, all of which is foreign source earned income, and incurs $500,000 of otherwise deductible business expenses definitely related to the foreign earned income. A elects to exclude $75,000 under section 911(a)(1). The expenses must be apportioned to excluded earned income as follows: $500,000 × $75,000/1,000,000. Thus, $37,500 of the business expenses are not deductible.
The facts are the same as in example 1, except that $100,000 of A's gross receipts is U.S. source earned income and $68,000 of A's business expenses are attributable to the U.S. source earned income. Thus, A has $900,000 of foreign earned income and $432,000 of deductions allocated to foreign earned income. The expenses apportioned to excluded earned income are $432,000 × $75,000/$900,000, or $36,000, which are not deductible.
B is a U.S. citizen, calendar year and cash basis taxpayer. B moves to foreign country N and maintains a tax home and is physically present there from July 1, 1984 through May 26, 1985. Among other possible periods, B is a qualified individual for 219 days in the year of the move. B pays $6,000 of otherwise deductible moving expenses in 1984. For 1984, B's foreign earned income is $60,000 and B excludes $47,869 ($80,000 × 219/366) under section 911(a). Under paragraph (b)(2) of this section, B's moving expenses are attributable to services performed in 1984. Under paragraph (b)(3) of this section, $6,000 × $47,869/$60,000, or $4,789, of B's moving expense deduction is disallowed. B may deduct $1,211 of moving expenses on his 1984 return.
The facts are the same as in example 3 except that B maintains a tax home and is physically present in foreign country N from October 9, 1984 through September 3, 1985. Among other possible periods, B is a qualified individual for no more than 119 days in 1984 and 281 days in 1985. B's foreign earned income for 1984 is $60,000. B's foreign earned income for 1985 is $150,000. Because B is a qualified individual for less than 120 days in the year of the move, under paragraph (b)(2) of this section, B's moving expenses are attributable to services performed in 1984 and 1985. At the close of 1984, B may either seek an extension of time to file under § 1.911-7(c) or may file an income tax return without claiming the exclusions or deduction under section 911. B does not seek an extension and files without excluding foreign earned income; thus B may deduct his moving expenses in full. B later amends his 1984 return and excludes foreign earned income for that year. B excludes foreign earned income for 1985. B must determine the portion of the moving expense deduction that is disallowed. The portion of the moving expense deduction that is disallowed is determined by multiplying the otherwise allowable moving expense deduction by a fraction. The numerator of the fraction is the sum of amounts excluded under section 911(a) for 1984 and 1985, that is $26,082 or $80,000 × 119/365, plus $61,589, or $80,000 × 281/365, which totals $87,671. The denominator of the fraction is the sum of foreign earned income for 1984 and 1985, that is $60,000 plus $150,000, or $210,000. B's allowable moving expense deduction is $3,495, or $6,000−($6,000 × $87,671/$210,000). If B does not file an amended 1984 return (and does not exclude foreign earned income for 1984), but excludes foreign earned income under section 911(a) for 1985, a portion of his moving expense deduction is disallowed, based on the same formula. The amount disallowed is $6,000 × $61,589/$210,000, or $1,760. This amount may be recaptured either by filing an amended return for 1984 or by including it in income for 1985 (in which case it is not foreign earned income).
C is a U.S. citizen, a self-employed individual, and a cash basis and calendar year taxpayer. For the entire 1982 taxable year C maintained his tax home and his bona fide residence in foreign country P. During 1982 C earned and received $120,000 of foreign earned income, none of which was attributable to employer provided amounts. C paid $40,000 of business expenses. C elected to exclude foreign earned income under section 911(a)(1) and claimed a housing cost amount deduction of $15,000. C received $10,000 of foreign source interest income which was included with C's earned income in a single tax base and taxed at graduated rates. For 1982, C paid $30,000 in income tax to foreign country P. The amount of C's business expenses that is properly apportioned to excluded amounts (and therefore, not deductible) equals $25,000, which is determined by multiplying the otherwise allowable deductions by C's excluded amounts over C's foreign earned income ($40,000 × 75,000/120,000). The amount of country P tax that is properly apportioned to excluded amounts (and therefore, not deductible or creditable) equals $20,000, which is determined by multiplying the tax of $30,000 by the following fraction:
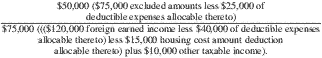
D is a U.S. citizen and an accrual basis and calendar year taxpayer for U.S. tax purposes. For the entire period from January 1, 1982 through December 31, 1983, D maintains his tax home and his bona fide residence in foreign country R. For purposes of R's income tax, D is a cash basis taxpayer and uses a fiscal year that begins on April 1 and ends on the following March 31. During his entire period of residence in R, D receives foreign earned income of $10,000 each month, all of which is attributable to employer provided amounts. For his foreign taxable year ending March 31, 1982, D pays $10,000 of income tax to R. For his foreign taxable year ending March 31, 1983, D pays $54,000 of income tax to R. Under paragraph (c)(2)(ii) of this section, all of the $10,000 of tax paid for this foreign taxable year ending March 31, 1982 is imposed on foreign earned income received in 1982, as is $40,500, or 9/12 × $54,000, of tax paid for his foreign taxable year ending March 31, 1983. (D received $10,000 per month for the last 3 months of his foreign taxable year ending March 31, 1982, all of which are within his U.S. taxable year ending December 31, 1982 under paragraph (c)(2)(i) of this section, and $10,000 per month for each month of his foreign taxable year ending March 31, 1983, of which the first 9 months are within his U.S. taxable year ending December 31, 1982. Under paragraph (c)(2)(ii) of this section, foreign taxes are deemed to accrue on a pro rata basis to income as it is received or accrued. Thus, all of the $10,000 of foreign taxes imposed on the income received during D's foreign taxable year ending March 31, 1982 accrue to D's 1982 foreign earned income, as do 9/12 (or $90,000/120,000) of foreign taxes imposed on income received during D's foreign taxable year ending March 31, 1983, for purposes of determining the amount of D's foreign taxes that is disallowed.) For 1982, D has no deductible expenses, and elects to exclude his housing cost amount of $21,000 under section 911(a)(2) and foreign earned income of $75,000 under section 911(a)(1). The amount of D's foreign taxes disallowed for deduction or credit purposes for 1982 is $8,000 (that is, $10,000 × $96,000/$120,000) of the taxes for his foreign taxable year ending March 31, 1982, plus $32,400 (that is, $40,500 × $96,000/$120,000) of the taxes for his foreign taxable year ending March 31, 1983, or $40,400. From 1982, D has $2,000 ($10,000−$8,000) of deductible or creditable taxes accrued on March 31, 1982, and $8,100 ($40,500-$32,400) of deductible or creditable taxes accrued on March 31, 1983, after the disallowance based on his 1982 excluded income.
E is a United States citizen, calendar year and cash basis taxpayer. E is physically present in and establishes his tax home in foreign country S on May 1, 1981. For purposes of country S, E's taxable year begins on April 1 and ends the following March 31. E receives foreign earned income of $15,000 each month beginning on May 1, 1981. At the end of his foreign taxable year ending on March 31, 1982, E pays $70,000 of income tax to S on $165,000 of foreign earned income. Under section 911, as in effect for taxable years beginning before January 1, 1982, E may not exclude any income that is earned or received during 1981. None of E's taxes paid in 1982 that are attributable to income earned or received in 1981 are subject to disallowance because, under paragraph (c)(2)(ii) of this section, the only taxes disallowed are those deemed to accrue on income earned and received after December 31, 1981, and excluded from gross income. The amount of E's taxes paid in 1982 that are attributable to 1981 is $50,909, or $70,000 × $120,000/$165,000. E elects to exclude foreign earned income for 1982. The amount of E's taxes paid to S in 1982 that accrue to 1982 foreign earned income, and are therefore subject to disallowance based on excluded income, is $19,091, or $70,000 × $45,000/$165,000.
(Sec. 911 (95 Stat. 194; 26 U.S.C. 911) and sec. 7805 (68A Stat. 917; 26 U.S.C. 7805) of the Internal Revenue Code of 1954)
[T.D. 8006, 50 FR 2973, Jan. 23, 1985]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 911 Citizens or residents of the United States living abroad
- § 219 Retirement savings
- § 217 Moving expenses
- § 7805 Rules and regulations
Regulations it cites
- § 1.861-8 Computation of taxable income from sources within the United States and from other sources and activities.
- § 1.911-4 Determination of housing cost amount eligible for exclusion or deduction.
- § 1.911-3 Determination of amount of foreign earned income to be excluded.
- § 1.911-2 Qualified individuals.
- § 1.911-7 Procedural rules.
Cited by 3 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 8006 (50 FR 2973)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Earned Income of Citizens or Residents of United States
Nearby sections
- § 1.911-2 Qualified individuals.
- § 1.911-3 Determination of amount of foreign earned income to be excluded.
- § 1.911-4 Determination of housing cost amount eligible for exclusion or deduction.
- § 1.911-5 Special rules for married couples.
- § 1.911-6 Disallowance of deductions, exclusions, and credits.
- § 1.911-7 Procedural rules.
- § 1.911-8 Former deduction for certain expenses of living abroad.