
Treasury Regulations · 26 CFR
§ 1.936-6. Intangible property income when an election out is made: Cost sharing and profit split options; covered intangibles.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 936
Cite as 26 CFR § 1.936-6
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- June 13, 1986 by T.D. 8090
- Last amended
- October 14, 1998 by T.D. 8786
- Issued under
- 26 U.S.C. § 936
- Length
- 15,468 words · about 67 min to read
- Defines
- 7 terms
- Cross-references
- cites 9 Code sections and 8 regulations; cited by 2
The rules in this section apply for purposes of section 936(h) and also for purposes of section 934(e) where applicable.
Q. 1: Cost sharing payments are based on research undertaken by the affiliated group in the “product area” which includes the possession product. The term “product area” is defined by reference to the three-digit classification under the Standard Industrial Classification (SIC) code. Which governmental agency has jurisdiction to decide the proper SIC category for any specfic product?
A. 1: Solely for the purpose of determining the tax consequences of operating in a possession, the Secretary or his delegate has exclusive jurisdiction to decide the proper SIC category under which a product is classified. For this purpose, the product area under which a product is classified will be determined according to the 1972 edition of the SIC code. From time to time and in appropriate cases, the Secretary may prescribe regulations or issue rulings determining the proper SIC category under which a particular product is to be classified, and may prescribe regulations for aggregating two or more three-digit classifications of the SIC code and for classifying product areas according to a system other than under the SIC code.
Q. 2: How is the term “affiliated group” defined for purposes of the cost sharing option?
A. 2: For purposes of the cost sharing option, the term “affiliated group” means the possessions corporation and all other organizations, trades or businesses (whether or not incorporated, whether or not organized in the United States, and whether or not affiliated) owned or controlled directly or indirectly by the same interests, within the meaning of section 482.
Q. 3: Are research and development expenditures that are included in product area research limited to research and development expenditures that are deductible under section 174 or that are incurred by U.S. affiliates?
A. 3: No, product area research is not limited to product area research expenditures deductible under section 174 or to expenses incurred by U.S. affiliates. Product area research also includes deductions permitted under section 168 with respect to research property which are not deductible under section 174; qualified research expenses within the meaning of section 30(b); payments (such as royalities) for the use of, or right to use, a patent, invention, formula, process, design, pattern or know-how; and a proper allowance for amounts incurred in the acquisition of manufacturing intangible property. In the case of an acquisition of depreciable or amortizable manufacturing intangible property, the annual amount of product area research shall be be equal to the allowable depreciation or amortization on the intangible property for the taxable year. In the case of an acquisition of nondepreciable or nonamortizable manufacturing intangible property, the amount expended for the acquisition shall be deemed to be amortized over a five year period and included in product area research in the year of the deemed amortization. Any contingent payment made with respect to the acquisition of nonamortizable manufacturing intangible property shall be treated as amounts incurred in the acquisition of nonamortizable manufacturing intangible property when paid or accrued.
Q. 4: Does royalty income from a person outside the affiliated group with respect to the manufacturing intangibles within a product area reduce the product area research pool within the same product area?
A. 4: Yes.
Q. 5: Does income received from a person outside the affiliated group from the sale of a manufacturing intangible reduce the product area research pool within the same product area?
A. 5: In determining product area research, the income from the sale attributable to noncontingent payments will reduce product area research ratably over the remaining useful life of the property in the case of an amortizable intangible and ratably over a 5-year period in the case of a nonamortizable intangible. Any income attributable to contingent amounts received with respect to the sale of manufacturing intangible property shall be treated as amounts received from the sale of the manufacturing intangible property in the year in which such contingent amounts are received or accrued.
Q. 6: If a member of an affiliated group incurs research and development expenses pursuant to a contract with an unrelated person who is entitled to exclusive ownership of all the technology resulting from the expenditures, is the amount of product area research reduced by the amount of such expenditures?
A. 6: To the extent that the product area research expenditures can be allocated solely to the technology produced for the unrelated person, such expenditures will not be included in product area research expenditures provided, however, that the unrelated person has exclusive ownership of all the technology resulting from these expenditures, and further that no member of the affiliated group has a right to use any of the technology.
Q. 7: What is the treatment of product area research expenditures attributable to a component where the component and the integrated product fall within different product areas?
A. 7: For purposes of the computation of product area research expenditures in the product area by the affiliated group, the product area in which the component falls is aggregated with the product area in which the integrated product falls. However, if the component product and integrated product are in separate SIC codes and if the component product is not included in the definition of the possession product, then the product area research expenditures are not aggregated. The same rule applies where the taxpayer elects a component product which encompasses another component product and the two component products fall into separate SIC codes. In such case, the product area in which the first component falls is aggregated with the product area in which the second component falls.
Q. 1: The cost sharing payment is the same proportion of the total cost of product area research which the amount of “possession sales” of the affiliated group bears to the “total sales” of the affiliated group within the product area. How are “possession sales” defined for purposes of the cost sharing fraction?
A. 1: The term “possession sales” means the aggregate sales or other dispositions of the possession product, to persons who are not members of the affiliated group, less returns and allowances and less indirect taxes imposed on the production of the product, for the taxable year. Except as otherwise indicated in § 1.936-6(a)(2), the sales price to be used is the sales price received by the affiliated group from persons who are not members of the affiliated group.
Q. 2: For purposes of the numerator of the cost sharing fraction, how are possession sales computed where the possession product is a component product or an end-product form?
A. 2: (i) The sales price of the component product or end-product form is determined as follows. With respect to a component product, an independent sales price from comparable uncontrolled transactions must be used if such price can be determined in accordance with § 1.482-2(e)(2). If an independent sales price of the component product from comparable uncontrolled transactions cannot be determined, then the sales price of the component product shall be deemed to be equal to the transfer price, determined under the appropriate section 482 method, which the possessions corporation uses under the cost sharing method in computing the income it derives from the active conduct of a trade or business in the possession with respect to the component product. The possessions corporation in lieu of using the transfer price determined under the preceding sentence may treat the sales price for the component product as equal to the same proportion of the third party sales price of the integrated product which the production costs attributable to the component product bear to the total production cost for the integrated product. Production cost will be the sum of direct and indirect production costs as defined in § 1.936-5(b)(4). If the possessions corporation determines the sales price of the component product using the production cost ratio, the transfer price used by the possessions corporation in computing its income from the component product under the cost sharing method may not be greater than such sales price.
Q. 3: For purposes of determining possessions sales in the numerator of the cost sharing fraction, will the replacement part price of the product be treated as a price from comparable uncontrolled transactions?
A. 3: Prices for replacement parts are generally higher than prices for equipment sold as part of an original system. Thus, prices for replacement parts cannot generally be used directly as prices for comparable uncontrolled transactions. However, replacement part prices may be used for estimating comparable uncontrolled prices where the price differential can be reasonably determined and taken into account under § 1.482-2(e)(2).
Q. 4: For purposes of determining possession sales in the cost sharing fraction, what is the treatment of components that are purchased by one possessions corporation from an affiliated possessions corporation and which are incorporated into a possession product where the transferor possessions corporation treats the transferred component as a possession product?
A. 4: When one possessions corporation purchases components from a second possessions corporation which is an affiliated corporation, the purchase price of the components paid to the second possessions corporation shall be subtracted from the sales proceeds of the product produced in the possession by the first possessions corporation, and only the remainder is included in the numerator of the cost sharing formula for the first corporation. For example, assume that N corporation manufactures a component for sale to O corporation for $100 (a price which reflects prices in comparable uncontrolled transactions). Both N and O are affiliated possessions corporations. N has designated that component product as its possession product. O then incorporates that product into a second product which is sold to customers for $300 N and O must make separate cost sharing payments. The cost sharing payment of N corporation is determined by including $100 as possession sales, and the payment of O is determined by subtracting that $100 purchase price from the $300 received from customers. Thus, the possessions sales amount of O is $200. This rule is intended to prevent the double counting of the sales of a component produced by one possessions corporation and incorporated into another product by an affiliated possessions corporation.
Q. 5: Are pre-TEFRA sales included in the cost sharing fraction?
A. 5: No. Pre-TEFRA sales are sales of products produced by the possessions corporation and transferred to an affiliate prior to a possessions corporation's first taxable year beginning after December 31, 1982. Pre-TEFRA sales are not included in either the numerator or denominator of the cost sharing fraction. If the U.S. affiliate uses the FIFO method of costing inventory, the pre-TEFRA inventory will be treated as the first inventory sold by the U.S. affiliate during the first year in which section 936(h) applies. If the U.S. affiliate uses the LIFO method of costing inventory (either dollar-value or specific goods LIFO), pre-TEFRA inventor will be treated as inventory sold by the U.S. affiliate in the year in which the U.S. afiliate's LIFO layer containing pre-TEFRA LIFO inventory is liquidated.
Q. 6: How are “possession sales” determined under the cost sharing formula if members of the affiliated group (other than the possessions corporation) include purchases of the possession product, X, in a dollar-value LIFO inventory pool (as provided under § 1.472-8)?
A. 6: Possession sales may be determined by applying the revenue identification method provided under paragraph (b)(1) Question and Answer 18 of this section.
Q. 7: Do possession sales include excise taxes paid by the possessions corporation when the product is sold for ultimate use or consumption in the possession?
A. 7: No. The amount of excise taxes is excluded from both the numerator and denominator of the cost sharing fraction.
Q. 8: How are “total sales” defined for purposes of the cost sharing fraction?
A. 8: The term “total sales” means aggregate sales or other dispositions of products in the same product area as the possession product, less returns and allowances and less indirect taxes imposed on the production of the product, for the taxable year to persons who are not members of the affiliated group. The sales price to be used is the sales price received by the affiliated group from persons who are not members of the affiliated group.
Q. 9: In computing that cost sharing payment, how are “total sales” computed if the dollar-value LIFO inventory pool includes some products which are not included in the product area (determined under the 3-digit SIC code) on which the denominator of the cost sharing fraction is based?
A. 9: In such case, the amount of the total sales within the product area to persons who are not members of the affiliated group by persons who are members of the affiliated group is determined by multiplying the total sales of the products within the dollar-value LIFO inventory pool by a fraction. The numerator of the fraction includes the dollar-value of purchases by members of the affiliated group (including the possessions corporation) of products within the product area made during the year, plus any added production costs (as defined in § 1.471-11(b), (c), and (d) but not including the costs of materials) incurred by the affiliates during the same period. The denominator of the fraction includes the dollar-value of purchases by members of the affiliated group (including the possessions corporation) of products within the dollar-value LIFO inventory pool made during the same period (including any production costs, as described above, incurred by the affiliate during the same period). For these purposes, purchases of a possession product are determined on the basis of the possessions corporation's cost for its inventory purposes.
Q. 10: May a possessions corporation compute its income under the cost sharing method with respect to a possession product which the possessions corporation sells to a member of its affiliated group and which that member then leases to an unrelated person or uses in its own trade or business?
A. 10: Yes, provided that an independent sales price for the possession product from comparable uncontrolled transactions can be determined in accordance with § 1.482-2(e)(2), and, provided further, that such member complies with the requirements of § 1.936-6(a)(2), question and answer 14. If, however, there is a comparable uncontrolled price for an integrated product and the possession product is a component product or end-product form thereof, the possessions corporation may, if such member complies with the requirements of § 1.936-6(a)(2), question and answer 14, compute its income under the cost sharing method with respect to such possession product. In that case, the cost sharing payment shall be computed under the following question and answer.
Q. 11: How are possession sales and total sales to be determined for purposes of computing the cost sharing payment with respect to a possession product which the possessions corporation sells to a member of its affiliated group where that member then leases the possession product to unrelated persons or uses it in its own trade or business?
A. 11: If the possessions corporation is entitled to compute its income from such sales of the possession product under the cost sharing method, both possession sales and total sales shall be determined as if the possession product had been sold by the affiliate to an unrelated person at the time the possession product was first leased or otherwise placed in service by the affiliate. The sales price on such deemed sale shall be equal to the independent sales price from comparable uncontrolled transactions determined in accordance with § 1.482-2(e)(2), if any. If the possession product is a component product or an end-product form for which there is no such independent sales price but there is a comparable uncontrolled price for the integrated product which includes the possession product, the deemed sales price of the possession product shall be computed under the rules of § 1.936-6(a)(2) question and answer 2. The full amount of income received under the lease shall be treated as income of (and taxed to) the affiliate and not the possessions corporation.
Q. 12: When may a possessions corporation take into account in computing total sales under the cost sharing method products in the same product area as the possession product (other than the possession product itself) where such products are leased by members of the affiliated group to unrelated persons or used by any such member in its own trade or business?
A. 12: For purposes of computing total sales under the cost sharing method, the possessions corporation may take into account products in the same product area as the possession product itself where such products are leased by members of the affiliated group to unrelated persons or used in the trade or business of any such member, but only if an independent sales price of such products from comparable uncontrolled transactions may be determined under § 1.482-2(e)(2). In such cases, the units of such products which are leased or otherwise used internally by members of the affiliated group may be treated as sold to unrelated persons for such independent sales price for purposes of computing total sales.
Q. 13: Assuming that a possessions corporation is entitled to compute its income under the cost sharing method with respect to sales of a possession product to affiliates in cases where those affiliates lease units of the possession product to unrelated persons or use them internally, is the possessions corporation's income from the possession product any different than if the affiliates had sold the product to unrelated parties?
A. 13: No.
Q. 14: If a possessions corporation sells units of a possession product to a member of its affiliated group and that affiliate then leases those units to an unrelated person or uses the units in its own trade or business, what requirements must the affilate meet in order for the possessions corporation to be entitled to the benefits of the cost sharing method with respect to such units?
A. 14: (i) For taxable years of the possessions corporation beginning on or before June 13, 1986, the affiliate need not meet any special requirements in order for the possessions corporation to be entitled to the beneifts of the cost sharing method with respect to such units. Thus, the affiliate's basis in such units shall be equal to the transfer price used for computing the possessions corporation's gross income with respect to such units under section 936(h)(5)(C)(i)(II), and the income derived by the affiliate from such lease or internal use shall be reported by the affiliate when and to the extent actually derived. The affiliate shall not be deemed to have sold such units to an unrelated party at the time they were first leased or otherwise placed in service for any purpose other than the computation of possession sales and total sales. A similar rule applies to other products in the same product area as the possession product which are sold by any member in its own trade or business and which the possessions corporation takes into account in computing total sales under the cost sharing method.
For treatment of other products in the same product area as the possession product see § 1.936-6(a)(2), question and answer 12.
Possessions corporation S and its affiliate A are calendar year taxpayers. In 1985, S manufactures 100 units of possession product X. S sells 50 units of X to unrelated persons in arm's length transactions for $10 per unit. In applying the cost sharing method to determine the portion of its gross income from such sales which qualifies for the possessions tax credit, S determines that $8 of the $10 sales price may be taken into account. S sells the remaining 50 units of X to A, and A then leases such units to unrelated persons. In 1985, A also manufacturers 100 units of product Y, the only other product in the same product area as X manufactured or sold by any member of the affiliated group. A manufactured the 100 units of Y at a cost of $15 per unit, sold 50 units of Y to unrelated persons in arm's length transactions for $20 per unit, and leased the remaining 50 units of Y to unrelated persons.
S may compute its income under the cost sharing method with respect to the 50 units of X it sold to A because S can determine an independent sales price of X from comparable uncontrolled transactions under § 1.482-2(e)(2). For purposes of computing both possessions sales and total sales, the 50 units of X sold to A will be deemed to have been sold by A to an unrelated person for $10 per unit. The income of S qualifying for the possessions tax credit from the sale of those 50 units of X to A, and A's basis in those units, will both be determined using the $8 transfer price determined under section 936 (h)(5)(C)(i)(II). For purposes of computing total sales in the denominator of the cost sharing fraction, S may also take into account the 50 units of Y leased by A to unrelated persons, as if A had sold those units for $20 per unit. A's basis in those units of Y will continue to be its actual cost basis of $15 per unit.
If all of the above transactions had occurred in 1987, S would be entitled to compute its income under the cost sharing method with respect to the 50 units of X it sold to A only if A agreed to be treated for all tax purposes as if it had sold such units for $10 per unit, realized income on such deemed sale of $2 per unit, repurchased such units immediately for $10 per unit, and then leased such units, which would then have a $10 per unit basis in A's hands. For purposes of computing total sales, S would be entitled to take into account the 50 units of X leased by A to unrelated persons as if A had sold such units for $20 per unit.
Q. 1: Is the cost of product area research paid or accrued by the possessions corporation in a taxable year creditable against the cost sharing payment?
A. 1: Yes, if the cost of the product area research is paid or accrued solely by the possessions corporation. Thus, payments by the possessions corporation under cost sharing arrangements with, or royalties paid to, unrelated persons are so creditable. Amounts (such as royalties) paid directly or indirectly to, or on behalf of, related persons and amounts paid under any cost sharing agreements with related persons are not creditable against the cost sharing payment.
Q. 2: Do royalties or other payments made by an affiliate of the possessions corporation to another member of the affiliated group reduce the cost sharing payment if such royalties or other payments are based, in part, on activity of the possessions corporation?
A. 2: No. Payments made between affiliated corporations do not reduce the cost sharing payment. Thus, for example, if a possessions corporation sells a component to a foreign affiliate for incorporation by the foreign affiliate into an integrated product sold to unrelated persons, and the foreign affiliate pays a royalty to the U.S. parent of the possessions corporation based on the total value of the integrated product, the cost sharing payment of the possessions corporation is not reduced.
Q. 1: S is a possessions corporation engaged in the manufacture and sale of four products (A, B, C, and D) all of which are classified under the same three-digit SIC code. S sells its production to a U.S. affiliate, P, which resells it to unrelated parties in the United States. P's third party sales of each of these products produced in whole or in part by S (computed as provided under paragraph (a)(2) of § 1.936-6) are $1 million or a total of $4 million for A, B, C, and D. P's other sales of products in the same SIC code are $3,000,000; and the defined worldwide product area research of the affiliated group is $350,000. How should S compute the cost sharing amount for products A, B, C, and D?
A. 1: The cost sharing amount is computed separately for each product on Schedule P of Form 5735. S should use the following formula for each of the products A, B, C, and D:
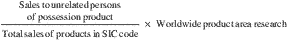
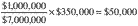
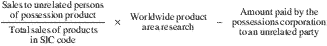
Q. 2: The facts are the same as in question 1 except that S manufactures product D under a license from an unrelated person. S pays the unrelated party an annual license fee of $20,000. Thus, the worldwide product area research expense of the affiliated group is $370,000. How should the cost sharing payment be adjusted?
A. 2: The cost sharing fee should be reduced by the $20,000 license fee made as a direct annual payment to a third party on account of product D. The cost sharing payment with respect to product D in this example will be adjusted as follows:
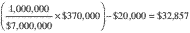
Q. 3: The facts are the same as in question 1 except that S also manufactures and exports product E to a foreign affiliate, which resells it to unrelated persons for $1 million. S makes a separate election for its export sales. How should S compute the cost sharing amount for product E?
A. 3: The numerator of the cost sharing fraction is the aggregate sales or other dispositions by members of the affiliated group of the units of product E produced in whole or in part in the possession to persons who are not members of the affiliated group. The cost sharing amount for product E would be computed as follows:
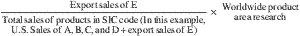
or
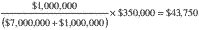
Q. 4: The facts are the same as in question 1, except that S also receives $10,000 in royalty income from unrelated persons for the licensing of certain manufacturing intangible property rights. What is the amount of the product area research that must be allocated in determining the cost sharing amount?
A. 4: If the affiliated group receives royalty income from unrelated persons with respect to manufacturing intangibles in the same product area, then the product area research to be considered shall be first reduced by such royalty income. In this case, the amount of product area research to be used in determining S's cost sharing payment should be reduced by the $10,000 royalty payment received to $340,000.
Q. 5: May a possessions corporation redetermine the amount of its required cost sharing payment after filing its tax return?
A. 5: If after filing its tax return, a possessions corporation files an amended return, or if an adjustment is made on audit, either of which affects the amount of the cost sharing payment required, then a redetermination of the cost sharing payment must be made. See, however, section 936(h)(5)(C)(i)(III)(a) with respect to the increase in the cost sharing payment due to interest imposed under section 6601(a).
Q. 1: What is the effect of the cost sharing method?
A. 1: The cost sharing payment reduces the amount of deductions (and the amount of reductions in earnings and profits) otherwise allowable to the U.S. affiliates (other than tax-exempt affiliates) within the affiliated group as determined under section 936(h)(5)(C)(i)(I)(b) which have incurred research expenditures (as defined in § 1.936-6(a)(1), question and answer (3) in the same product area for which the cost sharing option is elected, during the taxable year in which the cost sharing payment accrues. If there are no such U.S. affiliates, the reductions with respect to deductions and earnings and profits, as the case may be, are made with respect to foreign affiliates within the same affiliated group which have incurred product area research expenditures in such product area attributable to a U.S. trade or business. If there are no affiliates which have incurred research expenditures in such product area, the reductions are then made with respect to any other U.S. affiliate and, if there is no such U.S. affiliate, then to any other foreign affiliate. The allocations of these reductions in each case shall be made in proportion to the gross income of the affiliates. In the case of foreign affiliates, the allocation shall be made in proportion to gross income attributable to the U.S. trade or business or worldwide gross income, as the case may be. With respect to each group above, the reduction of deductions shall be applied first to deductions under section 174, then to deductions under section 162, and finally to any other deductions on a pro rata basis.
Q. 2: For purposes of estimated tax payments, when is the cost sharing amount deemed to accrue?
A. 2: The cost sharing amount is deemed to accrue to the appropriate affiliate on the last day of the taxable year of each such affiliate in which or with which the taxable year of the possessions corporation ends.
Q. 3: If the cost sharing method is elected and the year of accrual of the cost sharing payment to the appropriate affiliate (described in question and answer 1 of this paragraph (a)(5)) differs from the year of actual payment by the possessions corporation, in what year are the deductions of the recipients reduced?
A. 3: In the year the cost sharing payment has accrued.
Q. 4: What is the treatment of income from intangibles under the cost sharing method?
A. 4: Under the cost sharing method, a possessions corporation is treated as the owner, for purposes of obtaining a return thereon, of manufacturing intangibles related to a possession product. The term “manufacturing intangible” means any patent, invention, formula, process, design, pattern, or know-how. The possessions corporation will not be treated as the owner, for purposes of obtaining a return thereon, of any manufacturing intangibles related to a component product produced by an affiliated corporation and transferred to the possessions corporation for incorporation into the possession product, except in the case that the possession product is treated as including such component product for all purposes of section 936(h)(5). Further, the possessions corporation will not be treated as the owner, for purposes of obtaining a return thereon, of any marketing intangibles except “covered intangibles.” (See § 1.936-6(c).)
Q. 5: If the cost sharing option is elected, is it necessary for the possessions corporation to be the legal owner of the manufacturing intangibles related to the possession product in order for the possessions corporation to receive a full return with respect to such intangibles?
A. 5: No. There is no requirement that manufacturing intangibles be owned by the possessions corporation.
Q. 6: How is income attributable to marketing intangibles treated under the cost sharing method?
A. 6: Except in the case of “covered intangibles” (see § 1.936-6(c)), the possessions corporation is not treated as the owner of any marketing intangibles, and income attributable to marketing intangible of the possessions corporation will be allocated to the possessions corporation's U.S. shareholders with the proration of income based on shareholdings. If a shareholder of the possessions corporation is a foreign, person or is otherwise tax exempt, the possessions corporation is taxable on that shareholder's pro rata amount of the intangible property income. If the possessions corporation is a corporation any class of the stock of which is regularly traded on an established securities market, then the income attributable to marketing intangibles will be taxable to the possessions corporation rather than the corporation's U.S. shareholders.
Q. 7: What is the source of the intangible property income described in question and answer 6?
A. 7: The intangible property income is U.S. source whether taxed to the U.S. shareholder or taxed to the possessions corporation and section 863 (b) does not apply for this purpose. However, such intangible property income, if treated as income of the possessions corporation, does not enter into the calculation of the 80-percent possession source test or the 65-percent active trade or business test.
Q.7a: What is the source of the taxpayer's gross income derived from a sale in the United States of a possession product purchased by the taxpayer (or an affiliate) from a corporation that has an election in effect under section 936, if the income from such sale is taken into account to determine benefits under cost sharing for the section 936 corporation? Is the result different if the taxpayer (or an affiliate) derives gross income from a sale in the United States of an integrated product incorporating a possession product purchased by the taxpayer (or an affiliate) from the section 936 corporation, if the taxpayer (or an affiliate) processes the possession product or an excluded component in the United States?
A.7a: Under either scenario, the income is U.S. source, without regard to whether the possession product is a component, end-product, or integrated product. Section 863 does not apply in determining the source of the taxpayer's income. This Q&A 7a is applicable for taxable years beginning on or after November 13, 1998.
Q. 8: May marketing intangible income, if any, be allocated to the possessions corporation with respect to custom-made products?
A. 8: No. If the cost sharing option is elected, then income attributable to marketing intangibles (other than “covered intangibles” described in § 1.936-6(c)) will be taxed as discussed in questions and answers 6 and 7 of paragraph (a)(5) of this section. It is immaterial whether the product is custom-made.
Q. 9: In order to sell a pharmaceutical product in the United States, a New Drug Application (“NDA”) for the product must be approved by the U.S. Food and Drug Administration. Is an NDA considered a manufacturing or marketing intangible for purposes of the allocation of income under the cost sharing method?
A. 9: A manufacturing intangible.
Q. 10: Can a copyright be, in whole or in part, a manufacturing intangible for purposes of the allocation of income under the cost sharing method?
A. 10: In general, a copyright is a marketing intangible. See section 936(h)(3)(B)(ii). However, copyrights may be treated either as manufacturing intangibles or nonmanufacturing intangibles (or as partly each) depending upon the function or the use of the copyright. If the copyright is used in manufacturing, it will be treated as a manufacturing intangible; but if it is used in marketing, even if it is also classified as know-how, it will be treated as a marketing intangible.
Q. 11: If the cost sharing option is elected and a patent is related to the product produced by the possessions corporation, does the return to the possessions corporation with respect to the manufacturing intangible include the make, use, and sell elements of the patent?
A. 11: Yes. A patent confers an exclusive right for 17 years to sell a product covered by the patent. During this period, the return to the possessions corporation includes the make, use and sell elements of the patent.
Q. 12: For purposes of the cost sharing option, may a safe haven rule be applied to determine the amount of marketing intangible income?
A. 12: No. The amount of marketing intangible income is determined on the basis of all relevant facts and circumstances. The section 482 regulations will continue to apply except to the extent modified by the election. Rev. Proc. 63-10 and Rev. Proc. 68-22 do not apply for this purpose.
Q. 13: If a product covered by the cost sharing election is sold by a possessions corporation to an affiliated corporation for resale to an unrelated party, may the resale price method under section 482 be used to determine the intercompany price of the possessions corporation?
A. 13: In general, the resale price method may be used if (a) no comparable uncontrolled price for the product exists, and (b) the affiliated corporation does not add a substantial amount of value to the product by manufacturing or by the provision of services which are reflected in the sales price of the product to the customer. The possessions corporation will not be denied use of the resale price method for purposes of such inter-company pricing merely because the reseller adds more than an insubstantial amount to the value of the product by the use of intangible property.
Q. 14: If a possessions corporation makes the cost sharing election and uses the cost-plus method under section 482 to determine the arm's-length price of a possession product, will the cost base include the cost of materials which are subject to processing or which are components in the possession product?
A. 14: A taxpayer may include the cost of materials in the cost base if it is appropriate under the regulations under § 1.482-2(e)(4).
Q. 15: If the possessions corporation computes its income with respect to a product under the cost sharing method, and the price of the product is determined under the cost-plus method under section 482, does the cost base used in computing cost-plus under section 482 include the amount of the cost sharing payment?
A. 15: The amount of the cost sharing payment is included in the cost base. However, no profit with respect to the cost sharing payment will be allowed.
Q. 16: If a member of the affiliated group transfers to a possessions corporation a component which is incorporated into a possession product, how will the transfer price for the component be determined?
A. 16: The transfer price for the component will be determined under section 482, and as follows. If the possession product is treated as not including such component for purposes of section 936(h)(5), the transfer price paid for the component will include a return on all intangibles related to the component product. If the possession product is treated as including such component for purposes of section 936(h)(5), then the transfer price paid for the component by the possessions corporation will not include a return on any manufacturing intangible related to the component product, and the possessions corporation will obtain the return on the manufacturing intangibles associated with the component.
Q. 17: If the possessions corporation computes its income with respect to a product under the cost sharing method, with respect to which units of the product shall the possessions corporation be treated as owning intangible property as a result of having made the cost sharing election?
A. 17: The possessions corporation shall not be treated as owning intangible property, as a result of having made the cost sharing election, with respect to any units of a possession product which were not taken into account by the possessions corporation in applying the significant business presence test for the current taxable year or for any prior taxable year in which the possessions corporation also had a significant business presence in the possession with respect to such product.
Q. 1: In determining combined taxable income from sales of a possession product, how are the allocations and apportionments of expenses, losses, and other deductions to be determined?
A. 1: (i) Expenses, losses, and other deductions are to be allocated and apportioned on a “fully-loaded” basis under § 1.861-8 to the combined gross income of the possessions corporation and other members of the affiliated group (other than foreign affiliates). For purposes of the profit split option, the term “affiliated group” is defined the same as under § 1.936-6 (a)(1) question and answer 2. The amount of research, development, and experimental expenses allocated and apportioned to combined gross income is to be determined under § 1.861-8(e)(3). The amount of research, development and experimental expenses and related deductions (such as royalties paid or accrued with respect to manufacturing intangibles by the possessions corporation or other domestic members of the affiliated group to unrelated persons or to foreign affiliates) allocated and apportioned to combined gross income shall in no event be less than the amount of the cost sharing payment that would have been required under the rules set forth in section 936(h)(5)(C)(i)(II) and paragraph (a) of this section if the cost sharing option had been elected. Other expenses which are subject to § 1.861-8(e) are to be allocated and apportioned in accordance with that section. For example, interest expense (including payments made with respect to bonds issued by the Puerto Rican Industrial, Medical and Environmental Control Facilities Authority (AFICA)) is to be allocated and apportioned under § 1.861-8(e)(2). With the exception of marketing and distribution expenses discussed below, the other remaining expenses which are definitely related to a class of gross income shall be allocated to that class of gross income and shall be apportioned on the basis of any reasonable method, as described in § 1.861-8 (b)(3) and (c)(1). Examples of such methods may include, but are not limited to, those specified in § 1.861-8(c)(1)(i) through (vi).
Assume that possessions corporation A manufacturers prescription pharmaceutical product #1 for resale by P, its U.S. parent corporation, in the United States. Additionally, assume that P manufactures prescription pharmaceutical products #2 and #3 in the United States for sale there. Further, assume that all three products are within the same product area, and that marketing and distribution expenses are internally divided by P among the three products on the basis of time spent by sales persons of P on marketing of the three products, as follows:
| Product #1 | 50X |
| Product #2 | 80X |
| Product #3 | 110X |
| Total | 240X |
These expenses of 240X are allocated to gross income generated by all three products and shall be apportioned on the basis of gross sales or receipts of product #1 as compared to products #2 and #3 or another method which similarly reflects the factual relationship between these expenses and gross income derived from product #1 and products #2 and #3. Thus, if a sales method were used and sales of product #1 accounted for one-third of sales receipts from the three products, 80X (240 ÷ 3) of marketing and distribution expenses would be apportioned to the combined gross income from product #1.
Corporation B produces and sells Brand W whiskey, in the United States. B's subsidiary, S, which is a possessions corporation, produces soft drink extract in Puerto Rico which it sells to independent bottlers to produce Brand S soft drinks for sale in the United States. Corporation B's advertisements and other promotional materials for Brand W whiskey make no reference to Brand S soft drinks (or any other Corporation B products), and Brand S soft drink advertisements and other promotional materials make no reference to Brand W whiskey (or any other corporation B products). For purposes of section 936(h), the advertising and other promotional expenses for Brand W whiskey must be allocated entirely to the gross income from sales of Brand W whiskey and the advertising and other promotional expenses for Brand S soft drink must be allocated entirely to the gross income from the sales of soft drink extract, notwithstanding the fact that whiskey and soft drink extract are both included in SIC code 208. A similar result would apply, for example, to separately identifiable advertising and other marketing expenses which relate specifically and exclusively to one or the other of the following pairs of products: chewing gum and granulated sugar (SIC code 206); canned tuna fish and freeze-dried coffee (SIC code 209); children's underwear and ladies' brassieres (SIC code 234); aspirin tablets and prescription antibiotic tablets (SIC code 283); floor wax and perfume (SIC code 284); adhesives and inks (SIC code 289); semi-conductors and cathode-ray tubes (SIC code 367); batteries and extension cords (SIC code 369); bandages and dental supplies (SIC code 384); stainless steel flatware and jewelry parts (SIC code 391); children's toys and sporting goods (SIC code 394); hair curlers and zippers (SIC code 396); and paint brushes and linoleum tiles (SIC code 399).
Assume the same facts as in Example 1 and that possessions corporation A also manufactures aspirin, a non-prescription product, for resale by its U.S. parent corporation, P. Further, assume that the advertising and separately identifiable marketing expenses which relate specifically and exclusively to aspirin sales total $100 and that these expenses are allocable solely to gross income derived from aspirin sales. The sales method continues to be used to apportion the marketing and distribution expenses related, directly or indirectly, to products #1, #2, and #3, and the apportionment of such expenses to product #1 for purposes of determining combined taxable income from product #1 will remain as stated in Example 1. None of the advertising and other separately identifiable marketing expenses which relate specifically and exclusively to aspirin will be taken into account in allocating and apportioning the marketing and distribution expenses relating to the gross income attributable to products #1, #2, and #3. Gross income attributable to aspirin will be considered as a separate class of gross income, and all the advertising and separately identifiable marketing expenses which relate specifically and exclusively to aspirin sales of $100 will be allocated to the class of gross income derived from aspirin sales. Similarly, none of the marketing and distribution expenses, directly or indirectly, related solely to the group of products #1, #2, and #3 will be taken into account in determining the combined taxable income from aspirin sales. the remaining marketing and distribution expenses which do not, directly or indirectly, relate solely to any specific product or group of products (e.g., the salaries of a Vice-President of Marketing who has responsibility for marketing all products and his staff) shall be allocated and apportioned on the basis of the gross receipts from the sales of all of the products (or a similar method) in determining combined taxable income of any product.
Q. 2: How may the allocation and apportionment of expenses to combined gross income be verified?
A. 2: Substantiation of the allocation and apportionment of expenses will be required upon audit of the possessions corporation and affiliates. Detailed substantiation may be necessary, particularly where the entities are engaged in multiple lines of business involving distinct product areas. Sources of substantiation may include certified financial reports. Form 10-K's, annual reports, internal production reports, product line assembly work papers, and other relevant materials. In this regard, see § 1.861-8(f)(5).
Q. 3: Does section 936(h) override the moratorium provided by section 223 of the Economic Recovery Tax Act of 1981 and any subsequent similar moratorium?
A. 3: Yes. Thus, the allocation and apportionment of product area research described in question and answer 1 must be made without regard to the moratorium.
Q. 4: Is the cost of samples treated as a marketing expense?
A. 4: Yes. The cost of producing samples will be treated as a marketing expense and not as inventoriable costs for purposes of determining combined taxable income (and compliance with the significant business presence test). However, for taxable years beginning prior to January 1, 1986, the cost of producing samples may be treated as either a marketing expense or as inventoriable costs.
Q. 5: If a possessions corporation uses the profit split method to determine its taxable income from sales of a product, how does it determine its gross income for purposes of the 80-percent possession source test and the 65-percent active trade or business test of section 936(a)(2)?
A. 5: One-half of the deductions of the affiliated group (other than foreign affiliates) which are used in determining the combined taxable income from sales of the product are added to the portion of the combined taxable income allocated to the possessions corporation in order to determine the possessions corporation's gross income from sales of such product.
Q. 6: How will income from intangibles related to a possession product be treated under the profit split method?
A. 6: Combined taxable income of the possessions corporation and affiliates from the sale of the possession product will include income attributable to all intangibles, including both manufacturing and marketing intangibles, associated with the product.
Q. 7: Can a possessions corporation apply the profit split option to a possession product if no U.S. affiliates derive income from the sale of the possession product?
A. 7: Yes.
Q. 8: With respect to the factual situation discussed in question and answer 7 how is combined taxable income computed?
A. 8: The profit split option is applied to the taxable income of the possessions corporation from sales of the possession product to foreign affiliates and unrelated persons. Fifty percent of that income is allocated to the possessions corporation, and the remainder is allocated to the appropriate affiliates as described in question and answer 13 of this paragraph (b)(1).
Q. 9: May a possessions corporation compute its income under the profit split method with respect to units of a possession product which it sells to a U.S. affiliate if the U.S. affiliate leases such units to unrelated persons or to foreign affiliates or uses such units in its own trade or business?
A. 9: Yes, provided that an independent sales price for the possession product from comparable uncontrolled transactions can be determined in accordance with § 1.482-2 (e)(2). If, however, there is a comparable uncontrolled price for an integrated product and the possession product is a component product or end-product form thereof, the possessions corporation may compute its income under the profit split method with respect to such units. In either case, the possessions corporation shall compute combined taxable income with respect to such units under the following question and answer.
Q. 10: If the possessions corporation is entitled to use the profit split method in the situation described in Q. 9 (leasing units of the possession product or use of such units in the taxpayer's own trade or business), how should it compute combined taxable income with respect to such units?
A. 10: (i) Combined taxable income shall be computed as if the U.S. affiliate had sold the units to an unrelated person (or to a foreign affiliate) at the time the units were first leased or otherwise placed in service by the U.S. affiliate. The sales price on such deemed sale shall be equal to the independent sales price from comparable uncontrolled transactions determined in accordance with § 1.482-2(e)(2), if any.
Q. 11: In the situation described in question 9, how does the U.S. affiliate determine its basis in such units for purposes of computing depreciation and similar items?
A. 11: The U.S. affiliate shall be treated, for purposes of computing its basis in such units, as if it had repurchased such units immediately following the deemed sale and at the deemed sales price as provided in Q&A. 10 of this paragraph (b)(1).
The principles of questions and answers 10 and 11 are illustrated by the following example:
Possessions corporation S manufactures 100 units of possession product X. S sells 50 units of X to an unrelated person in an arm's length transaction for $10 per unit. S sells the remaining 50 units to its U.S. affiliate, A, which leases such units to unrelated persons. The combined taxable income for the 100 units of X is computed below on the basis of the given production, sales, and cost data:
| Sales: | |
| 1. Total sales by S to unrelated persons (50 × $10) | $500 |
| 2. Total deemed sales by A to unrelated persons (50 × $10) | 500 |
| 3. Total gross receipts (line 1 plus line 2) | 1,000 |
| Total costs: | |
| 4. Material costs | 200 |
| 5. Production costs | 300 |
| 6. Research expenses | 0 |
| 7. Other expenses | 100 |
| 8. Total (add lines 4 through 7) | 600 |
| Combined taxable income attributable to the 100 units of X: | |
| 9. Combined taxable income (line 3 minus line 8) | 400 |
| 10. Share of combined taxable income apportioned to S (50% of line 9) | 200 |
| 11. Share of combined taxable income apportioned to A (line 9 minus line 10) | 200 |
| A's basis in 50 units of X leased by it to unrelated persons: | |
| 12. 50 units times $10 deemed repurchase price | 500 |
Subsequent leasing income is entirely taxed to A.
Q. 12: If the possession product is a component product or an end-product form, how is the combined taxable income for such product to be determined?
A. 12: (i) Except as provided in paragraph (v) of this A. 12, combined taxable income for a component product or an end-product form is computed under the production cost ratio (PCR) method.
| Production costs (excluding costs of materials): | |
| 1. O's costs for the component | 100 |
| 2. S's costs for the microprocessors | 500 |
| 3. P's costs for the CPUs (the possession product) | 200 |
| 4. Q's costs for the computers | 400 |
| 5. Total production costs for the computer (Add lines 1 through 4) | 1,200 |
| 6. Combined production costs for the CPU (the possession product) (Add lines 1 through 3) | 800 |
| 7. Ratio of production costs for the CPUs (the possession product) to the production costs for the computer | 0.667 |
| Determination of combined taxable income for computers: | |
| Sales: | |
| 8. Total possession sales of computers to unrelated customers and foreign affiliates | 7,500 |
| Total costs of O, S, P, and Q incurred in production of a computer: | |
| 9. Production costs (enter from line 5) | 1,200 |
| 10. Material costs | 100 |
| 11. Total costs (line 9 plus line 10) | 1,300 |
| 12. Combined gross income from sale of computers (line 8 minus line 11) | 6,200 |
| Expenses of the affiliated group (other than foreign affiliates) allocable and apportionable to the computers or any component thereof under the rules of §§ 1.861-8 through 1.861-14T and 1.936-6 (b)(1), Q&A. 1: | |
| 13. Expenses (other than research expenses) | 980 |
| Research expenses of the affiliated group allocable and apportionable to the computers: | |
| 14. Total sales in the 3-digit SIC Code | 12,500 |
| 15. Possession sales of the computers (enter from line 8) | 7,500 |
| 16. Cost sharing fraction (divide line 15 by line 14) | 0.6 |
| 17. Research expenses incurred by the affiliated group in 3-digit SIC Code multiplied by 120 percent | 700 |
| 18. Cost sharing amount (multiply line 16 by line 17) | 420 |
| 19. Research of the affiliated group (other than foreign affiliates) allocable and apportionable under §§ 1.861-17 and 1.861-14T(e)(2) to the computers | 300 |
| 20. Enter the greater of line 18 or line 19 | 420 |
| Computation of combined taxable income of the computer and the CPU: | |
| 21. Combined taxable income attributable to the computer (line 12 minus line 13 and line 20) | 4,800 |
| 22. Combined taxable income attributable to CPUs (multiply line 21 by line 7) (production cost ratio) | 3,200 |
| 23. Share of combined taxable income apportioned to S (50 percent of line 22) | 1,600 |
| Share of combined taxable income apportioned to U.S. affiliate(s) of S: | |
| 24. Adjustments for research expenses (line 18 minus line 19 multiplied by line 7) | 80 |
| 25. Adjusted combined taxable income (line 22 plus line 24) | 3,280 |
| 26. Share of combined taxable income apportioned to affiliates of S (line 25 minus line 23) | 1,680 |
Q. 13: If the profit split option is elected, how is the portion of combined taxable income not allocated to the possessions corporation to be treated?
A. 13: (i) The income shall be allocated to affiliates in the following order, but no allocations will be made to affiliates described in a later category if there are any affiliates in a prior category—
Q. 14: What is the source of the portion of combined taxable income allocated to the possessions corporation?
A. 14: Income allocated to the possessions corporation shall be treated as possession source income and as derived from the active conduct of a trade or business within the possession.
Q. 15: How is the profit split option to be applied to properly account for costs incurred in a year with respect to products which are sold by the possessions corporation to a U.S. affiliate during such year, but are not resold by the U.S. affiliate to persons who are not members of the affiliated group or to foreign affiliates until a later year?
A. 15: The rules under § 1.994-1(c)(5) are to be applied. Incomplete transactions will not be taken into consideration in computing combined taxable income. Thus, for example, if in 1983, A, a possessions corporation, sells units of a product with a cost to A of $5000 to B corporation, its U.S. affiliate, which use the dollar-value LIFO method of costing inventory, and B sells units with a cost of $4000 (representing A's cost) to C corporation, a foreign affiliate, only $4000 of such costs shall be taken into consideration in computing the combined taxable income of the possessions corporation and U.S. affiliates for 1983. If a specific goods LIFO inventory method is used by B, the determination of whether A's goods remain in B's inventory shall be based on whether B's specific goods LIFO grouping has experienced an increment or decrement for the year on the specific LIFO cost of such units, rather than on an average unit cost of such units. If the FIFO method of costing inventory is used by B, transfers may be based on the cost of the specific units transferred or on the average unit production cost of the units transferred, but in each case a FIFO flow assumption shall be used to identify the units transferred. For a determination of which goods are sold by taxpayers using the LIFO method, see question and answer 19.
Q. 16: If a possessions corporation purchases materials from an affiliate and computes combined taxable income for a possession product which includes such materials, how are those materials to be treated in the possessions corporation's inventory?
A. 16: The cost of those materials is considered to be equal to the affiliate's cost using the affiliate's method of costing inventory.
Q. 17: If the possessions corporation uses the FIFO method of costing inventory and the U.S. affiliate uses the LIFO method of costing inventory, or vice versa, what method of costing inventory should be used in computing combined taxable income?
A. 17: The transferor corporation's method of costing inventory determines the cost of inventory for purposes of combined taxable income while the transferee corporation's method of costing inventory determines the flow. Assume, for example, that X corporation, a possessions corporation, using the FIFO method of costing inventory purchases materials from Y corporation, U.S. affiliate, also using the FIFO method. X corporation produces a product which it transfers to Z corporation, another U.S. affiliate using the LIFO method. Assume also that the final product satisfies the significant business presence test. Under the facts, the cost of the materials purchased by X from Y is Y's FIFO cost. The costs of the inventory transferred by X to Z are determined under X's FIFO method of accounting as is the flow of the inventory from X to Z. The costs added by Z are determined under Z's LIFO method of inventory, as is the flow of the inventory from Z to unrelated persons or foreign affiliates.
Q. 18: How are the costs of a possession product and the revenues derived from the sale of a possession product determined if the U.S. affiliate includes purchases of the possessions product in a dollar-value LIFO inventory pool (as provided under § 1.472-8)?
A. 18: The following method will be accepted in determining the revenues derived from the sale of a possession product and the costs of a possession product if the U.S. affiliate includes purchases of the possession product in a dollar-value LIFO inventory pool. The rules apply solely for the cost sharing and profit split options under section 936(h).
At the end of year 1, there are 600 units of combined items A and B which are to be allocated between A and B on the basis of annual purchases of A and B units during year 1. During year 1, 1,000 units of item A, a possession product, and 2,000 units of item B, a non-possession product, were purchased. Thus, the 600 units in year 1 ending inventory are allocated 200 (i.e. 1/3) to item A units and 400 (i.e. 2/3) to item B units based on the relative purchases of A (1,000) and B (2,000) in year 1. These units appear as beginning inventory in year 2.
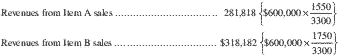
In year 2, 1,500 units of item A are purchased and 1,500 units of item B are purchased. However, 3,300 units of items A and B in the aggregate are sold for $600,000. The relative proportion of the $600,000 attributable to item A and to item B sales would be determined as follows:
| Year 2 sales | Item A | Item B |
|---|---|---|
| Unit sales from opening inventory | 200 | 400 |
| Unit sale from current-year purchases | 1,350 | 1,350 |
| Total unit sales (3,300) | 1,550 | 1,750 |
| Percentage | 47 | 53 |
| Year 2 Closing Inventory | Units |
|---|---|
| Item A | 150 |
| Item B | 150 |
Thus, revenues from Item A sales for purposes of computing possession sales for the cost sharing option and revenues for the profit split option are $281,818.
The number determined by this calculation is the LIFO cost of possession product sales from the taxpayer's LIFO pool.
Assume that item A is a possession product and item B is a non-possession product and also assume the inventory and purchases with respect to the LIFO pool as provided below:
| No. of units | Base-year cost/unit | Base-year cost | Percent | |
|---|---|---|---|---|
| Item A | 100 | $2.00 | $200 | 20 |
| Item B | 200 | 4.00 | 800 | 80 |
| Base-year cost | Index | LIFO cost | |
|---|---|---|---|
| Increment layer 2 | $300 | 3.0 | $900 |
| Increment layer 1 | 400 | 2.0 | 800 |
| Base layer | 300 | 1.0 | 300 |
| Pool total | $1,000 | $2,000 |
| Base-year cost | LIFO value | |
|---|---|---|
| Total pool | $1,000 | $2,000 |
| Item A | 200 | 400 |
| Item B | 800 | 1,600 |
| Total purchases | |
|---|---|
| Item A | $6,000 |
| Item B | 4,000 |
| No. of units | Base-year cost/unit | Base-year cost | Percent | |
|---|---|---|---|---|
| Item A | 200 | $2.00 | $400 | 50 |
| Item B | 100 | 4.00 | 400 | 50 |
| Base-year cost | Index | LIFO cost | |
|---|---|---|---|
| Increment layer 2 | $100 | 3.0 | $300 |
| Increment layer 1 | 400 | 2.0 | 800 |
| Base layer | $300 | 1.0 | 300 |
| Pool total | 800 | 1,400 | |
| The year 2 LIFO cost of possession product A sales will be calculated as follows: | |||
| (1) Base-year cost of item in year 2 ending inventory = $400 | |||
| (2) Percentage of item A base-year cost to total base-year cost ($400 ÷ $800) = 50% | |||
| (3) LIFO value of item A ($1,400 × 50%) = $700 | |||
| (4) LIFO cost of item A sales is determined by adding to the beginning inventory in year 2 the purchases of item A in year 2 and subtracting from this amount the ending inventory in year 2 ($400 + $6000 − $700 = $5700). The beginning inventory in year 2 is determined by multiplying the LIFO cost of the year 1 ending inventory by a percentage of item A base year cost to the total base-year cost in year 1. The ending inventory in year 2 is determined under (3) above. | |||
Q. 19: If a possession product is purchased from a possessions corporation by a U.S. affiliate using the dollar-value LIFO method of costing its inventory and is included in a LIFO pool of the U.S. affiliate which includes products purchased from the possessions corporation in pre-TEFRA years, how should the LIFO index computation of the U.S. affiliate be made in the first year in which section 936(h) applies and in subsequent taxable years?
A. 19: The U.S. affiliate should treat the first taxable year for which section 936(h) applies as a new base year in accordance with procedures provided by regulations under section 472. Thus, the opening inventory for the first year for which section 936(h) applies (valuing possession products purchased from the possessions corporation on the basis of the cost of such possession products), would equal the new base year cost of the inventory of such pool of the U.S. affiliate. Increments and decrements at new base year cost would be valued for LIFO purposes pursuant to the procedures provided by regulations under section 472.
Q. 20: If the possessions corporation computes its income with respect to a product under the profit split method, with respect to which units of the product shall the profit split method apply?
A. 20: The profit split method shall apply to units of the possession product produced in whole or in part by the possessions corporation in the possession and sold during the taxable year by members of the affiliated group (other than foreign affiliates) to unrelated parties or to foreign affiliates. In no event shall the profit split method apply to units of the product which were not taken into account by the possessions corporation in applying the significant business presence test for the current taxable year or for any prior taxable year in which the possessions corporation also had a significant business presence in the possession with respect to such product.
Q. 1: How is pre-TEFRA inventory to be determined if the profit split option is elected and the FIFO method of costing inventory is used by the U.S. affiliate?
A. 1: Pre-TEFRA inventory is inventory which was produced by the possessions corporation and transferred to a U.S. affiliate prior to the possessions corporation's first taxable year beginning after December 31, 1982. Pre-TEFRA inventory will not be included for purposes of the profit split option. If the U.S. affiliate uses the FIFO method of costing inventory, the pre-TEFRA inventory will be treated as the first inventory sold by the U.S. affiliate during the first year in which section 936(h) applies and will not be included in the computation of combined taxable income for purposes of the profit split option. The treatment of pre-TEFRA inventory when FIFO costing is used by both the U.S. affiliate and the possessions corporation is illustrated by the following example in which FIFO unit costing is used:
Assume the following:
| X | Y | |||
|---|---|---|---|---|
| Possessions corporation | U.S. affiliate | |||
| Number of units | Cost per unit | Number of units | Cost per unit | |
| Beginning inventory | 500 | $150 | 200 | $225 |
| Units produced during 1983 | 1,000 | 200 | ||
| Ending inventory | 400 | 200 | 300 | |
In 1983, the beginning inventory of X, a possessions corporation, is 500 units with a unit cost of $150 and the beginning inventory of Y, the U.S. affiliate, is 200 units with a unit cost of $225, which represents the section 482 price paid by Y. Y's beginning inventory in 1983 represents purchases made in 1982 of products produced by X in that year. Y sells all the units it purchases from X to Z, a foreign affiliate. In 1983, X produces 1000 units at a unit cost of $200 and sells 1100 units to Y (the difference between 1500 units, representing X's 1983 beginning inventory (500) and the units produced by X in 1983 (1000), and X's ending inventory of 400 units). Of the 1100 units sold by X to Y in 1983 only 800 units (and not 1000 units) which were sold by Y to Z are taken into consideration in computing combined taxable income for 1983. Since FIFO costing by the possessions corporation is used, the cost is $150 per unit for the first 500 units and $200 per unit for the remaining 300 units. The 200 units sold by X to Y in 1982 are pre-TEFRA inventory and are not included in the computation of combined taxable income for 1983. They are also treated as the first units sold by Y to Z in 1983. This inventory has a unit cost of $225, which reflects the section 482 transfer price from X to Y in 1982. Y's 1983 ending inventory of 300 units will not be taken into consideration in computing the combined taxable income of X and Y for 1983 because the units have not been sold to a foreign affiliate or to persons who are not members of the affiliated group. In a subsequent year when the units are sold to Z, the cost to X and selling price to Z of these units will enter into the computation of combined taxable income for that year.
Q. 1: What are “covered intangibles” under section 936(h)(5)(C)(i)(II)?
A. 1: The term “covered intangibles” means (1) intangible property developed in a possession solely by the possessions corporation and owned by it, (2) manufacturing intangible property (described in section 936(h)(3)(B)(i)) which is acquired by the possessions corporation from unrelated persons, and (3) any other intangible property (described in section 936(h)(3)(B) (ii) through (v), to the extent not described in section 936(h)(3)(B)(i)) which relates to sales of products or services to unrelated persons for ultimate consumption or use in the possession in which the possessions corporation conducts its business. The possessions corporation is treated as the owner of covered intangibles for purposes of obtaining a return thereon.
Q. 2: Do covered intangibles include manufacturing intangible property which is acquired by an affiliate and subsequently transferred to the possessions corporation?
A. 2: No. In order for a manufacturing intangible to be treated as a covered intangible, the intangible property must be acquired directly by the possessions corporation from an unrelated person unless the manufacturing intangible was acquired by an affiliate from an unrelated person and was transferred to the possessions corporation by the affiliate prior to September 3, 1982.
Q. 3: If a possessions corporation licenses a manufacturing intangible from an unrelated party, will the licensed intangible be treated as a covered intangible?
A. 3: No.
Q. 4: How is ultimate consumption or use determined for purposes of the definition of covered intangibles?
A. 4: A product will be treated as having its ultimate use or consumption in a possession if it is sold by the possessions corporation to a related or unrelated person in a possession and is not resold or used or consumed outside of the possession within one year after the date of the sale.
Q. 5: Are sales of products that relate to covered intangibles excluded from the cost sharing fraction?
A. 5: If no manufacturing intangibles other than covered intangibles are associated with the possession product, then sales of such product will be excluded from the cost sharing fraction. If both covered and non-covered manufacturing intangibles are associated with the possession product, then sales of such product will be included in the cost sharing fraction.
Q. 6: If the cost sharing option is elected, is it necessary for the possessions corporation to be the legal owner of covered intangibles described in section 936(h)(5)(C)(i)(II)(c) related to the product in order for the possessions corporation to receive a full return with respect to such intangibles?
A. 6: No. For purposes of section 936(h), it is immaterial whether such covered intangibles are owned by the possessions corporation or by another member of the affiliated group. Moreover, if the legal owner of such covered intangibles which are subject to section 936(h)(5) is an affiliate of the possessions corporation, such person will not be required to charge an arm's-length royalty under section 482 to the possessions corporation.
[T.D. 8090, 51 FR 21532, June 13, 1986; 51 FR 27174, July 30, 1986, as amended by T.D. 8669, 61 FR 21367, May 10, 1996; 61 FR 39072, July 26, 1996; T.D. 8786, 63 FR 55025, Oct. 14, 1998]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 936 Repealed
- § 934 Limitation on reduction in income tax liability incurred to the Virgin Islands
- § 174 Amortization of research and experimental expenditures
- § 168 Accelerated cost recovery system
- § 30 Repealed
- § 482 Allocation of income and deductions among taxpayers
- § 6601 Interest on underpayment, nonpayment, or extensions of time for payment, of tax
- § 162 Trade or business expenses
- § 863 Special rules for determining source
Regulations it cites
- § 1.482-2 Determination of taxable income in specific situations.
- § 1.936-5 Intangible property income when an election out is made: Product, business presence, and contract manufacturing.
- § 1.472-8 Dollar-value method of pricing LIFO inventories.
- § 1.471-11 Inventories of manufacturers.
- § 1.861-8 Computation of taxable income from sources within the United States and from other sources and activities.
- § 1.482-3 Methods to determine taxable income in connection with a transfer of tangible property.
- § 1.861-17 Allocation and apportionment of research and experimental expenditures.
- § 1.994-1 Inter-company pricing rules for DISC's.
Cited by 2 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 8786 (63 FR 55025)
- Amended (61 FR 39072)
- Amended by T.D. 8669 (61 FR 21367)
- Amended (51 FR 27174)
- Issued by T.D. 8090 (51 FR 21532)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Possessions of the united states
Nearby sections
- § 1.935-1 Coordination of individual income taxes with Guam and the Northern Mariana Islands.
- § 1.936-1 Elections.
- § 1.936-4 Intangible property income in the absence of an election out.
- § 1.936-5 Intangible property income when an election out is made: Product, business presence, and contract manufacturing.
- § 1.936-6 Intangible property income when an election out is made: Cost sharing and profit split options; covered intangibles.
- § 1.936-7 Manner of making election under section 936 (h)(5); special election for export sales; revocation of election under section 936(a).
- § 1.936-10 Qualified investments.
- § 1.936-11 New lines of business prohibited.
- § 1.937-1 Bona fide residency in a possession.