
Treasury Regulations · 26 CFR
§ 1.937-2. Income from sources within a possession.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 937
Cite as 26 CFR § 1.937-2
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- April 9, 2008 by T.D. 9391
- Last amended
- December 11, 2020 by T.D. 9921
- Issued under
- 26 U.S.C. § 937
- Length
- 4,520 words · about 20 min to read
- Defines
- 4 terms
- Cross-references
- cites 18 Code sections and 9 regulations; cited by 11
(i) X, a U.S. citizen, resides in State N and acquires stock of Corporation C, a domestic corporation, in 2008 for $10x. X moves to the Northern Mariana Islands (NMI) on March 1, 2009 and changes his principal place of business to NMI on that same date. Assume for purposes of this example that, under § 1.937-1(b) and (f)(1) (year-of-move exception), X is considered a bona fide resident of NMI for 2009 through 2012. On March 1, 2009, the closing value of X's stock in Corporation C, a marketable security (within the meaning of paragraph (f)(1)(vii)(A) of this section), is $20x. On January 3, 2012, X sells all his Corporation C stock for $70x.
(ii) Pursuant to section 1277(e) of the Tax Reform Act of 1986, and absent an election under paragraph (f)(1)(vi) of this section, all of X's gain ($60x) will be treated as income from sources within the United States for all purposes of the Internal Revenue Code (including section 7654, as in effect with respect to the NMI), and (under paragraph (f)(1)(i) of this section) not as income from sources in the NMI. However, pursuant to paragraph (f)(1)(vi) of this section, X may elect on his 2012 income tax return filed with NMI to treat the portion of this gain attributable to X's possession holding period with respect to NMI as gain from sources within NMI. X's possession holding period with respect to NMI begins on March 1, 2009, the date his tax home changes to the NMI. Under paragraph (f)(1)(vi)(A) of this section, the portion of X's gain attributable to this possession holding period is $50x, the excess of the sale price of the stock ($70x) over its closing value ($20x) on the first day of the possession holding period. By reporting $50x of gain on his 2012 NMI return, X will elect under paragraph (f)(1)(vi) of this section to treat that amount as NMI source income.
(i) R, a U.S. citizen, resides in State F and acquires a 5 percent interest in Partnership P on January 1, 2009. R moves to Puerto Rico on June 1, 2010 and changes her principal place of business to Puerto Rico on that same date. Assume for purposes of this example that under § 1.937-1(b) and (f)(1) (year-of-move exception), R is considered a bona fide resident of Puerto Rico for 2010 through 2012. On June 1, 2010, R's interest in Partnership P is not a marketable security within the meaning of paragraph (f)(1)(vii)(A) of this section. On December 31, 2012, having owned the interest in Partnership P for a period of 4 years (1461 days), R sells it, recognizing gain of $100x.
(ii) Pursuant to paragraph (f)(1) of this section, and absent an election under paragraph (f)(1)(vi) of this section, the gain will not be treated as income from sources within Puerto Rico for purposes of the Internal Revenue Code (including section 933(1)). However, pursuant to paragraph (f)(1)(vi) of this section, R may elect on her 2012 return filed with the IRS to treat the portion of this gain attributable to R's possession holding period with respect to Puerto Rico as gain from sources within Puerto Rico. R's possession holding period with respect to Puerto Rico is the 945-day period from June 1, 2010, the date her tax home changes to Puerto Rico, through December 31, 2012, the date of sale. Under paragraph (f)(1)(vi)(B) of this section, the portion of R's gain attributable to this possession holding period is $64.68x, computed as follows:
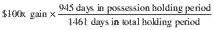
(iii) By reporting $64.68x of gain on her 2012 Federal return, R will elect under paragraph (f)(1)(vi) of this section to treat that amount as Puerto Rico source income.
X, a bona fide resident of Possession S, a section 931 possession (as defined in § 1.931-1(c)(1)), is engaged in a trade or business in the United States through an office in State H. In 2008, this office materially participates in the sale of inventory property in Possession S, such that the income from these inventory sales is considered effectively connected to this trade or business in the United States under section 864(c)(4)(B)(iii). This income will not be treated as income from sources within Possession S for purposes of section 931(a)(1) pursuant to paragraph (c)(1)(ii) of this section, but nonetheless will continue to be treated as income from sources without the United States under section 862 (for example, for purposes of section 904).
(i) X, a bona fide resident of Possession I, owns 25 percent of the outstanding shares of A Corp, a corporation organized under the laws of Possession I. In 2010, X receives a dividend of $70x from A Corp. During 2008 through 2010, A Corp has gross income from the following sources:
| Possession I sources | Sources outside possession I | |
|---|---|---|
| 2008 | $10x | $20x |
| 2009 | 20x | 10x |
| 2010 | 25x | 15x |
(ii) A Corp owns 50 percent of the outstanding shares of B Corp, a corporation organized under the laws of Country FC. During 2008 through 2010, B Corp has gross income from the following sources:
| Possession I sources | Sources outside possession I | |
|---|---|---|
| 2008 | $10x | $6x |
| 2009 | 14x | 8x |
| 2010 | 10x | 4x |
(iii) A Corp is treated as having received 50 percent of the gross income of B Corp. Therefore, for 2008 through 2010, the gross income of A Corp is from the following sources:
| Possession I sources | Sources outside possession I | |
|---|---|---|
| 2008 | $15x | $23x |
| 2009 | 27x | 14x |
| 2010 | 30x | 17x |
| Totals | $72x | $54x |
(iv) Pursuant to paragraph (g) of this section, the portion of the dividend of $70x that X receives from Corp A in 2010 that is treated as income from sources within Possession I is 72/126 of $70x, or $40x.
X is a U.S. citizen and a bona fide resident of the Northern Mariana Islands (NMI). In 2008, X receives compensation for services performed as a member of the crew of a fishing boat. Ten percent of the services for which X receives compensation are performed in the NMI, and 90 percent of X's services are performed in international waters. Under the principles of section 861(a)(3) as applied pursuant to paragraph (b) of this section, the compensation that X receives for services performed in the NMI is treated as income from sources within the NMI. Under the principles of section 863(d)(1)(A) as applied pursuant to paragraph (b) of this section, the compensation that X receives for services performed in international waters is treated as income from sources within the NMI for purposes of the Internal Revenue Code (including section 7654, as in effect with respect to the NMI). Thus, all of X's compensation for services during 2008 is treated as income from sources within the NMI.
X, a U.S. citizen, resides in State L and receives $2,500 of compensation for services performed in Possession J during 2008 for Y, X's employer. X is temporarily present in Possession J in 2008 for a period (or periods) not exceeding a total of 90 days. Y, a U.S. citizen, is not a bona fide resident of Possession J and is not engaged in a trade or business within Possession J. Under the principles of section 861(a)(3) as applied pursuant to paragraph (b) of this section, the compensation that X receives for services performed in Possession J during 2008 is not treated as income from sources within Possession J.
(i) Company Y, a corporation organized in State C, produces, markets, and distributes music products. Y enters into a recording contract with Z, a recording artist who is a bona fide resident of the U.S. Virgin Islands (USVI). Pursuant to the contract between Y and Z, Z agrees to perform services as writer, musician, and vocalist on the recording of a new musical composition and related music video. Under the contract, all songs, recordings and related artwork, packaging copy, and liner notes, together with copyrights and other intellectual property in those works, are the sole property of Y, and Z obtains no proprietary rights in that property. As compensation for Z's services, all of which are performed at a recording studio or other locations in the USVI, Y agrees to pay amounts designated as the “writer's share” to Z based on a percentage of the music products sold. Y also agrees to make an upfront payment to Z as an advance against future portions of Z's writer's share.
(ii) To the extent that Z performs personal services within the USVI, the compensation that Z receives for his services is sourced to the USVI under the principles of section 861(a)(3) and § 1.861-4 as applied pursuant to § 1.937-2(b). If all of Z's services are performed in the USVI, none of the writer's share is derived from sources within the United States under section 861(a)(3) and § 1.861-4, nor is it effectively connected with the conduct of a trade or business in the United States under section 864(c)(3). Accordingly, the U.S. income rule of section 937(b)(2) and paragraph (c)(1) of this section would not operate to prevent Z's services income from being USVI source or USVI effectively connected income within the meaning of section 937(b)(1). If Z also performs services in the United States, however, then the U.S. income rule would apply to the part of Z's compensation that is sourced to the United States under section 861(a)(3) and § 1.861-4. In the event that Y and Z are controlled taxpayers within the meaning of § 1.482-1(i)(5), section 482 and the regulations under that section, including § 1.482-9T(i), would apply to evaluate the arm's length amount charged for Z's controlled services.
[T.D. 9391, 73 FR 19370, Apr. 9, 2008, as amended at T.D. 9391, 73 FR 27728, May 14, 2008; T.D. 9391, 73 FR 36594, June 27, 2008; T.D. 9921, 85 FR 79853, Dec. 11, 2020]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 937 Residence and source rules involving possessions
- § 957 Controlled foreign corporations; United States persons
- § 932 Coordination of United States and Virgin Islands income taxes
- § 861 Income from sources within the United States
- § 863 Special rules for determining source
- § 731 Extent of recognition of gain or loss on distribution
- § 735 Character of gain or loss on disposition of distributed property
- § 1223 Holding period of property
- § 865 Source rules for personal property sales
- § 243 Dividends received by corporations
- § 904 Limitation on credit
- § 318 Constructive ownership of stock
- § 7654 Coordination of United States and certain possession individual income taxes
- § 933 Income from sources within Puerto Rico
- § 931 Income from sources within Guam, American Samoa, or the Northern Mariana Islands
- § 864 Definitions and special rules
- § 862 Income from sources without the United States
- § 482 Allocation of income and deductions among taxpayers
Regulations it cites
- § 1.863-3 Allocation and apportionment of income from certain sales of inventory.
- § 1.1092(d)-1 Definitions and special rules.
- § 1.937-1 Bona fide residency in a possession.
- § 1.937-3 Income effectively connected with the conduct of a trade or business in a possession.
- § 1.861-9 Allocation and apportionment of interest expense and rules for asset-based apportionment.
- § 1.882-5 Determination of interest deduction.
- § 1.931-1 Exclusion of certain income from sources within Guam, American Samoa, or the Northern Mariana Islands.
- § 1.861-4 Compensation for labor or personal services.
- § 1.482-1 Allocation of income and deductions among taxpayers.
Cited by 11 other regulations
- § 1.881-5 Exception for certain possessions corporations.
- § 1.931-1 Exclusion of certain income from sources within Guam, American Samoa, or the Northern Mariana Islands.
- § 1.932-1 Coordination of United States and Virgin Islands income taxes.
- § 1.933-1 Exclusion of certain income from sources within Puerto Rico.
- § 1.934-1 Limitation on reduction in income tax liability incurred to the Virgin Islands.
- § 1.935-1 Coordination of individual income taxes with Guam and the Northern Mariana Islands.
- § 1.937-1 Bona fide residency in a possession.
- § 1.937-3 Income effectively connected with the conduct of a trade or business in a possession.
- § 1.957-3 United States person defined.
- § 1.6038-2 Information returns required of United States persons with respect to annual accounting periods of certain foreign corporations.
- § 1.6046-1 Returns as to organization or reorganization of foreign corporations and as to acquisitions of their stock.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9921 (85 FR 79853)
- Amended by T.D. 9391 (73 FR 36594)
- Amended by T.D. 9391 (73 FR 27728)
- Issued by T.D. 9391 (73 FR 19370)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Possessions of the united states
Nearby sections
- § 1.936-7 Manner of making election under section 936 (h)(5); special election for export sales; revocation of election under section 936(a).
- § 1.936-10 Qualified investments.
- § 1.936-11 New lines of business prohibited.
- § 1.937-1 Bona fide residency in a possession.
- § 1.937-2 Income from sources within a possession.
- § 1.937-3 Income effectively connected with the conduct of a trade or business in a possession.