
Treasury Regulations · 26 CFR
§ 1.882-5. Determination of interest deduction.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 882
Cite as 26 CFR § 1.882-5
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- March 8, 1996 by T.D. 8658
- Last amended
- December 15, 2025 by T.D. 10042
- Issued under
- 26 U.S.C. § 882
- Length
- 9,825 words · about 43 min to read
- Defines
- 1 term
- Cross-references
- cites 14 Code sections and 11 regulations; cited by 21
(i) Facts: FC is a foreign corporation that conducts business through a branch, B, in the United States. Among B's U.S. assets is an interest in a partnership, P, that is engaged in airplane leasing solely in the U.S. FC contributes 200 × to P in exchange for its partnership interest. P incurs qualified nonrecourse indebtedness within the meaning of § 1.861-10T to purchase an airplane. FC's share of the liability of P, as determined under section 752, is 800 ×.
(ii) Analysis: Pursuant to paragraph (a)(1)(ii)(B) of this section, FC is permitted to directly allocate its distributive share of the interest incurred with respect to the qualified nonrecourse indebtedness to FC's distributive share of the rental income generated by the airplane. A liability the interest on which is allocated directly to the income from a particular asset under paragraph (a)(1)(ii)(B) of this section is disregarded for purposes of paragraphs (b)(1), (c)(2)(vi), and (d)(2)(vii) or (e)(1)(ii) of this section. Consequently, for purposes of determining the value of FC's assets under paragraphs (b)(1) and (c)(2)(vi) of this section, FC's basis in P is reduced by the 800 × liability as determined under section 752, but is not increased by the 800 × liability that is directly allocated under paragraph (a)(1)(ii)(B) of this section. Similarly, pursuant to paragraph (a)(1)(ii)(B) of this section, the 800 × liability is disregarded for purposes of determining FC's liabilities under paragraphs (c)(2)(vi) and (d)(2)(vii) of this section.
(i) FC is a foreign corporation that conducts a real estate business in the United States. In its 1997 tax year, FC has no outstanding indebtedness, and therefore incurs no interest expense. FC elects to use the 50% fixed ratio under paragraph (c)(4) of this section.
(ii) Under paragraph (a)(3) of this section, FC is not allowed to deduct any interest expense that exceeds the amount of interest on indebtedness paid or accrued in that taxable year. Since FC incurred no interest expense in taxable year 1997, FC will not be entitled to any interest deduction for that year under § 1.882-5, notwithstanding the fact that FC has elected to use the 50% fixed ratio.
(i) FC is a foreign corporation that is a bank under section 585(a)(2) and a financial institution under section 265(b)(5). FC is a calendar year taxpayer, and operates a U.S. branch, B. Throughout its taxable year 1997, B holds only two assets that are U.S. assets within the meaning of paragraph (b)(1) of this section. FC does not make a fair-market value election under paragraph (b)(2)(ii) of this section, and, therefore, values its U.S. assets according to their bases under paragraph (b)(2)(i) of this section. The first asset is a taxable security with an adjusted basis of $100. The second asset is an obligation the interest on which is exempt from federal taxation under section 103, with an adjusted basis of $50. The tax-exempt obligation is not a qualified tax-exempt obligation as defined by section 265(b)(3)(B).
(ii) FC calculates its interest expense under § 1.882-5 to be $12. Under paragraph (a)(5) of this section, however, a portion of the interest expense that is allocated to FC's effectively connected income under § 1.882-5 is disallowed in accordance with the provisions of section 265(b). Using the methodology prescribed under section 265, the amount of disallowed interest expense is $4, calculated as follows:
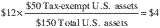
(iii) Therefore, FC deducts a total of $8 ($12-$4) of interest expense attributable to its effectively connected income in 1997.
(i) FC is a foreign corporation, resident in Country X, that is actively engaged in the banking business in the United States through a permanent establishment, B. The income tax treaty in effect between Country X and the United States provides that FC is not taxable on foreign source income earned by its U.S. permanent establishment. In its 1997 tax year, B earns $90 of U.S. source income from U.S. assets with an adjusted tax basis of $900, and $12 of foreign source interest income from U.S. assets with an adjusted tax basis of $100. FC's U.S. interest expense deduction, computed in accordance with § 1.882-5, is $500.
(ii) Under paragraph (a)(5) of this section, FC is required to apply any provision that disallows, defers, or capitalizes interest expense after determining the interest expense allocated to ECI under § 1.882-5. Section 265(a)(2) disallows interest expense that is allocable to one or more classes of income that are wholly exempt from taxation under subtitle A of the Internal Revenue Code. Section 1.265-1(b) provides that income wholly exempt from taxes includes both income excluded from tax under any provision of subtitle A and income wholly exempt from taxes under any other law. Section 894 specifies that the provisions of subtitle A are applied with due regard to any relevant treaty obligation of the United States. Because the treaty between the United States and Country X exempts foreign source income earned by B from U.S. tax, FC has assets that produce income wholly exempt from taxes under subtitle A, and must therefore allocate a portion of its § 1.882-5 interest expense to its exempt income. Using the methodology prescribed under section 265, the amount of disallowed interest expense is $50, calculated as follows:
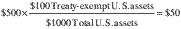
(iii) Therefore, FC deducts a total of $450 ($500-$50) of interest expense attributable to its effectively connected income in 1997.
FC is a foreign corporation that qualifies as a bank under section 585(a)(2)(B) (without regard to the second sentence thereof), but is not a large bank as defined in section 585(c)(2). FC conducts business through a branch, B, in the United States. Among B's U.S. assets are a portfolio of loans with an adjusted basis of $500. FC accounts for its bad debts for U.S. federal income tax purposes under the reserve method, and B maintains a deductible reserve for bad debts of $50. Under paragraph (b)(2)(iii) of this section, the total value of FC's portfolio of loans is $450 ($500−$50).
Bank Z, a resident of country X, has a branch in the United States through which it conducts its banking business. In preparing its financial statements in country X, Z treats an instrument documented as perpetual subordinated debt as a liability. Under U.S. tax principles, however, this instrument is treated as equity. Consequently, the classification of this instrument as a liability for purposes of paragraph (c)(2)(iii) of this section is not in accordance with U.S. tax principles.
Bank Z, a resident of country X, has a branch in the United States through which it conducts its banking business. Bank Z is a large bank as defined in section 585(c)(2). The tax rules of country X allow Bank Z to take deductions for additions to certain reserves. Bank Z decreases the value of the assets on its financial statements by the amounts of the reserves. The additions to the reserves under country X tax rules cause the value of Bank Z's assets to differ from the value of those assets determined under U.S. tax principles to a degree that materially affects the value of taxpayer's worldwide assets. Consequently, the valuation of Bank Z's worldwide assets under country X tax principles is not substantially in accordance with U.S. tax principles. Bank Z must increase the value of its worldwide assets under paragraph (c)(2)(iii) of this section by the amount of its country X reserves.
Bank Z, a resident of country X, has a branch in the United States through which it conducts its banking business. In determining the value of its worldwide assets, Bank Z computes the adjusted basis of certain non-U.S. assets according to the depreciation methodology provided under country X tax laws, which is different than the depreciation methodology provided under U.S. tax law. If the depreciation methodology provided under country X tax laws does not differ from U.S. tax principles to a degree that materially affects the value of Bank Z's worldwide assets or Bank Z's actual ratio as computed under paragraph (c)(2) of this section, then the valuation of Bank Z's worldwide assets under paragraph (c)(2)(iv) of this section is substantially in accordance with U.S. tax principles.
[Reserved]
is a foreign corporation engaged in the active conduct of a banking business through a branch, B, in the United States. P, an unrelated foreign corporation, deposits $100,000 in the home office of FC. Shortly thereafter, in a transaction arranged by the home office of FC, B lends $80,000 bearing interest at an arm's length rate to S, a wholly owned U.S. subsidiary of P. The director of field operations or the Assistant Commissioner (International) determines that one of the principal purposes for making and incurring such loans is to increase FC's actual ratio. For purposes of this section, therefore, P is treated as having directly lent $80,000 to S. Thus, for purposes of paragraph (c) of this section (Step 2), the director of field operations or the Assistant Commissioner (International) may offset FC's liability and asset arising from this transaction, resulting in a net liability of $20,000 that is not a booked liability of B. Because the loan to S from B was initiated and arranged by the home office of FC, with no material participation by B, the loan to S will not be treated as a U.S. asset.
(i) Facts. (A) FC is a foreign corporation that is not a bank and that actively conducts a real estate business through a branch, B, in the United States. For the taxable year, FC's balance sheet and income statement is as follows (assume amounts are in U.S. dollars and computed in accordance with paragraphs (b)(2) and (b)(3) of this section):
| Value | ||
|---|---|---|
| Asset 1 | $2,000 | |
| Asset 2 | 2,500 | |
| Asset 3 | 5,500 | |
| Amount | Interest Expense | |
| Liability 1 | $800 | 56 |
| Liability 2 | 3,200 | 256 |
| Capital | 6,000 | 0 |
(B) Asset 1 is the stock of FC's wholly-owned domestic subsidiary that is also actively engaged in the real estate business. Asset 2 is a building in the United States producing rental income that is entirely ECI to FC. Asset 3 is a building in the home country of FC that produces rental income. Liabilities 1 and 2 are loans that bear interest at the rates of 7% and 8%, respectively. Liability 1 is a booked liability of B, and Liability 2 is booked in FC's home country. Assume that FC has not elected to use the fixed ratio in Step 2.
(ii) Step 1. Under paragraph (b)(1) of this section, Assets 1 and 3 are not U.S. assets, while Asset 2 qualifies as a U.S. asset. Thus, under paragraph (b)(3) of this section, the total value of U.S. assets for the taxable year is $2,500, the value of Asset 2.
(iii) Step 2. Under paragraph (c)(1) of this section, the amount of FC's U.S.-connected liabilities for the taxable year is determined by multiplying $2,500 (the value of U.S. assets determined under Step 1) by the actual ratio for the taxable year. The actual ratio is the average amount of FC's worldwide liabilities divided by the average value of FC's worldwide assets. The amount of Liability 1 is $800, and the amount of Liability 2 is $3,200. Thus, the numerator of the actual ratio is $4,000. The average value of worldwide assets is $10,000 (Asset 1 + Asset 2 + Asset 3). The actual ratio, therefore, is 40% ($4,000/$10,000), and the amount of U.S.-connected liabilities for the taxable year is $1,000 ($2,500 U.S. assets × 40%).
(iv) Step 3. Because the amount of FC's U.S.-connected liabilities ($1,000) exceeds the average total amount of U.S. booked liabilities of B ($800), FC determines its interest expense in accordance with paragraph (d)(5) of this section by adding the interest paid or accrued on U.S. booked liabilities, and the interest expense associated with the excess of its U.S.-connected liabilities over its average total amount of U.S. booked liabilities. Under paragraph (d)(5)(ii) of this section, FC determines the interest rate attributable to its excess U.S.-connected liabilities by dividing the interest expense paid or accrued by the average amount of U.S.-dollar denominated liabilities, which produces an interest rate of 8% ($256/$3200). Therefore, FC's allocable interest expense is $72 ($56 of interest expense from U.S. booked liabilities plus $16 ($200 × 8%) of interest expense attributable to its excess U.S.-connected liabilities).
(i) The facts are the same as in Example 1, except that FC makes a fixed ratio election under paragraph (c)(4) of this section. The conclusions under Step 1 are the same as in Example 1.
(ii) Step 2. Under paragraph (c)(1) of this section, the amount of U.S.-connected liabilities for the taxable year is determined by multiplying $2,500 (the value of U.S. assets determined under Step 1) by the fixed ratio for the taxable year, which, under paragraph (c)(4) of this section is 50 percent. Thus, the amount of U.S.-connected liabilities for the taxable year is $1,250 ($2,500 U.S. assets × 50%).
(iii) Step 3. As in Example 1, the amount of FC's U.S.-connected liabilities exceed the average total amount of U.S. booked liabilities of B, requiring FC to determine its interest expense under paragraph (d)(5) of this section. In this case, however, FC has excess U.S.-connected liabilities of $450 ($1,250 of U.S.-connected liabilities—$800 U.S. booked liabilities). FC therefore has allocable interest expense of $92 ($56 of interest expense from U.S. booked liabilities plus $36 ($450 × 8%) of interest expense attributable to its excess U.S.-connected liabilities).
(i) Facts. Bank Z, a resident of country X, has a branch in the United States through which it conducts its banking business. For the taxable year, Z has U.S.-connected liabilities, determined under paragraph (c) of this section, equal to $300. Z, however, has U.S. booked liabilities of $300 and U500. Therefore, assuming an exchange rate of the U to the U.S. dollar of 5:1, Z has U.S. booked liabilities of $400 ($300 + (U500 ÷ 5)).
(ii) U.S.-connected liabilities. Because Z's U.S. booked liabilities of $400 exceed its U.S.-connected liabilities by $100, all of Z's interest expense allocable to its U.S. trade or business must be scaled back pro-rata. To determine the scaling ratio, Z divides its U.S.-connected liabilities by its U.S. booked liabilities, as required by paragraph (d)(4) of this section. Z's interest expense is scaled back pro rata by the resulting ratio of 3/4 ($300 ÷ $400). Z's income, expense, gain or loss from hedging transactions described in paragraph (d)(2)(vi) of this section must be similarly reduced.
[Reserved]
(i) Facts. Bank A, a resident of Country X maintains a banking office in the U.S. that records transactions on three sets of books for State A, an International Banking Facility (IBF) for its bank regulatory approved international transactions, and a shell branch licensed operation in Country C. Bank A records substantial ECI assets from its bank lending and placement activities and a mix of interbranch and non-ECI producing assets from the same or similar activities on the books of State A branch and on its IBF. Bank A's Country C branch borrows substantially from third parties, as well as from its home office, and lends all of its funding to its State A branch and IBF to fund the mix of ECI, interbranch and non-ECI activities on those two books. The consolidated books of State A branch and IBF indicate that a substantial amount of the total book assets constitute U.S. assets under paragraph (b) of this section. Some of the third-party borrowings on the books of the State A branch are used to lend directly to Bank A's home office in Country X. These borrowings reflect the average borrowing rate of the State A branch, IBF and Country C branches as a whole. All third-party borrowings reflected on the books of State A branch, the IBF and Country C branch were recorded on such books before the close of business on the day the liabilities were acquired by Bank A.
(ii) U.S. booked liabilities. The facts demonstrate that the separate State A branch, IBF and Country C branch books taken together, constitute a set of books within the meaning of paragraph (d)(2)(iii)(A)(1) of this section. Such set of books as a whole has a direct relationship to an ECI activity under paragraph (d)(2)(iii)(A)(2) of this section even though the Country C branch books standing alone would not. The third-party liabilities recorded on the books of Country C constitute U.S. booked liabilities because they were timely recorded and the overall set of books on which they were reflected has a direct relationship to a bank lending and interbank placement ECI producing activity. The third-party liabilities that were recorded on the books of State A branch that were used to lend funds to Bank A's home office also constitute U.S. booked liabilities because the interbranch activity the funds were used for is a lending activity of a type that also gives rise to a substantial amount of ECI that is properly reflected on the same set of books as the interbranch loans. Accordingly, the liabilities are not traced to their specific interbranch use but to the overall activity of bank lending and interbank placements which gives rise to substantial ECI. The facts show that the liabilities were not acquired to increase artificially the interest expense of Bank A's U.S. booked liabilities as a whole under paragraph (d)(2)(v) of this section. The third-party liabilities also constitute U.S. booked liabilities for purposes of determining Bank A's branch interest under § 1.884-4(b)(1)(i)(A) regardless of whether Bank A uses the Adjusted U.S. booked liability method, or the Separate Currency Pool method to allocate its interest expense under paragraph 5(e) of this section.
Separate currency pools method—(i) Facts. (A) Bank Z, a resident of country X, has a branch in the United States through which it conducts its banking business. For its 1997 taxable year, Z has U.S. assets, as defined in paragraph (b) of this section, that are denominated in U.S. dollars and in U, the country X currency. Accordingly, Z's U.S. assets are as follows:
| Average value | |
|---|---|
| U.S. Dollar Assets | $20,000 |
| U Assets | U 5,000 |
(B) Z's worldwide liabilities are also denominated in U.S. Dollars and in U. The average interest rates on Z's worldwide liabilities, including those in the United States, are 6% on its U.S. dollar liabilities, and 12% on its liabilities denominated in U. Assume that Z has properly elected to use its actual ratio of 95% to determine its U.S.-connected liabilities in Step 2, and has also properly elected to use the separate currency pools method provided in paragraph (e) of this section.
(ii) Determination of interest expense. Z determines the interest expense attributable to its U.S.-connected liabilities according to the steps described below.
(A) First, Z separates its U.S. assets into two currency pools, one denominated in U.S. dollars ($20,000) and the other denominated in U (U5,000).
(B) Second, Z multiplies each pool of assets by the applicable ratio of worldwide liabilities to assets, which in this case is 95%. Thus, Z has U.S.-connected liabilities of $19,000 ($20,000 × 95%), and U4750 (U5000 × 95%).
(C) Third, Z calculates its interest expense by multiplying each pool of its U.S.-connected liabilities by the relevant interest rates. Accordingly, Z's allocable interest expense for the year is $1140 ($19,000 × 6%), the sum of the expense associated with its U.S. dollar liabilities, plus U570 (U4750 × 12%), the interest expense associated with its liabilities denominated in U. Z must translate its interest expense denominated in U in accordance with the rules provided in section 988, and then must determine whether it is subject to any other provision of the Code that would disallow or defer any portion of its interest expense so determined.
[Reserved]
[T.D. 8658, 61 FR 9329, Mar. 8, 1996; 61 FR 15891, Apr. 10, 1996, as amended by T.D. 9281, 71 FR 47448, Aug. 17, 2006; 71 FR 56868, Sept. 28, 2006; T.D. 9465, 74 FR 49320, Sept. 28, 2009; 74 FR 57252, Nov. 5, 2009; T.D. 9976, 88 FR 42234, June 30, 2023; T.D. 10042, 90 FR 57915, Dec. 15, 2025]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 882 Tax on income of foreign corporations connected with United States business
- § 265 Expenses and interest relating to tax-exempt income
- § 163 Interest
- § 263A Capitalization and inclusion in inventory costs of certain expenses
- § 752 Treatment of certain liabilities
- § 585 Reserves for losses on loans of banks
- § 103 Interest on State and local bonds
- § 894 Income affected by treaty
- § 883 Exclusions from gross income
- § 953 Insurance income
- § 475 Mark to market accounting method for dealers in securities
- § 1256 Section 1256 contracts marked to market
- § 267 Losses, expenses, and interest with respect to transactions between related taxpayers
- § 988 Treatment of certain foreign currency transactions
Regulations it cites
- § 1.861-10T Special allocations of interest expense (temporary).
- § 1.884-1 Branch profits tax.
- § 1.989(b)-1 Definition of weighted average exchange rate.
- § 1.988-2 Recognition and computation of exchange gain or loss.
- § 1.985-1 Functional currency.
- § 1.892-2T Foreign government defined (temporary regulations).
- § 1.892-5 Controlled commercial entity.
- § 301.9100-1 Extensions of time to make elections.
- § 1.864-4 U.S. source income effectively connected with U.S. business.
- § 1.861-9T Allocation and apportionment of interest expense (temporary).
- § 1.884-4 Branch-level interest tax.
Cited by 21 other regulations
- § 1.59A-0 Table of contents.
- § 1.59A-3 Base erosion payments and base erosion tax benefits.
- § 1.267A-5 Definitions and special rules.
- § 1.267A-6 Examples.
- § 1.585-5 Denial of bad debt reserves for large banks.
- § 1.861-8 Computation of taxable income from sources within the United States and from other sources and activities.
- § 1.861-9T Allocation and apportionment of interest expense (temporary).
- § 1.881-3 Conduit financing arrangements.
- § 1.882-0 Table of contents.
- § 1.882-4 Allowance of deductions and credits to foreign corporations.
- § 1.884-0 Overview of regulation provisions for section 884.
- § 1.884-1 Branch profits tax.
- § 1.884-2T Special rules for termination or incorporation of a U.S. trade or business or liquidation or reorganization of a foreign corporation or its domestic subsidiary (temporary).
- § 1.884-4 Branch-level interest tax.
- § 1.937-2 Income from sources within a possession.
- § 1.988-5 Section 988(d) hedging transactions.
- § 1.1275-6 Integration of qualifying debt instruments.
- § 1.1446-2 Determining a partnership's effectively connected taxable income allocable to foreign partners under section 704.
- § 1.1503(d)-0 Table of contents.
- § 1.1503(d)-5 Attribution of items and basis adjustments.
- § 1.1503(d)-7 Examples.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 10042 (90 FR 57915)
- Amended by T.D. 9976 (88 FR 42234)
- Amended (74 FR 57252)
- Amended by T.D. 9465 (74 FR 49320)
- Amended (71 FR 56868)
- Amended by T.D. 9281 (71 FR 47448)
- Amended (61 FR 15891)
- Issued by T.D. 8658 (61 FR 9329)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Foreign corporations
Nearby sections
- § 1.882-1 Taxation of foreign corporations engaged in U.S. business or of foreign corporations treated as having effectively connected income.
- § 1.882-2 Income of foreign corporations treated as effectively connected with U.S. business.
- § 1.882-3 Gross income of a foreign corporation.
- § 1.882-4 Allowance of deductions and credits to foreign corporations.
- § 1.882-5 Determination of interest deduction.
- § 1.883-0 Outline of major topics.
- § 1.883-1 Exclusion of income from the international operation of ships or aircraft.
- § 1.883-2 Treatment of publicly-traded corporations.
- § 1.883-3 Treatment of controlled foreign corporations.