
Treasury Regulations · 26 CFR
§ 25.2523(i)-2. Treatment of spousal joint tenancy property where one spouse is not a United States citizen.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 2523(i)
Cite as 26 CFR § 25.2523(i)-2
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- August 22, 1995 by T.D. 8612
- Issued under
- 26 U.S.C. § 2523(i)
- Length
- 1,336 words · about 6 min to read
- Cross-references
- cites 3 Code sections and 4 regulations; cited by 0
In 1992, A, a United States citizen, furnished $200,000 and A's spouse B, a resident alien, furnished $50,000 for the purchase and subsequent improvement of real property held by them as tenants by the entirety. The property is sold in 1998 for $300,000. A receives $225,000 and B receives $75,000 of the sales proceeds. The termination results in a gift of $15,000 by A to B, computed as follows:
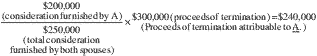
$240,000−$225,000 (proceeds received by A) = $15,000 gift by A to B.
In 1986, A purchased real property for $300,000 and took title in the names of A and B, A's spouse, as joint tenants. Under section 2511 and § 25.2511-1(h)(1) of the regulations, A was treated as making a gift of one-half of the value of the property ($150,000) to B. In 1995, the real property is sold for $400,000 and B receives the entire proceeds of sale. For purposes of determining the amount of the gift on termination of the tenancy under the principles of section 2515 and the regulations thereunder, the amount treated as a gift to B on creation of the tenancy under section 2511 is treated as B's contribution towards the purchase of the property. Accordingly, the termination of the tenancy results in a gift of $200,000 from A to B determined as follows:
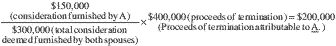
$200,000−0 (proceeds received by A) = $200,000 gift by A to B.
[T.D. 8612, 60 FR 43553, Aug. 22, 1995]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 2515 Treatment of generation-skipping transfer tax
- § 2523 Gift to spouse
- § 2511 Transfers in general
Regulations it cites
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Issued by T.D. 8612 (60 FR 43553)
Where it sits in 26 CFR
- Subchapter B Estate and gift taxes
- Part 25 Gift tax; gifts made after december 31, 1954
- Deductions
Nearby sections
- § 25.2523(g)-1 Special rule for charitable remainder trusts.
- § 25.2523(h)-1 Denial of double deduction.
- § 25.2523(h)-2 Effective dates.
- § 25.2523(i)-1 Disallowance of marital deduction when spouse is not a United States citizen.
- § 25.2523(i)-2 Treatment of spousal joint tenancy property where one spouse is not a United States citizen.
- § 25.2523(i)-3 Effective date.
- § 25.2524-1 Extent of deductions.