
Treasury Regulations · 26 CFR
§ 26.2601-1. Effective dates.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 2601
Cite as 26 CFR § 26.2601-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- December 27, 1995 by T.D. 8644
- Last amended
- January 2, 2004 by T.D. 9102
- Issued under
- 26 U.S.C. § 2601
- Length
- 13,149 words · about 57 min to read
- Defines
- 1 term
- Cross-references
- cites 16 Code sections and 6 regulations; cited by 3
T created a revocable trust on September 30, 1985, that became irrevocable when T died on October 10, 1986. Although the trust terminated in favor of a grandchild of T, the transfer to the grandchild is not treated as occurring on October 23, 1986, pursuant to paragraph (a)(2) of this section because it is not an inter vivos transfer subject to chapter 12. The transfer is not subject to chapter 13 because it is in the nature of a testamentary transfer that occurred prior to October 23, 1986.
On September 25, 1985, T, the settlor of a trust that was created before September 25, 1985, held a testamentary power to add new beneficiaries to the trust. T held no other powers over any portion of the trust. The testamentary power held by T would have caused the trust to be included in T's gross estate under section 2038 if T had died on September 25, 1985. Therefore, the trust is not an irrevocable trust for purposes of this section.
On September 25, 1985, S, the spouse of the settlor of a trust in existence on that date, had an annual right to withdraw a portion of the principal of the trust. The trust was otherwise irrevocable on that date. Because the power was not held by the settlor of the trust, it is not a power described in section 2038. Thus, the trust is considered an irrevocable trust for purposes of this section.
In 1984, T created a trust and retained the right to expand the class of remaindermen to include any of T's afterborn grandchildren. As of September 25, 1985, all of T's grandchildren were named remaindermen of the trust. Since the exercise of T's power was dependent on there being afterborn grandchildren who were not members of the class of remaindermen, a contingency that did not exist on September 25, 1985, the trust is not considered subject to the power on September 25, 1985, and is an irrevocable trust for purposes of this section. The result is not changed even if grandchildren are born after September 25, 1985, whether or not T exercises the power to expand the class of remaindermen.
On September 25, 1985, T purchased an insurance policy on T's own life and designated child, C, and grandchild, GC, as the beneficiaries. T retained the power to obtain from the insurer a loan against the surrender value of the policy. T's insurance policy is a trust (as defined in section 2652(b)) for chapter 13 purposes. The trust is not considered an irrevocable trust because, on September 25, 1985, T possessed an incident of ownership that would have caused the value of the policy to be included in T's gross estate under section 2042 if T had died on that date.
In 1984, T created a trust naming T's grandchildren as the income and remainder beneficiaries. T retained the power to revoke the trust as to one-half of the principal at any time prior to T's death. T retained no other powers over the trust principal. T did not die before September 25, 1985, and did not exercise or release the power before that date. The half of the trust not subject to T's power to revoke is an irrevocable trust for purposes of this section.
On March 28, 1985, T established a trust. The trust instrument provided that the trustee must distribute all income annually to T's spouse, S, during S's life. Upon S's death, the remainder is to be distributed to GC, the grandchild of T and S. On April 15, 1986, T elected under section 2523(f) to treat the property in the trust as qualified terminable interest property. On December 1, 1987, S died and soon thereafter the trust assets were distributed to GC. Because the trust was irrevocable on September 25, 1985, the transfer to GC is not subject to tax under chapter 13. T is treated as the transferor with respect to the transfer of the trust assets to GC in the same manner as if T had made an election under section 2652(a)(3) to reverse the effect of the section 2523(f) election for chapter 13 purposes.
Assume the same facts as in Example 1, except the trust instrument provides that after S's death all income is to be paid annually to C, the child of T and S. Upon C's death, the remainder is to be distributed to GC. C died on October 1, 1992, and soon thereafter the trust assets are distributed to GC. Because the trust was irrevocable on September 25, 1985, the termination of C's interest is not subject to chapter 13.
(i) On August 16, 1980, T established an irrevocable trust. Under the trust instrument, the trustee is required to distribute the entire income annually to T's child, C, for life, then to T's grandchild, GC, for life. Upon GC's death, the remainder is to be paid to GC's issue. On October 1, 1986, when the total value of the entire trust is $400,000, T transfers $100,000 to the trust. The allocation fraction is computed as follows:
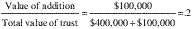
(ii) Thus, immediately after the transfer, 20 percent of the value of future generation-skipping transfers under the trust will be subject to chapter 13.
Assume the same facts as in Example 1, except immediately prior to the transfer on October 1, 1986, the fair market value of the individual assets in the trust totaled $400,000. Also, assume that the trust had accrued and unpaid debts, expenses, and taxes totaling $300,000. Assume further that the entire $300,000 represented amounts that would be deductible under section 2053 if the trust were includible in the transferor's gross estate. The numerator of the allocation fraction is $100,000 and the denominator of the allocation fraction is $200,000 (($400,000−$300,000) + $100,000). Thus, the allocation fraction is .5 ($100,000/$200,000) and 50 percent of the value of future generation-skipping transfers will be subject to chapter 13.
(i) Assume the same facts as in Example 1, except on January 30, 1988, when the total value of the entire trust is $600,000, T transfers an additional $40,000 to the trust. Before the transfer, the value of the portion of the trust that was attributable to the prior addition was $120,000 ($600,000 × .2). The new allocation fraction is computed as follows:
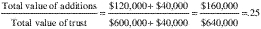
(ii) Thus, immediately after the transfer, 25 percent of the value of future generation-skipping transfers under the trust will be subject to chapter 13.
Assume the same facts as in Example 3, except on March 1, 1989, when the value of the trust is $800,000, C dies. A generation-skipping transfer occurs at C's death because of the termination of C's life estate. Therefore, $200,000 ($800,000 × .25) is subject to tax under chapter 13.
On June 19, 1980, T established an irrevocable trust with a corpus of $500,000. The trust instrument provides that the trustee shall distribute the entire income from the trust annually to T's spouse, S, during S's life. At S's death, the remainder is to be distributed to T and S's grandchild, GC. T also gave S a general power of appointment over one-half of the trust assets. On December 21, 1989, when the value of the trust corpus is $1,500,000, S died without having exercised the general power of appointment. The value of one-half of the trust corpus, $750,000 ($1,500,000 × .5) is included in S's gross estate under section 2041(a) and is subject to tax under Chapter 11. Because the value of one-half of the trust corpus is subject to tax under Chapter 11 with respect to S's estate, S is treated as the transferor of that property for purposes of Chapter 13 (see section 2652(a)(1)(A)). For purposes of the generation-skipping transfer tax, the lapse of S's power of appointment is treated as if $750,000 ($1,500,000 × .5) had been distributed to S and then transferred back to the trust. Thus, S is considered to have added $750,000 ($1,500,000 × .5) to the trust at the date of S's death. Because this constructive addition occurred after September 25, 1985, 50 percent of the corpus of the trust became subject to Chapter 13 at S's death.
On June 19, 1980, T established an irrevocable trust with a principal of $500,000. The trust instrument provides that the trustee shall distribute the entire income from the trust annually to T's spouse, S, during S's life. At S's death, the remainder is to be distributed to GC, the grandchild of T and S. On October 1, 1985, when the trust assets were valued at $800,000, T added $200,000 to the trust. After the transfer on October 1, 1985, the allocation fraction was .2 ($200,000/$1,000,000). On December 21, 1989, when the value of the trust principal is $1,000,000, T adds $1,000,000 to the trust. After this addition, the new allocation fraction is 0.6 ($1,200,000/$2,000,000). The numerator of the fraction is the value of that portion of trust assets that were subject to chapter 13 immediately prior to the addition (by reason of the first addition), $200,000 (.2 × $1,000,000), plus the value of the second transfer, $1,000,000, which equals $1,200,000. The denominator of the fraction, $2,000,000, is the total value of the trust assets immediately after the second transfer. Thus, 60 percent of the principal of the trust becomes subject to chapter 13.
On September 25, 1985, B possessed a general power of appointment over the assets of an irrevocable trust that had been created by T in 1980. Under the terms of the trust, B's power lapsed on July 20, 1987. For Federal gift tax purposes, B is treated as making a gift of ninety-five percent (100%—5%) of the value of the principal (see section 2514). However, because the entire trust was subject to the power of appointment, 100 percent (that portion of the trust subject to the power) of the assets of the trust are treated as a constructive addition. Thus, the entire amount of all generation-skipping transfers occurring pursuant to the trust instrument after July 20, 1987, are subject to chapter 13.
On March 1, 1985, T established an irrevocable trust as defined in paragraph (b)(1)(ii) of this section. Under the terms of the trust instrument, the trustee is required to distribute the entire income annually to T's child, C, for life, then to T's grandchild, GC, for life. GC has the power to appoint any or all of the trust assets to Trust 2 which is an irrevocable trust (as defined in paragraph (b)(1)(ii) of this section) that was established on August 1, 1985. The terms of Trust 2's governing instrument provide that the trustee shall pay income to T's great grandchild, GGC, for life. Upon GGC's death, the remainder is to be paid to GGC's issue. GGC was alive on March 1, 1985, when Trust 1 was created. C died on April 1, 1986. On July 1, 1987, GC exercised the power of appointment. The exercise of GC's power does not subject future transfers from Trust 2 to tax under chapter 13 because the exercise of the power in favor of Trust 2 does not suspend the vesting, absolute ownership, or power of alienation of an interest in property for a period, measured from the date of creation of Trust 1, extending beyond the life of GGC (a beneficiary under Trust 2 who was in being at the date of creation of Trust 1) plus a period of 21 years. The result would be the same if Trust 2 had been created after the effective date of chapter 13.
Assume the same facts as in Example 4, except that GGC was born on March 28, 1986. The valid exercise of GC's power in favor of Trust 2 causes the principal of Trust 1 to be subject to chapter 13, because GGC was not born until after the creation of Trust 1. Thus, such exercise may suspend the vesting, absolute ownership, or power of alienation of an interest in the trust principal for a period, measured from the date of creation of Trust 1, extending beyond the life of GGC (a beneficiary under Trust 2 who was not a life in being at the date of creation of Trust 1).
Prior to the effective date of chapter 13, GP established an irrevocable trust under which the trust income was to be paid to GP's child, C, for life. C was given a testamentary power to appoint the remainder in further trust for the benefit of C's issue. In default of C's exercise of the power, the remainder was to pass to charity. C died on February 3, 1995, survived by a child who was alive when GP established the trust. C exercised the power in a manner that validly extends the trust in favor of C's issue until the latter of May 15, 2064 (80 years from the date the trust was created), or the death of C's child plus 21 years. C's exercise of the power is a constructive addition to the trust because the exercise may extend the trust for a period longer than the permissible periods of either the life of C's child (a life in being at the creation of the trust) plus 21 years or a term not more than 90 years measured from the creation of the trust. On the other hand, if C's exercise of the power could extend the trust based only on the life of C's child plus 21 years or only for a term of 80 years from the creation of the trust (but not the later of the two periods) then the exercise of the power would not have been a constructive addition to the trust.
The facts are the same as in Example 6 except local law provides that the effect of C's exercise is to extend the term of the trust until May 15, 2064, whether or not C's child predeceases that date by more than 21 years. C's exercise is not a constructive addition to the trust because C exercised the power in a manner that cannot postpone or suspend vesting, absolute ownership, or power of alienation for a term of years that will exceed 90 years. The result would be the same if the effect of C's exercise is either to extend the term of the trust until 21 years after the death of C's child or to extend the term of the trust until the first to occur of May 15, 2064 or 21 years after the death of C's child.
On November 1, 1986, T executes a codicil to T's will removing one of the co-executors named in the will. Although the codicil may have the effect of lowering administrative costs and thus increasing the amount transferred, it is considered administrative in nature and thus does not cause generation-skipping transfers under the will to be subject to chapter 13.
On November 1, 1986, T executes a codicil to T's will revoking a bequest of $100,000 to C, a non-skip person (as defined under section 2613(b)) and causing that amount to be added to a residuary trust held for a skip person. The amendment is deemed to increase the amount of a generation-skipping transfer and prevents any transfers under the will from qualifying under paragraph (b)(2)(i) of this section. If, however, C dies before T and under local law the property would have been added to the residue in any event because the bequest would have lapsed, the codicil is not considered an amendment that increases the amount of a generation-skipping transfer.
T's will provided that an amount equal to the maximum allowable marital deduction would pass to T's spouse with the residue of the estate passing to a trust established for the benefit of skip persons. On October 23, 1986, the will is amended to provide that the marital share passing to T's spouse shall be the lesser of the maximum allowable marital deduction or the minimum amount that will result in no estate tax liability for T's estate. The amendment may increase the amount of a generation-skipping transfer. Therefore, any generation-skipping transfers under the will are subject to tax under chapter 13. If it becomes apparent that the amendment does not increase the amount of a generation-skipping transfer, a claim for refund may be filed with respect to any generation-skipping transfer tax that was paid within the period set forth in section 6511. For example, it would become apparent that the amendment did not result in an increase in the residue if it is subsequently determined that the maximum marital deduction and the minimum amount that will result in no estate tax liability are equal in amount.
T's will provided for the creation of two trusts for the benefit of skip persons. On November 1, 1986, T executed a codicil to the will specifically increasing the amount of a generation-skipping transfer under the will. All transfers made pursuant to the will or either of the trusts created thereunder are precluded from qualifying under the transition rule of paragraph (b)(2)(i) of this section and are subject to tax under chapter 13.
Assume that T in Example 4 later executes a second codicil deleting the increase to the generation-skipping transfer. Because the provision increasing a generation-skipping transfer does not become effective, it is not considered an amendment to a will in existence on October 22, 1986.
A became disabled, and T modified the trust on December 1, 1986, to increase A's share of the income. Since the amendment does not result in the creation of, or increase in the amount of, a generation-skipping transfer, transfers pursuant to the trust are not subject to chapter 13.
Assume that T amends the trust to add T's grandchild, D, as an income beneficiary. The trust will be subject to the provisions of chapter 13 because the amendment creates a generation-skipping transfer.
Assume that T amends the trust to provide that the issue of S are to take a one-fourth share of the principal per stirpes upon S's death. Because the distribution to be made upon S's death may involve skip persons, the amendment is considered an amendment that creates or increases the amount of a generation-skipping transfer until a determination can be made. Accordingly, any distributions from (or terminations of interests in) such trust are subject to chapter 13 until it is determined that no skip person has been added to the trust. At that time, a claim for refund may be filed within the period set forth in section 6511 with respect to any generation-skipping transfer tax that was paid.
T was mentally incompetent on October 22, 1986, and remained so until death in 1993. Prior to becoming incompetent, T created a revocable generation-skipping trust that was includible in T's gross estate. Prior to October 22, 1986, the appropriate court issued an order under which P, who was thereby charged with the care of T's property, had the power to modify or revoke the revocable trust. Although P exercised the power after October 22, 1986, and while T was incompetent, the power was not exercised in a manner that created, or increased the amount of, a generation-skipping transfer. Thus, the existence and exercise of P's power did not cause the trust to lose its exempt status under paragraph (b)(3) of this section. The result would be the same if the court order was issued after October 22, 1986.
Trustee's power to distribute principal authorized under trust instrument. In 1980, Grantor established an irrevocable trust (Trust) for the benefit of Grantor's child, A, A's spouse, and A's issue. At the time Trust was established, A had two children, B and C. A corporate fiduciary was designated as trustee. Under the terms of Trust, the trustee has the discretion to distribute all or part of the trust income to one or more of the group consisting of A, A's spouse or A's issue. The trustee is also authorized to distribute all or part of the trust principal to one or more trusts for the benefit of A, A's spouse, or A's issue under terms specified by the trustee in the trustee's discretion. Any trust established under Trust, however, must terminate 21 years after the death of the last child of A to die who was alive at the time Trust was executed. Trust will terminate on the death of A, at which time the remaining principal will be distributed to A's issue, per stirpes. In 2002, the trustee distributes part of Trust's principal to a new trust for the benefit of B and C and their issue. The new trust will terminate 21 years after the death of the survivor of B and C, at which time the trust principal will be distributed to the issue of B and C, per stirpes. The terms of the governing instrument of Trust authorize the trustee to make the distribution to a new trust without the consent or approval of any beneficiary or court. In addition, the terms of the governing instrument of the new trust do not extend the time for vesting of any beneficial interest in a manner that may postpone or suspend the vesting, absolute ownership or power of alienation of an interest in property for a period, measured from the date of creation of Trust, extending beyond any life in being at the date of creation of Trust plus a period of 21 years, plus if necessary, a reasonable period of gestation. Therefore, neither Trust nor the new trust will be subject to the provisions of chapter 13 of the Internal Revenue Code.
Trustee's power to distribute principal pursuant to state statute. In 1980, Grantor established an irrevocable trust (Trust) for the benefit of Grantor's child, A, A's spouse, and A's issue. At the time Trust was established, A had two children, B and C. A corporate fiduciary was designated as trustee. Under the terms of Trust, the trustee has the discretion to distribute all or part of the trust income or principal to one or more of the group consisting of A, A's spouse or A's issue. Trust will terminate on the death of A, at which time, the trust principal will be distributed to A's issue, per stirpes. Under a state statute enacted after 1980 that is applicable to Trust, a trustee who has the absolute discretion under the terms of a testamentary instrument or irrevocable inter vivos trust agreement to invade the principal of a trust for the benefit of the income beneficiaries of the trust, may exercise the discretion by appointing so much or all of the principal of the trust in favor of a trustee of a trust under an instrument other than that under which the power to invade is created, or under the same instrument. The trustee may take the action either with consent of all the persons interested in the trust but without prior court approval, or with court approval, upon notice to all of the parties. The exercise of the discretion, however, must not reduce any fixed income interest of any income beneficiary of the trust and must be in favor of the beneficiaries of the trust. Under state law prior to the enactment of the state statute, the trustee did not have the authority to make distributions in trust. In 2002, the trustee distributes one-half of Trust's principal to a new trust that provides for the payment of trust income to A for life and further provides that, at A's death, one-half of the trust remainder will pass to B or B's issue and one-half of the trust will pass to C or C's issue. Because the state statute was enacted after Trust was created and requires the consent of all of the parties, the transaction constitutes a modification of Trust. However, the modification does not shift any beneficial interest in Trust to a beneficiary or beneficiaries who occupy a lower generation than the person or persons who held the beneficial interest prior to the modification. In addition, the modification does not extend the time for vesting of any beneficial interest in Trust beyond the period provided for in the original trust. The new trust will terminate at the same date provided under Trust. Therefore, neither Trust nor the new trust will be subject to the provisions of chapter 13 of the Internal Revenue Code.
Construction of an ambiguous term in the instrument. In 1980, Grantor established an irrevocable trust for the benefit of Grantor's children, A and B, and their issue. The trust is to terminate on the death of the last to die of A and B, at which time the principal is to be distributed to their issue. However, the provision governing the termination of the trust is ambiguous regarding whether the trust principal is to be distributed per stirpes, only to the children of A and B, or per capita among the children, grandchildren, and more remote issue of A and B. In 2002, the trustee files a construction suit with the appropriate local court to resolve the ambiguity. The court issues an order construing the instrument to provide for per capita distributions to the children, grandchildren, and more remote issue of A and B living at the time the trust terminates. The court's construction resolves a bona fide issue regarding the proper interpretation of the instrument and is consistent with applicable state law as it would be interpreted by the highest court of the state. Therefore, the trust will not be subject to the provisions of chapter 13 of the Internal Revenue Code.
Change in trust situs. In 1980, Grantor, who was domiciled in State X, executed an irrevocable trust for the benefit of Grantor's issue, naming a State X bank as trustee. Under the terms of the trust, the trust is to terminate, in all events, no later than 21 years after the death of the last to die of certain designated individuals living at the time the trust was executed. The provisions of the trust do not specify that any particular state law is to govern the administration and construction of the trust. In State X, the common law rule against perpetuities applies to trusts. In 2002, a State Y bank is named as sole trustee. The effect of changing trustees is that the situs of the trust changes to State Y, and the laws of State Y govern the administration and construction of the trust. State Y law contains no rule against perpetuities. In this case, however, in view of the terms of the trust instrument, the trust will terminate at the same time before and after the change in situs. Accordingly, the change in situs does not shift any beneficial interest in the trust to a beneficiary who occupies a lower generation (as defined in section 2651) than the person or persons who held the beneficial interest prior to the transfer. Furthermore, the change in situs does not extend the time for vesting of any beneficial interest in the trust beyond that provided for in the original trust. Therefore, the trust will not be subject to the provisions of chapter 13 of the Internal Revenue Code. If, in this example, as a result of the change in situs, State Y law governed such that the time for vesting was extended beyond the period prescribed under the terms of the original trust instrument, the trust would not retain exempt status.
Division of a trust. In 1980, Grantor established an irrevocable trust for the benefit of his two children, A and B, and their issue. Under the terms of the trust, the trustee has the discretion to distribute income and principal to A, B, and their issue in such amounts as the trustee deems appropriate. On the death of the last to die of A and B, the trust principal is to be distributed to the living issue of A and B, per stirpes. In 2002, the appropriate local court approved the division of the trust into two equal trusts, one for the benefit of A and A's issue and one for the benefit of B and B's issue. The trust for A and A's issue provides that the trustee has the discretion to distribute trust income and principal to A and A's issue in such amounts as the trustee deems appropriate. On A's death, the trust principal is to be distributed equally to A's issue, per stirpes. If A dies with no living descendants, the principal will be added to the trust for B and B's issue. The trust for B and B's issue is identical (except for the beneficiaries), and terminates at B's death at which time the trust principal is to be distributed equally to B's issue, per stirpes. If B dies with no living descendants, principal will be added to the trust for A and A's issue. The division of the trust into two trusts does not shift any beneficial interest in the trust to a beneficiary who occupies a lower generation (as defined in section 2651) than the person or persons who held the beneficial interest prior to the division. In addition, the division does not extend the time for vesting of any beneficial interest in the trust beyond the period provided for in the original trust. Therefore, the two partitioned trusts resulting from the division will not be subject to the provisions of chapter 13 of the Internal Revenue Code.
Merger of two trusts. In 1980, Grantor established an irrevocable trust for Grantor's child and the child's issue. In 1983, Grantor's spouse also established a separate irrevocable trust for the benefit of the same child and issue. The terms of the spouse's trust and Grantor's trust are identical. In 2002, the appropriate local court approved the merger of the two trusts into one trust to save administrative costs and enhance the management of the investments. The merger of the two trusts does not shift any beneficial interest in the trust to a beneficiary who occupies a lower generation (as defined in section 2651) than the person or persons who held the beneficial interest prior to the merger. In addition, the merger does not extend the time for vesting of any beneficial interest in the trust beyond the period provided for in the original trust. Therefore, the trust that resulted from the merger will not be subject to the provisions of chapter 13 of the Internal Revenue Code.
Modification that does not shift an interest to a lower generation. In 1980, Grantor established an irrevocable trust for the benefit of Grantor's grandchildren, A, B, and C. The trust provides that income is to be paid to A, B, and C, in equal shares for life. The trust further provides that, upon the death of the first grandchild to die, one-third of the principal is to be distributed to that grandchild's issue, per stirpes. Upon the death of the second grandchild to die, one-half of the remaining trust principal is to be distributed to that grandchild's issue, per stirpes, and upon the death of the last grandchild to die, the remaining principal is to be distributed to that grandchild's issue, per stirpes. In 2002, A became disabled. Subsequently, the trustee, with the consent of B and C, petitioned the appropriate local court and the court approved a modification of the trust that increased A's share of trust income. The modification does not shift a beneficial interest to a lower generation beneficiary because the modification does not increase the amount of a GST transfer under the original trust or create the possibility that new GST transfers not contemplated in the original trust may be made. In this case, the modification will increase the amount payable to A who is a member of the same generation as B and C. In addition, the modification does not extend the time for vesting of any beneficial interest in the trust beyond the period provided for in the original trust. Therefore, the trust as modified will not be subject to the provisions of chapter 13 of the Internal Revenue Code. However, the modification increasing A's share of trust income is a transfer by B and C to A for Federal gift tax purposes.
Conversion of income interest into unitrust interest. In 1980, Grantor established an irrevocable trust under the terms of which trust income is payable to A for life and, upon A's death, the remainder is to pass to A's issue, per stirpes. In 2002, the appropriate local court approves a modification to the trust that converts A's income interest into the right to receive the greater of the entire income of the trust or a fixed percentage of the trust assets valued annually (unitrust interest) to be paid each year to A for life. The modification does not result in a shift in beneficial interest to a beneficiary who occupies a lower generation (as defined in section 2651) than the person or persons who held the beneficial interest prior to the modification. In this case, the modification can only operate to increase the amount distributable to A and decrease the amount distributable to A's issue. In addition, the modification does not extend the time for vesting of any beneficial interest in the trust beyond the period provided for in the original trust. Therefore, the trust will not be subject to the provisions of chapter 13 of the Internal Revenue Code.
Allocation of capital gain to income. In 1980, Grantor established an irrevocable trust under the terms of which trust income is payable to Grantor's child, A, for life, and upon A's death, the remainder is to pass to A's issue, per stirpes. Under applicable state law, unless the governing instrument provides otherwise, capital gain is allocated to principal. In 2002, the trust is modified to allow the trustee to allocate capital gain to the income. The modification does not shift any beneficial interest in the trust to a beneficiary who occupies a lower generation (as defined in section 2651) than the person or persons who held the beneficial interest prior to the modification. In this case, the modification can only have the effect of increasing the amount distributable to A, and decreasing the amount distributable to A's issue. In addition, the modification does not extend the time for vesting of any beneficial interest in the trust beyond the period provided for in the original trust. Therefore, the trust will not be subject to the provisions of chapter 13 of the Internal Revenue Code.
Administrative change to terms of a trust. In 1980, Grantor executed an irrevocable trust for the benefit of Grantor's issue, naming a bank and five other individuals as trustees. In 2002, the appropriate local court approves a modification of the trust that decreases the number of trustees which results in lower administrative costs. The modification pertains to the administration of the trust and does not shift a beneficial interest in the trust to any beneficiary who occupies a lower generation (as defined in section 2651) than the person or persons who held the beneficial interest prior to the modification. In addition, the modification does not extend the time for vesting of any beneficial interest in the trust beyond the period provided for in the original trust. Therefore, the trust will not be subject to the provisions of chapter 13 of the Internal Revenue Code.
In 1980, Grantor, a resident of State X, established an irrevocable trust for the benefit of Grantor's child, A, and A's issue. The trust provides that trust income is payable to A for life and upon A's death the remainder is to pass to A's issue, per stirpes. In 2002, State X amends its income and principal statute to define income as a unitrust amount of 4% of the fair market value of the trust assets valued annually. For a trust established prior to 2002, the statute provides that the new definition of income will apply only if all the beneficiaries who have an interest in the trust consent to the change within two years after the effective date of the statute. The statute provides specific procedures to establish the consent of the beneficiaries. A and A's issue consent to the change in the definition of income within the time period, and in accordance with the procedures, prescribed by the state statute. The administration of the trust, in accordance with the state statute defining income to be a 4% unitrust amount, will not be considered to shift any beneficial interest in the trust. Therefore, the trust will not be subject to the provisions of chapter 13 of the Internal Revenue Code. Further, under these facts, no trust beneficiary will be treated as having made a gift for federal gift tax purposes, and neither the trust nor any trust beneficiary will be treated as having made a taxable exchange for federal income tax purposes. Similarly, the conclusions in this example would be the same if the beneficiaries' consent was not required, or, if the change in administration of the trust occurred because the situs of the trust was changed to State X from a state whose statute does not define income as a unitrust amount or if the situs was changed to such a state from State X.
The facts are the same as in Example 11, except that in 2002, State X amends its income and principal statute to permit the trustee to make adjustments between income and principal when the trustee invests and manages the trust assets under the state's prudent investor standard, the trust describes the amount that shall or must be distributed to a beneficiary by referring to the trust's income, and the trustee after applying the state statutory rules regarding allocation of receipts between income and principal is unable to administer the trust impartially. The provision permitting the trustees to make these adjustments is effective in 2002 for trusts created at any time. The trustee invests and manages the trust assets under the state's prudent investor standard, and pursuant to authorization in the state statute, the trustee allocates receipts between the income and principal accounts in a manner to ensure the impartial administration of the trust. The administration of the trust in accordance with the state statute will not be considered to shift any beneficial interest in the trust. Therefore, the trust will not be subject to the provisions of chapter 13 of the Internal Revenue Code. Further, under these facts, no trust beneficiary will be treated as having made a gift for federal gift tax purposes, and neither the trust nor any trust beneficiary will be treated as having made a taxable exchange for federal income tax purposes. Similarly, the conclusions in this example would be the same if the change in administration of the trust occurred because the situs of the trust was changed to State X from a state whose statute does not authorize the trustee to make adjustments between income and principal or if the situs was changed to such a state from State X.
On December 31, 1980, T created an irrevocable trust having a principal of $100,000. Under the terms of the trust, the principal was to be held for the benefit of T's grandchild, GC. Pursuant to the terms of T's will, a document entitled to relief under the transition rule of paragraph (b)(2) of this section, the residue of the estate was paid to the trust. Because the addition to the trust was paid pursuant to the terms of an instrument (T's will) that is not subject to the provisions of chapter 13 because of paragraph (b)(2) of this section, the payment to the trust is not considered an addition to the principal of the trust. Thus, distributions to or for the benefit of GC, are not subject to the provisions of chapter 13.
T is the grantor of a trust that was irrevocable on September 25, 1985. T's will, which was executed before October 22, 1986, and not amended thereafter, provides that, upon T's death, the entire estate will pour over into T's trust. On October 1, 1985, T transfers $100,000 to the trust. While T's will otherwise qualifies for relief under the transition rule in paragraph (b)(2) of this section, the transition rule is not applicable unless T dies prior to January 1, 1987. Thus, if T dies after December 31, 1986, the transfer is treated as an addition to the trust for purposes of any distribution made from the trust after the transfer to the trust on October 1, 1985. If T dies before January 1, 1987, the entire trust (as well as any distributions from or terminations of interests in the trust prior to T's death) is exempt, under paragraph (b)(2) of this section, from chapter 13 because the $100,000 would have been added to the trust under a will that would have qualified under paragraph (b)(2) of this section. In either case, for any generation-skipping transfers made after the transfer to the trust on October 1, 1985, but before T's death, the $100,000 is treated as an addition to the trust and a proportionate amount of the trust is subject to chapter 13.
T and S are the settlors of separate revocable trusts with equal values. Both trusts were established for the benefit of skip persons (as defined in section 2613). S dies on December 1, 1985, and under the provisions of S's trust, the principal pours over into T's trust. If T dies before January 1, 1987, the entire trust is excluded under paragraph (b)(2) of this section from the operation of chapter 13. If T dies after December 31, 1986, the entire trust is subject to the generation-skipping transfer tax provisions because T's trust is not a trust described in paragraph (b)(1) or (2) of this section. In the latter case, the fact that S died before January 1, 1987, is irrelevant because the principal of S's trust was added to a trust that never qualified under the transition rules of paragraph (b)(1) or (2) of this section.
Assume the same facts as in Example 3, except upon the death of S on December 1, 1985, S's trust continues as an irrevocable trust and that the principal of T's trust is to be paid over upon T's death to S's trust. Again, if T dies before January 1, 1987, S's entire trust falls within the provisions of paragraph (b)(2) of this section. However, if T dies after December 31, 1986, the pour-over is considered an addition to the trust. Therefore, S's trust is not a trust excluded under paragraph (b)(2) of this section because an addition is made to the trust.
S, the spouse of the settlor of an irrevocable trust that was created in 1980, had, on September 25, 1985, a general power of appointment over the trust assets. The trust provides that should S fail to exercise the power of appointment the property is to remain in the trust. On October 21, 1986, S executed a will under which S failed to exercise the power of appointment. If S dies before January 1, 1987, without having exercised the power in a manner which results in the creation of, or increase in the amount of, a generation-skipping transfer (or amended the will in a manner that results in the creation of, or increase in the amount of, a generation-skipping transfer), transfers pursuant to the trust or the will are not subject to chapter 13 because the trust is an irrevocable trust and the will qualifies under paragraph (b)(2) of this section.
Assume the same facts as in Example 5, except on October 22, 1986, S did not have a will and that S dies after that date. Upon S's death, or upon the prior exercise or release of the power, the value of the entire trust is treated as having been distributed to S, and S is treated as having made an addition to the trust in the amount of the entire principal. Any distribution or termination pursuant to the trust occurring after S's death is subject to chapter 13. It is immaterial whether S's death occurs before January 1, 1987, since paragraph (b)(2) of this section is only applicable where a will or revocable trust was executed before October 22, 1986.
[T.D. 8644, 60 FR 66903, Dec. 27, 1995; 61 FR 29653, June 12, 1996, as amended at 61 FR 43656, Aug. 26, 1996; T.D. 8912, 65 FR 79738, Dec. 20, 2000; 66 FR 11108, Feb. 22, 2001; 66 FR 12834, Feb. 28, 2001; T.D. 9102, 69 FR 21, Jan. 2, 2004]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 2611 Generation-skipping transfer defined
- § 2652 Other definitions
- § 2038 Revocable transfers
- § 2042 Proceeds of life insurance
- § 2056 Bequests, etc., to surviving spouse
- § 2523 Gift to spouse
- § 2642 Inclusion ratio
- § 2612 Taxable termination; taxable distribution; direct skip
- § 2031 Definition of gross estate
- § 2053 Expenses, indebtedness, and taxes
- § 2041 Powers of appointment
- § 2207A Right of recovery in the case of certain marital deduction property
- § 2514 Powers of appointment
- § 2613 Skip person and non-skip person defined
- § 6511 Limitations on credit or refund
- § 2651 Generation assignment
Regulations it cites
- § 26.2652-1 Transferor defined; other definitions.
- § 20.2042-1 Proceeds of life insurance.
- § 26.2652-2 Special election for qualified terminable interest property.
- § 26.2654-1 Certain trusts treated as separate trusts.
- § 1.643(b)-1 Definition of income.
- § 26.2611-1 Generation-skipping transfer defined.
Cited by 3 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9102 (69 FR 21)
- Amended (66 FR 12834)
- Amended (66 FR 11108)
- Amended by T.D. 8912 (65 FR 79738)
- Amended (61 FR 43656)
- Amended (61 FR 29653)
- Issued by T.D. 8644 (60 FR 66903)
Where it sits in 26 CFR
- Subchapter B Estate and gift taxes
- Part 26 Generation-skipping transfer tax regulations under the tax reform act of 1986