
Treasury Regulations · 26 CFR
§ 41.4481-1. Imposition and computation of tax.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 4481
Cite as 26 CFR § 41.4481-1
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- May 23, 1985 by T.D. 8027
- Last amended
- October 29, 2014 by T.D. 9698
- Issued under
- 26 U.S.C. § 4481
- Length
- 2,265 words · about 10 min to read
- Cross-references
- cites 3 Code sections and 1 regulation; cited by 5
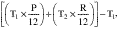
where:
T1 = Tax imposed for a full taxable period (or partial taxable period as determined under paragraph (c)(2) of this section) at the vehicle's previously reported taxable gross weight.
T2 = Tax imposed for the same taxable period as used in T1 at the vehicle's increased taxable gross weight.
P = The number of months in the taxable period during which the vehicle's taxable gross weight was as previously reported for such taxable period. This number does not include the month in which the vehicle's taxable gross weight increased.
R = The number of months remaining in the taxable period including the month in which the vehicle's taxable gross weight was increased.
If tax was imposed for a partial taxable period as determined under paragraph (c)(2) of this section, the additional tax is determined by substituting the number of months in such partial taxable period for “12” in the above formula.
In the taxable period beginning July 1, 1984, the first taxable use of a particular highway motor vehicle, a bus, having a taxable gross weight of 56,000 pounds, occurs on July 10, 1984, at which time the vehicle is registered in the name of X. A tax of $122 ($100 + $22) is imposed on X for the use of such vehicle for such taxable period.
On July 1, 1984, X has registered in his name a highway motor vehicle having a taxable gross weight of 60,000 pounds. The vehicle is in “dead storage” until August 10, 1984, at which time X starts using the vehicle on the public highways in carrying on his trucking business. On August 10, 1984, the vehicle is still registered in X's name. Since the first taxable use of this highway motor vehicle during the taxable period occurred on August 10, 1984, X is required to pay a tax of $192.50 ([$100 + (5 × $22)] × 11/12) for such taxable period.
(i) In July, X uses a vehicle that is registered in X's name and has a taxable gross weight of 70,000 pounds. The vehicle is not a logging vehicle. X pays the $430 of tax imposed by section 4481 for the taxable period. On September 2 of the same calendar year, X sells the vehicle to Y. X's tax is calculated under paragraph (c)(4)(ii) by multiplying the amount of tax that would be due for a full taxable period by a fraction that has as its numerator the number of months in the period from the first day of the month in which X's first taxable use of the highway motor vehicle occurs to and including the last day of the month in which the vehicle was sold, and as its denominator the number of months in the entire taxable period. Thus, X's tax for the period is $107.50 (3/12 of $430), and X may claim a credit or refund of $322.50 ($430.00−$107.50) in accordance with § 41.4481-1(c)(4)(v) after X sells the vehicle.
(ii) On September 23, Y uses the vehicle. Y is liable for tax on the use of the vehicle during the taxable period ending June 30 of the following calendar year. Y's tax is calculated under paragraph (c)(4)(vii) by multiplying the amount of tax that would be due for a full taxable period by a fraction that has as its numerator the number of months in the period from the first day of the month in which Y's first taxable use of the vehicle after the sale occurs (the first day of the month after such month if the first taxable use after the sale occurs in the month of the sale) through the end of the taxable period, and as its denominator the number of months in the entire taxable period. Y's first use of the vehicle occurs in the month of the sale. Accordingly, Y's tax is based on the number of months in the period from the first day of October (the month following the month of the first taxable use) through the end of June, and Y owes a section 4481 tax of $322.50 (9/12 of $430) for the taxable period.
Assume the same facts as in Example (3)(i), except that on September 2, X sells the vehicle to Dealer, a dealer in highway motor vehicles. X may claim a credit or refund of $322.50. Dealer operates the vehicle exclusively for the purpose of demonstration, which is not a “use” of the vehicle under § 41.4482(c)-1(c). On May 2 of the following calendar year, Dealer sells the vehicle to Y. Dealer does not owe a section 4481 tax and may not claim a refund. Y's first taxable use of the vehicle occurs on May 3. Y's first taxable use of the vehicle does not occur in the month of a sale upon which a credit or refund is allowable. Accordingly, Y's tax is calculated under paragraph (c)(2) by multiplying the amount of tax that would be due for a full taxable period by a fraction which has as its numerator the number of months in the taxable period beginning with the month of first taxable use and as its denominator the number of months in the entire taxable period. The numerator is the number of months in the period from the first day of May (the month of Y's first taxable use after the sale) through the end of June, and Y owes a section 4481 tax of $71.67 (2/12 of $430) for the taxable period.
[T.D. 8027, 50 FR 21246, May 23, 1985, as amended by T.D. 8159, 52 FR 33584, Sept. 4, 1987; T.D. 8177, 53 FR 6626, Mar. 2, 1988; T.D. 8879, 65 FR 17153, Mar. 31, 2000; T.D. 9698, 79 FR 64314, Oct. 29, 2014]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
Regulations it cites
Cited by 5 other regulations
- § 41.4481-2 Persons liable for tax.
- § 41.4482(b)-1 Definition of taxable gross weight.
- § 41.4483-2 Exemption for certain transit-type buses.
- § 41.4483-3 Exemption for trucks used for 5,000 or fewer miles and agricultural vehicles used for 7,500 or fewer miles on public highways.
- § 41.4483-4 Application of exemptions.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9698 (79 FR 64314)
- Amended by T.D. 8879 (65 FR 17153)
- Amended by T.D. 8177 (53 FR 6626)
- Amended by T.D. 8159 (52 FR 33584)
- Issued by T.D. 8027 (50 FR 21246)
Where it sits in 26 CFR
- Subchapter D Miscellaneous excise taxes
- Part 41 Excise tax on use of certain highway motor vehicles
- Subpart B Tax on Use of Certain Highway Motor Vehicles
Nearby sections
- § 41.4481-1 Imposition and computation of tax.
- § 41.4481-2 Persons liable for tax.
- § 41.4481-3 Registration.
- § 41.4482(a)-1 Definition of highway motor vehicle.
- § 41.4482(b)-1 Definition of taxable gross weight.