
Treasury Regulations · 26 CFR
§ 1.263A-2. Rules relating to property produced by the taxpayer.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 263A
Cite as 26 CFR § 1.263A-2
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- August 9, 1993 by T.D. 8482
- Last amended
- January 5, 2021 by T.D. 9942
- Issued under
- 26 U.S.C. § 263A
- Length
- 12,857 words · about 56 min to read
- Cross-references
- cites 7 Code sections and 12 regulations; cited by 12
Y is a manufacturer of automobiles. During the taxable year Y produces numerous substantially identical dies and molds using standardized designs and assembly line techniques. The dies and molds have a 3-year applicable recovery period for purposes of section 168(c). Y uses the dies and molds to produce or process particular automobile components and does not hold them for sale. The dies and molds are produced on a routine and repetitive basis in the ordinary course of Y's business for purposes of this paragraph because the dies and molds are both mass-produced and have a recovery period of not longer than 3 years.
Z is an electric utility that regularly manufactures and installs identical poles that are used in transmitting and distributing electricity. The poles have a 20-year applicable recovery period for purposes of section 168(c). The poles are not produced on a routine and repetitive basis in the ordinary course of Z's business for purposes of this paragraph because the poles have an applicable recovery period that is longer than 3 years.
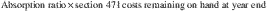
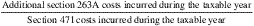
(i) Taxpayer J uses the FIFO method of accounting for inventories. J's beginning inventory for 1994 (all of which is sold during 1994) is $2,500,000 (consisting of $2,000,000 of section 471 costs and $500,000 of additional section 263A costs). During 1994, J incurs $10,000,000 of section 471 costs and $1,000,000 of additional section 263A costs. J's additional section 263A costs include capitalizable mixed service costs computed under the simplified service cost method as well as other allocable costs. J's section 471 costs remaining in ending inventory at the end of 1994 are $3,000,000. J computes its absorption ratio for 1994, as follows:
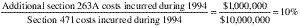
(ii) Under the simplified production method, J determines the additional section 263A costs allocable to its ending inventory by multiplying the absorption ratio by the section 471 costs remaining in its ending inventory:
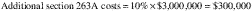
(iii) J adds this $300,000 to the $3,000,000 of section 471 costs remaining in its ending inventory to calculate its total ending inventory of $3,300,000. The balance of J's additional section 263A costs incurred during 1994, $700,000, ($1,000,000 less $300,000) is taken into account in 1994 as part of J's cost of goods sold.
(i) Taxpayer K uses a dollar-value LIFO inventory method. K's beginning inventory for 1994 is $2,500,000 (consisting of $2,000,000 of section 471 costs and $500,000 of additional section 263A costs). During 1994, K incurs $10,000,000 of section 471 costs and $1,000,000 of additional section 263A costs. K's 1994 LIFO increment is $1,000,000 ($3,000,000 of section 471 costs in ending inventory less $2,000,000 of section 471 costs in beginning inventory).
(ii) To determine the additional section 263A costs allocable to its ending inventory, K multiplies the 10% absorption ratio ($1,000,000 of additional section 263A costs divided by $10,000,000 of section 471 costs) by the $1,000,000 LIFO increment. Thus, K's additional section 263A costs allocable to its ending inventory are $100,000 ($1,000,000 multiplied by 10%). This $100,000 is added to the $1,000,000 to determine a total 1994 LIFO increment of $1,100,000. K's ending inventory is $3,600,000 (its beginning inventory of $2,500,000 plus the $1,100,000 increment). The balance of K's additional section 263A costs incurred during 1994, $900,000 ($1,000,000 less $100,000), is taken into account in 1994 as part of K's cost of goods sold.
(iii) In 1995, K sells one-half of the inventory in its 1994 LIFO increment. K must include in its cost of goods sold for 1995 the amount of additional section 263A costs relating to this inventory, $50,000 (one-half of the tional section 263A costs capitalized in 1994 ending inventory, or $100,000).
(i) Taxpayer U begins its business in 1994 and adopts the LIFO inventory method. During 1994, L incurs $10,000 of section 471 costs and $1,000 of additional section 263A costs. At the end of 1994, L's ending inventory includes $3,000 of section 471 costs contained in three LIFO pools (X, Y, and Z) as shown below. Under the simplified production method, L computes its absorption ratio and inventory for 1994 as follows:
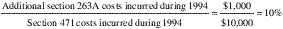
| Total | X | Y | Z | |
|---|---|---|---|---|
| 1994: | ||||
| Ending section 471 costs | $3,000 | $1,600 | $600 | $800 |
| Additional section 263A costs (10%) | 300 | 160 | 60 | 80 |
| 1994 ending inventory | $3,300 | $1,760 | $660 | $880 |
(ii) During 1995, L incurs $2,000 of section 471 costs as shown below and $400 of additional section 263A costs. Moreover, L sells goods from pools X, Y, and Z having a total cost of $1,000. L computes its absorption ratio and inventory for 1995:
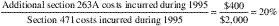
| Total | X | Y | Z | |
|---|---|---|---|---|
| 1995: | ||||
| Beginning section 471 costs | $3,000 | $1,600 | $600 | $800 |
| 1995 section 471 costs | 2,000 | 1,500 | 300 | 200 |
| Section 471 cost of goods sold | (1,000) | (300) | (300) | (400) |
| 1995 ending section 471 costs | $4,000 | $2,800 | $600 | $600 |
| Consisting of: | ||||
| 1994 layer | $2,800 | $1,600 | $600 | $600 |
| 1995 layer | 1,200 | 1,200 | ||
| $4,000 | $2,800 | $600 | $600 | |
| Additional section 263A costs: | ||||
| 1994 (10%) | $280 | $160 | $60 | $60 |
| 1995 (20%) | 240 | 240 | ||
| $520 | $400 | $60 | $60 | |
| 1995 ending inventory | $4,520 | $3,200 | $660 | $660 |
(iii) In 1995, L experiences a $200 decrement in pool Z. Thus, L must charge the additional section 263A costs incurred in prior years applicable to the decrement to 1995's cost of goods sold. To do so, L determines a ratio by dividing the decrement by the section 471 costs in the 1994 layer ($200 divided by $800, or 25%). L then multiplies this ratio (25%) by the additional section 263A costs in the 1994 layer ($80) to determine the additional section 263A costs applicable to the decrement ($20). Therefore, $20 is taken into account by L in 1995 as part of its cost of goods sold ($80 multiplied by 25%).
paragraph (b)(3)(ii) of this section) for its three most recent consecutive taxable years. This method is not available to a taxpayer that is deemed to have zero additional section 263A costs under paragraph (b)(3)(iv) of this section. The historic absorption ratio is used in lieu of an actual absorption ratio computed under paragraph (b)(3)(ii) of this section and is based on costs capitalized by a taxpayer during its test period. If elected, the historic absorption ratio must be used for each taxable year within the qualifying period described in paragraph (b)(4)(ii)(C) of this section.
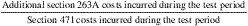
(B) Test period—(1) In general. The test period is generally the three taxable-year period immediately prior to the taxable year that the historic absorption ratio is elected.
(i) Taxpayer M uses the FIFO method of accounting for inventories and for 1994 elects to use the historic absorption ratio with the simplified production method. After recomputing its additional section 263A costs in accordance with the transition rules of paragraph (b)(4)(v) of this section, M identifies the following costs incurred during the test period:
1991:
Add'l section 263A costs—$100
Section 471 costs—$3,000
1992:
Add'l section 263A costs—$200
Section 471 costs—$4,000
1993:
Add'l section 263A costs—$300
Section 471 costs—$5,000
(ii) Therefore, M computes a 5% historic absorption ratio determined as follows:
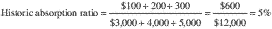
(iii) In 1994, M incurs $10,000 of section 471 costs of which $3,000 remain in inventory at the end of the year. Under the simplified production method using a historic absorption ratio, M determines the additional section 263A costs allocable to its ending inventory by multiplying its historic absorption ratio (5%) by the section 471 costs remaining in its ending inventory as follows:
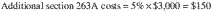
(iv) To determine its ending inventory under section 263A, M adds the additional section 263A costs allocable to ending inventory to its section 471 costs remaining in ending inventory ($3,150 = $150 + $3,000). The balance of M's additional section 263A costs incurred during 1994 is taken into account in 1994 as part of M's cost of goods sold.
(v) M's qualifying period ends with the close of its 1998 taxable year. Therefore, 1999 is a recomputation year in which M must compute its actual absorption ratio. M determines its actual absorption ratio for 1999 to be 5.25% and compares that ratio to its historic absorption ratio (5.0%). Therefore, M must continue to use its historic absorption ratio of 5.0% throughout an extended qualifying period, 1999 through 2004 (the recomputation year and the following five taxable years).
(vi) If, instead, M's actual absorption ratio for 1999 were not between 4.5% and 5.5%, M's qualifying period would end and M would be required to compute a new historic absorption ratio with reference to an updated test period of 1999, 2000, and 2001. Once M's historic absorption ratio is determined for the updated test period, it would be used for a new qualifying period beginning in 2002.
Additional section 263A costs = (8% × $1,000,000) + (10.22% × $2,000,000) = $284,400
| Reference | Amount | |
|---|---|---|
| Beginning Inventory: | ||
| Direct material costs | a | $ 400,000 |
| Property acquired for resale | b | 100,000 |
| Pre-production section 471 costs | c = a + b | 500,000 |
| Production section 471 costs | d | 1,500,000 |
| Additional section 263A costs | e | 500,000 |
| Total | f = c d + e | 2,500,000 |
| Incurred During 2018: | ||
| Direct material costs | g | 1,900,000 |
| Property acquired for resale | h | 600,000 |
| Pre-production section 471 costs | i = g + h | 2,500,000 |
| Production section 471 costs | j | 7,500,000 |
| Pre-production additional section 263A costs | k | 200,000 |
| Production additional section 263A costs | l | 800,000 |
| Total | m = i + j + k + l | 11,000,000 |
| Ending Inventory: | ||
| Direct material costs | n | 800,000 |
| Property acquired for resale | o | 200,000 |
| Pre-production section 471 costs | p = n + o | 1,000,000 |
| Production section 471 costs | q | 2,000,000 |
| Section 471 costs | r = p + q | 3,000,000 |
| Additional section 263A costs allocable to ending inventory | s = v + z | 284,400 |
| Total | t = r + s | 3,284,400 |
| Modified Simplified Production Method: | ||
| Pre-production additional section 263A costs | k | 200,000 |
| Pre-production section 471 costs | i | 2,500,000 |
| Pre-production absorption ratio | u = k / i | 8.00% |
| Pre-production section 471 costs remaining on hand at year end | p | 1,000,000 |
| Pre-production additional section 263A costs allocable to ending inventory | v = u * p | 80,000 |
| Production additional section 263A costs | l | 800,000 |
| Residual pre-production additional section 263A costs | w = k−(u * p) | 120,000 |
| Production section 471 costs | j | 7,500,000 |
| Direct materials adjustment | x = a + g−n | 1,500,000 |
| Production absorption ratio | y = (l + w) / (j + x) | 10.22% |
| Production section 471 costs remaining on hand at year end | q | 2,000,000 |
| Production additional section 263A costs allocable to ending inventory | z = y * q | 204,400 |
| Summary: | ||
| Pre-production additional section 263A costs allocable to ending inventory | v | 80,000 |
| Production additional section 263A costs allocable to ending inventory | z | 204,400 |
| Additional section 263A costs allocable to ending inventory | s | 284,400 |
| Section 471 costs | r | 3,000,000 |
| Total Ending Inventory | t | 3,284,400 |
Additional section 263A costs = (8.00% × $1,000,000) + (10.11% × $2,000,000) = $282,200
| 2018 | 2019 | 2020 | |
|---|---|---|---|
| Pre-production additional section 263A costs | $100 | $200 | $300 |
| Production additional section 263A costs | 200 | 350 | 450 |
| Pre-production section 471 costs | 2,000 | 2,500 | 3,000 |
| Production section 471 costs | 2,500 | 3,500 | 4,000 |
| Residual pre-production additional section 263A costs | 60 | 136 | 220 |
| Direct materials adjustments | 2,700 | 3,200 | 3,700 |
[T.D. 8482, 58 FR 42219, Aug. 9, 1993, as amended by 59 FR 3318, 3319, Jan. 21, 1994; T.D. 8584, 59 FR 67197, Dec. 29, 1994; T.D. 9217, 70 FR 44469, Aug. 3, 2005; T.D. 9318, 72 FR 14677, Mar. 29, 2007; T.D. 9652, 79 FR 2097, Jan. 13, 2014; T.D. 9843, 83 FR 58491, Nov. 20, 2018; T.D. 9942, 86 FR 266, Jan. 5, 2021]
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 263A Capitalization and inclusion in inventory costs of certain expenses
- § 448 Limitation on use of cash method of accounting
- § 263 Capital expenditures
- § 168 Accelerated cost recovery system
- § 471 General rule for inventories
- § 481 Adjustments required by changes in method of accounting
- § 446 General rule for methods of accounting
Regulations it cites
- § 1.263A-1 Uniform capitalization of costs.
- § 1.448-2 Limitation on the use of the cash receipts and disbursements method of accounting for taxable years beginning after December 31, 2017.
- § 1.174-2 Definition of research and experimental expenditures.
- § 1.263A-3 Rules relating to property acquired for resale.
- § 1.471-11 Inventories of manufacturers.
- § 1.263A-10 Unit of property.
- § 1.46-3 Qualified investment.
- § 1.471-3 Inventories at cost.
- § 1.472-8 Dollar-value method of pricing LIFO inventories.
- § 1.6001-1 Records.
- § 1.263A-7 Changing a method of accounting under section 263A.
- § 1.446-1 General rule for methods of accounting.
Cited by 12 other regulations
- § 1.162-3 Materials and supplies.
- § 1.263(a)-1 Capital expenditures; in general.
- § 1.263(a)-2 Amounts paid to acquire or produce tangible property.
- § 1.263A-0 Outline of regulations under section 263A.
- § 1.263A-1 Uniform capitalization of costs.
- § 1.263A-3 Rules relating to property acquired for resale.
- § 1.263A-8 Requirement to capitalize interest.
- § 1.263A-9 The avoided cost method.
- § 1.451-3 Timing of income inclusion for taxpayers with an applicable financial statement using an accrual method of accounting.
- § 1.451-8 Advance payments for goods, services, and certain other items.
- § 1.460-5 Cost allocation rules.
- § 1.471-3 Inventories at cost.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9942 (86 FR 266)
- Amended by T.D. 9843 (83 FR 58491)
- Amended by T.D. 9652 (79 FR 2097)
- Amended by T.D. 9318 (72 FR 14677)
- Amended by T.D. 9217 (70 FR 44469)
- Amended by T.D. 8584 (59 FR 67197)
- Date not givenAmended (59 FR 3318)
- Issued by T.D. 8482 (58 FR 42219)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Items Not Deductible
Nearby sections
- § 1.263(e)-1 Expenditures in connection with certain railroad rolling stock.
- § 1.263(f)-1 Reasonable repair allowance.
- § 1.263A-0 Outline of regulations under section 263A.
- § 1.263A-1 Uniform capitalization of costs.
- § 1.263A-2 Rules relating to property produced by the taxpayer.
- § 1.263A-3 Rules relating to property acquired for resale.
- § 1.263A-4 Rules for property produced in a farming business.
- § 1.263A-7 Changing a method of accounting under section 263A.
- § 1.263A-8 Requirement to capitalize interest.