
Treasury Regulations · 26 CFR
§ 1.861-10. Special allocations of interest expense.
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 861
Cite as 26 CFR § 1.861-10
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- April 15, 1992 by T.D. 8410
- Last amended
- January 4, 2022 by T.D. 9959
- Issued under
- 26 U.S.C. § 861
- Length
- 5,673 words · about 25 min to read
- Defines
- 1 term
- Cross-references
- cites 4 Code sections and 9 regulations; cited by 3
(i) Facts. X, a domestic corporation, elects to apply this paragraph (e) to its 1990 tax year. X has a calendar taxable year and apportions its interest expense on the basis of the tax book value of its assets. In 1990, X incurred deductible third-party interest expense of $24,960 on an average amount of indebtedness (determined on the basis of beginning-of-year and end-of-year amounts) of $249,600. X manufactures widgets, all of which are sold in the United States. X owns all of the stock of Y, a controlled foreign corporation that also has a calendar taxable year and is also engaged in the manufacture and sale of widgets. Y has no earnings and profits or deficit of earnings and profits attributable to taxable years prior to 1987. X's total assets and their average tax book values (determined on the basis of beginning-of-year and end-of-year tax book values) for 1990 are:
| Asset | Average tax book value |
|---|---|
| Plant and equipment | $315,000 |
| Corporate headquarters | 60,000 |
| Y stock | 75,000 |
| Y note | 50,000 |
| Total | 500,000 |
Y had $25,000 of income before the deduction of any interest expense. Of this total, $5,000 is high withholding tax interest income. The remaining $20,000 is derived from widget sales, and constitutes foreign source general limitation income. Assume that Y has no deductions from gross income other than interest expense. During 1990, Y paid $5,000 of interest expense to X on the Y note and $10,000 of interest expense to third parties, giving Y total interest expense of $15,000. X elects pursuant to § 1.861-9T to apportion Y's interest expense under the gross income method prescribed in section 1.861-9T (j).
(ii) Step 1: Using a beginning and end of year average, X (the U.S. shareholder) held the following average amounts of indebtedness of Y and Y had the following average asset values:
| 1985 | 1986-88 | 1989 | 1990 | |
|---|---|---|---|---|
| (A) Related group indebtedness | $11,000 | 24,000 | 26,000 | 50,000 |
| (B) Average Value of Assets of Related CFC | 100,000 | 200,000 | 200,000 | 250,000 |
| (C) Related Group Debt-to-Asset Ratio | .11 | .12 | .13 | .20 |
(1) X's “foreign base period ratio” for 1990, an average of its ratios of related group indebtedness to related group assets for 1985 through 1989, is:
(.11 + .12 + .12 + .12 + .13) / 5 = .12
(2) X's “allowable related group indebtedness” for 1990 is:
$250,000 × .12 = $30,000.
(3) X's “excess related group indebtedness” for 1990 is:
$50,000 − $30,000 = $20,000
X's related group indebtedness of $50,000 for 1990 is greater than its allowable related group indebtedness of $24,000 for 1989 (assuming a foreign base period ratio in 1989 of .12), and X's related group debt-to-asset ratio for 1990 is .20, which is greater than the ratio of .10 described in paragraph (e)(2)(vii)(B) of this section. Therefore, X's excess related group indebtedness for 1990 remains at $20,000.
(iii) Step 2: Using a beginning and end of year average, X has the following average amounts of U.S. and foreign indebtedness and average asset values:
| 1985 | 1986 | 1987 | 1988 | 1989 | 1990 | |
|---|---|---|---|---|---|---|
| (1) | $231,400 | 225,000 | 225,000 | 225,000 | 220,800 | 249,600 |
| (2) | 445,000 | 450,000 | 450,000 | 450,000 | 460,000 | 480,000 |
| (a) | ||||||
| (3) | .52 | .50 | .50 | .50 | .48 | .52 |
(1) U.S. and foreign indebtedness
(2) Average value of assets of U.S. shareholder
(3) Debt-to-Asset ratio of U.S. shareholder
(a) [500,000-20,000 (excess related group indebtedness determined in Step 1)]
X's “U.S. base period ratio” for 1990 is:
(.52 + .50 + .50 + .50 + .48) / 5 = .50
X's “allowable indebtedness” for 1990 is:
$480,000 × .50 = $240,000
X's “excess U.S. shareholder indebtedness” for 1990 is:
$249,000 − $240,000 = $9,600
X's debt-to-asset ratio for 1990 is .52, which is greater than the ratio of .10 described in paragraph (e)(3)(vii) of this section. Therefore, X's excess U.S. shareholder indebtedness for 1990 remains at $9,600.
(iv) Step 3: (a) Since X's excess U.S. shareholder indebtedness of $9,600 is less than its excess related group indebtedness of $20,000, X's allocable related group indebtedness for 1990 is $9,600. The amount of interest received by X during 1990 on allocable related group indebtedness is:
$5,000 × $9,600 / $50,000 = $960
(b) Therefore, $960 of X's third party interest expense ($24,960) shall be allocated among various separate limitation categories in proportion to the relative average amounts of Y obligations held by X in each such category. The amount of Y obligations in each limitation category is determined in the same manner as the stock of Y would be attributed under the rules of § 1.861-12T(c)(3). Since Y's interest expense is apportioned under the gross income method prescribed in § 1.861-9T (j), the Y stock must be characterized under the gross income method described in § 1.861-12T(c)(3)(iii). Y's gross income net of interest expense is determined as follows:
Foreign source high withholding tax interest income
= $5,000 − [($15,000) multiplied by ($5,000)/($5,000 + $20,000)]
= $2,000
and
Foreign source general limitation income
= $20,000 − [($15,000) multiplied by ($20,000)/($5,000 + $20,000)]
= $8,000.
(c) Therefore, $192 [($960 × $2,000/($2,000 + $8,000)] of X's third party interest expense is allocated to foreign source high withholding tax interest income and $768 [$960 × $8,000/($2,000 + $8,000)] is allocated to foreign source general limitation income.
(v) As a result of these direct allocations, for purposes of apportioning X's remaining interest expense under § 1.861-9T, the value of X's assets generating foreign source general limitation income is reduced by the principal amount of indebtedness the interest on which is directly allocated to foreign source general limitation income ($7,680), and the value of X's assets generating foreign source high withholding tax interest income is reduced by the principal amount of indebtedness the interest on which is directly allocated to foreign source high withholding tax interest income ($1,920), determined as follows:
Reduction of X's assets generating foreign source general limitation income:
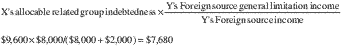
Reduction of X's assets generating foreign source high withholding tax interest income:
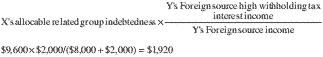
[T.D. 8410, 57 FR 13022, Apr. 15, 1992; 57 FR 28012, June 23, 1992, as amended by T.D. 9882, 84 FR 69068, Dec. 17, 2019; T.D. 9959, 87 FR 326, Jan. 4, 2022]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 904 Limitation on credit
- § 957 Controlled foreign corporations; United States persons
- § 864 Definitions and special rules
- § 355 Distribution of stock and securities of a controlled corporation
Regulations it cites
- § 1.861-9 Allocation and apportionment of interest expense and rules for asset-based apportionment.
- § 1.861-10T Special allocations of interest expense (temporary).
- § 1.861-9T Allocation and apportionment of interest expense (temporary).
- § 1.861-11T Special rules for allocating and apportioning interest expense of an affiliated group of corporations (temporary).
- § 1.861-8T Computation of taxable income from sources within the United States and from other sources and activities (temporary).
- § 1.861-12T Characterization rules and adjustments for certain assets (temporary).
- § 1.1502-75 Filing of consolidated returns.
- § 1.163(j)-1 Definitions.
- § 1.163(j)-10 Allocation of interest expense, interest income, and other items of expense and gross income to an excepted trade or business.
Cited by 3 other regulations
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9959 (87 FR 326)
- Amended by T.D. 9882 (84 FR 69068)
- Amended (57 FR 28012)
- Issued by T.D. 8410 (57 FR 13022)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Determination of Sources of Income
Nearby sections
- § 1.861-8 Computation of taxable income from sources within the United States and from other sources and activities.
- § 1.861-8T Computation of taxable income from sources within the United States and from other sources and activities (temporary).
- § 1.861-9 Allocation and apportionment of interest expense and rules for asset-based apportionment.
- § 1.861-9T Allocation and apportionment of interest expense (temporary).
- § 1.861-10 Special allocations of interest expense.
- § 1.861-10T Special allocations of interest expense (temporary).
- § 1.861-11 Special rules for allocating and apportioning interest expense of an affiliated group of corporations.
- § 1.861-11T Special rules for allocating and apportioning interest expense of an affiliated group of corporations (temporary).
- § 1.861-12 Characterization rules and adjustments for certain assets.