
Treasury Regulations · 26 CFR
§ 1.861-11T. Special rules for allocating and apportioning interest expense of an affiliated group of corporations (temporary).
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 861
Cite as 26 CFR § 1.861-11T
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- September 14, 1988 by T.D. 8228
- Last amended
- December 17, 2019 by T.D. 9882
- Issued under
- 26 U.S.C. § 861
- Length
- 5,711 words · about 25 min to read
- Defines
- 7 terms
- Cross-references
- cites 9 Code sections and 6 regulations; cited by 10
| Analysis of the YZ group assets | |
| Adjusted basis of assets of the YZ group that generate foreign source financial services income (excluding stock of foreign subsidiaries not included in the YZ affiliated group) | $200,000 |
| Z's basis in the C stock (not adjusted by the allocable amount of C's earnings and profits because Z owns less than 10 percent of the stock) which would be considered to generate passive income in the hands of a nonfinancial services entity but is considered to generate financial services income when in the hands of Z, a financial services entity | $100,000 |
| Y's basis in the B stock (adjusted by the allocable amount of B's earnings and profits) which generates dividends subject to a separate limitation for B dividends | $100,000 |
| Adjusted basis of assets of the YZ group that generate U.S. source income | $600,000 |
| Total assets | $1,000,000 |
| Analysis of the XZ1 group assets | |
| Adjusted basis of assets of the XZ1 group that generate foreign source general limitation income | $500,000 |
| Adjusted basis of assets of the XZ1 group other than A stock that generate domestic source income | $1,900,000 |
| X's basis in the A stock adjusted by the allocable amount of A's earnings and profits | $100,000 |
| Total domestic assets | $2,000,000 |
| Total assets | $2,500,000 |
To gross financial services income from sources outside the United States:
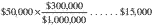
To gross income subject to a separate limitation for dividends from B:
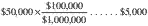
To gross income from sources inside the United States:
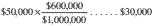
The XZ1 group would apportion its interest expense as follows:
To gross general limitation income from sources outside the United States:
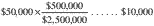
To gross income from sources inside the United States:
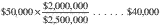
X, a domestic corporation, is the parent of Y, a domestic corporation. X and Y were organized after January 1, 1987, and constitute an affiliated group within the meaning of paragraph (d)(1) of this section. Among X's assets is the note of Y for the amount of $100,000. Because X and Y are members of an affiliated group, Y's note does not constitute an asset for purposes of apportionment. The apportionment fractions for the relevant tax year of the XY group are 50 percent domestic, 40 percent foreign general, and 10 percent foreign passive. Y deducts its related person interest payment using those apportionment fractions. Of the $10,000 in related person interest income received by X, $5,000 consists of domestic source income, $4,000 consists of foreign general limitation income, and $1,000 consists of foreign passive income.
X is a domestic corporation organized after January 1, 1987. X owns all the stock of Y, a domestic corporation. On June 1, 1987, X loans $100,000 to Z, an unrelated person. On June 2, 1987, Z makes a loan to Y with terms substantially similar to those of the loan from X to Z. Based on the facts and circumstances of the transaction, it is determined that Z would not have made the loan to Y on the same terms if X had not made the loan to Z. Because the transaction constitutes a back-to-back loan, as defined in paragraph (e)(3) of this section, the Commissioner may require, in his discretion, that neither the note of Y nor the note of Z may be considered an asset of X for purposes of this section.
Such adjustments shall be accomplished, in accordance with paragraph (g)(2) of this section, without changing the total taxable income of any member and before the application of section 904(f). Section 904(f) (including section 904(f)(5)) does not apply to a loss created through the apportionment of interest expense to the extent that the loss is eliminated pursuant to paragraph (g)(2)(ii) of this section. For purposes of this section, the terms “limitation adjustment” and “recharacterization” mean the recharacterization of income in one limitation category as income in another limitation category.
(i) Facts. X, a domestic corporation, is the parent of domestic corporations Y and Z. X, Y, and Z were organized after January 1, 1987, constitute an affiliated group within the meaning of paragraph (d)(1) of this section, but do not file a consolidated return. The XYZ group apportions its interest expense on the basis of the fair market value of its assets. X, Y, and Z have the following assets, interest expense, and taxable income before apportioning interest expense:
| Assets | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 2,000.00 | 0 | 1,000.00 | 3,000.00 |
| Foreign Passive | 0 | 50.00 | 50.00 | 100.00 |
| Foreign General | 0 | 700.00 | 200.00 | 900.00 |
| Interest expense | 48.00 | 12.00 | 80.00 | 140.00 |
| Taxable Income (pre-interest): | ||||
| Domestic | 100.00 | 0 | 63.00 | 163.00 |
| Foreign Passive | 0 | 5.00 | 5.00 | 10.00 |
| Foreign General | 0 | 60.00 | 35.00 | 95.00 |
(ii) Step 1: Computation of consolidated taxable income. Each member of the XYZ group apportions its interest expense according to group apportionment ratios determined under the asset method described in § 1.861-9T(f), yielding the following results:
| Apportioned interest expense | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 36.00 | 9.00 | 60.00 | 105.00 |
| Foreign Passive | 1.20 | 0.30 | 2.00 | 3.50 |
| Foreign General | 10.80 | 2.70 | 18.00 | 31.50 |
| Total | 48.00 | 12.00 | 80.00 | 140.00 |
The members of the group then compute taxable income within each category by deducting the apportioned interest expense from the amounts of pre-interest taxable income specified in the facts in paragraph (i), yielding the following results:
| Taxable income | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 64.00 | 9.00 | 3.00 | 58.00 |
| Foreign Passive | −1.20 | 4.70 | 3.00 | 6.50 |
| Foreign General | −10.80 | 57.30 | 17.00 | 63.50 |
| Total | 52.00 | 53.00 | 23.00 | 128.00 |
(iii) Step 2: Loss offset adjustments. Because X and Y have losses created through apportionment, these losses must be eliminated by reducing taxable income of the member in other limitation categories. Because X has a total of $12 in apportionment losses and because it has only one limitation category with income (i.e., domestic), domestic income must be reduced by $12, thus eliminating its apportionment losses. Because Y has a total of $9 in apportionment losses and because it has two limitation categories with income (i.e., foreign passive and foreign general limitation), the income in these two limitation categories must be reduced on a pro rata basis in order to eliminate its apportionment losses. In summary, the following adjustments are required:
| Loss offset adjustments | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | −12.00 | + 9.00 | 0 | −3.00 |
| Foreign Passive | + 1.20 | −0.68 | 0 | + 0.52 |
| Foreign General | + 10.80 | −8.32 | 0 | + 2.48 |
These adjustments yield the following adjusted taxable income figures:
| Adjusted taxable income | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 52.00 | 0 | 3.00 | 55.00 |
| Foreign Passive | 0 | 4.02 | 3.00 | 7.02 |
| Foreign General | 0 | 48.98 | 17.00 | 65.98 |
| Total | 52.00 | 53.00 | 23.00 | 128.00 |
(iv) Step 3: Determination of amount subject to recharacterization. The adjustments performed under Step 2 led to a change in the group's taxable income within each limitation category. The total loss offset adjustments column shown in paragraph (iii) above shows the net deviations between Step 1 and 2.
(v) Step 4: Recharacterization. The loss offset adjustments yield a positive change in the foreign passive and the foreign general limitation categories. Y and Z both have income in these limitation categories. Accordingly, the income of Y and Z in each of these limitation categories must be reduced on a pro rata basis (by reference to the adjusted taxable income figures) to the extent of the positive change in each limitation category. The total positive change in the foreign passive limitation category is $0.52. The adjusted taxable income of Y in the foreign passive limitation category is $4.02 and the adjusted taxable income of Z in the foreign passive limitation category is $3. Therefore, $0.30 is drawn from Y and $0.22 is drawn from Z. The total positive change in the foreign general limitation category is $2.48. The adjusted taxable income of Y in the foreign general limitation category is $48.98, and the adjusted taxable income of Z in the foreign general limitation category is $17. Therefore, $1.84 is drawn from Y and $.64 is drawn from Z.
The members must then separately compute the sum of the limitation reductions. Y has limitation reductions of $0.30 in the foreign passive limitation category and $1.84 in the foreign general limitation category, yielding total limitation reduction of $2.14. Under these facts, domestic income is the only limitation category requiring a positive adjustment. Accordingly, Y's domestic income is increased by $2.14. Z has limitation reductions of $0.22 in the foreign passive limitation category and $0.64 in the foreign general limitation category, yielding total limitation reductions of $0.86. Under these facts, domestic income is the only limitation category of Z requiring a positive adjustment. Accordingly, Z's domestic income is increased by $0.86.
| Recharacterization adjustments | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 0 | + 2.14 | + 0.86 | + 3.00 |
| Foreign Passive | 0 | −0.30 | −0.22 | −0.52 |
| Foreign General | 0 | −1.84 | −0.64 | −2.48 |
These recharacterization adjustments yield the following final taxable income figures:
| Final taxable income | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 52.00 | 2.14 | 3.86 | 58.00 |
| Foreign Passive | 0 | 3.72 | 2.78 | 6.50 |
| Foreign General | 0 | 47.14 | 16.36 | 63.50 |
| Total | 52.00 | 53.00 | 23.00 | 128.00 |
(i) Facts. X, a domestic corporation, is the parent of domestic corporations Y and Z. X, Y, and Z were organized after January 1, 1987, constitute an affiliated group within the meaning of paragraph (d)(1) of this section, but do not file a consolidated return. Moreover, X has served as the sole borrower in the group and, as a result, has sustained an overall loss. The XYZ group apportions its interest expense on the basis of the fair market value of its assets. X, Y, and Z have the following assets, interest expense, and taxable income before interest expense:
| Assets | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 2,000 | 0 | 1,000 | 3,000 |
| Foreign Passive | 0 | 50 | 50 | 100 |
| Foreign General | 0 | 700 | 200 | 900 |
| Interest Expense | 140 | 0 | 0 | 140 |
| Taxable Income (pre-interest): | ||||
| Domestic | 100 | 0 | 100 | 200 |
| Foreign Passive | 0 | 5 | 5 | 10 |
| Foreign General | 0 | 70 | 35 | 105 |
(ii) Step 1: Computation of consolidated taxable income. Each member of the XYZ group apportions its interest expense according to group apportionment ratios determined under the asset method described in § 1.861-9T(g), yielding the following results:
| Apportioned interest expense | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 105.00 | 0 | 0 | 105.00 |
| Foreign Passive | 3.50 | 0 | 0 | 3.50 |
| Foreign General | 31.50 | 0 | 0 | 31.50 |
| Total | 140.00 | 0 | 0 | 140.00 |
The members of the group then compute taxable income within each category by deducting the apportioned interest expense from the amounts of pre-interest taxable income specified in the facts in paragraph (i), yielding the following results:
| Taxable income | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | −5.00 | 0 | 100.00 | 95.00 |
| Foreign Passive | −3.50 | 5.00 | 5.00 | 6.50 |
| Foreign General | −31.50 | 70.00 | 35.00 | 73.50 |
| Total | −40.00 | 75.00 | 140.00 | 175.00 |
(iii) Step 2: Loss offset adjustment. Because X has insufficient domestic income to offset the sum of the losses in the foreign limitation categories caused by apportionment, the amount of apportionment losses in each limitation category shall be recharacterized as domestic losses to the extent of taxable income of other members in the same limitation category. This is accomplished by adding to each foreign limitation categories an amount equal to the loss therein and by subtracting the sum of such foreign losses from domestic income, as follows:
| Loss offset adjustments | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | −35.00 | 0 | 0 | −35.00 |
| Foreign Passive | + 3.50 | 0 | 0 | + 3.50 |
| Foreign General | + 31.50 | 0 | 0 | + 31.50 |
These adjustments yield the following adjusted taxable income figures:
| Adjusted taxable income | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | −40 | 0 | 100 | 60 |
| Foreign Passive | 0 | 5 | 5 | 10 |
| Foreign General | 0 | 70 | 35 | 105 |
| Total | −40 | 75 | 140 | 175 |
(iv) Step 3: Determination of amount subject to recharacterization. The adjustments performed under Step 2 led to a change in the group's taxable income within each limitation category. The total loss offset adjustment column shown in paragraph (iii) above shows the net deviations between Steps 1 and 2.
(v) Step 4: Recharacterization. The loss offset adjustments yield a positive change in the foreign passive and the foreign general limitation categories. Y and Z both have income in these limitation categories. Accordingly, the income of Y and Z in each of these limitation categories must be reduced on a pro rata basis (by reference to the adjusted taxable income figures) to the extent of the positive change in each limitation category. The total positive change in the foreign passive limitation category is $3.50. The adjusted taxable income of Y in the foreign passive limitation category is $5, and the adjusted taxable income of Z in the foreign passive limitation category is $5. Therefore, $1.75 is drawn from Y and $1.75 is drawn from Z. The total positive change in the foreign general limitation category is $31.50. The adjusted taxable income of Y in the foreign general limitation category is $70, and the adjusted taxable income of Z in the foreign general limitation category is $35. Therefore, $21 is drawn from Y and $10.50 is drawn from Z.
The members must then separately compute the sum of the limitation reductions. Y has limitation reductions of $1.75 in the foreign passive limitation category and $21 in the foreign general limitation category, yielding total limitation reductions of $22.75. Under these facts, domestic income is the only limitation category requiring a positive adjustment. Accordingly, Y's domestic income is increased by $22.75. Z has limitation reductions of $1.75 in the foreign passive limitation category and $10.50 in the foreign general limitation category, yielding total limitation reductions of $12.25. Under these facts, domestic income is the only limitation category requiring a positive adjustment. Accordingly, Z's domestic income is increased by $12.25.
| Recharacterization adjustments | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | 0 | + 22.75 | + 12.25 | + 35.00 |
| Foreign Passive | 0 | −1.75 | −1.75 | −3.50 |
| Foreign General | 0 | −21.00 | −10.50 | −31.50 |
These recharacterization adjustments yield the following final taxable income figures:
| Final taxable income | X | Y | Z | Total |
|---|---|---|---|---|
| Domestic | −40.00 | 22.75 | 112.25 | 95.00 |
| Foreign Passive | 0 | 3.25 | 3.25 | 6.50 |
| Foreign General | 0 | 49.00 | 24.50 | 73.50 |
| Total | −40.00 | 75.00 | 140.00 | 175.00 |
[T.D. 8228, 53 FR 35490, Sept. 14, 1988, as amended by T.D. 8916, 65 FR 274, Jan. 3, 2001; T.D. 9456, 74 FR 38875, Aug. 4, 2009; T.D. 9571, 77 FR 2227, Jan. 17, 2012; 77 FR 9844, Feb. 21, 2012; T.D. 9676, 79 FR 41426, July 16, 2014; T.D. 9882, 84 FR 69069, Dec. 17, 2019]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 864 Definitions and special rules
- § 951 Amounts included in gross income of United States shareholders
- § 936 Repealed
- § 801 Tax imposed
- § 1504 Definitions
- § 581 Definition of bank
- § 591 Deduction for dividends paid on deposits
- § 904 Limitation on credit
- § 861 Income from sources within the United States
Regulations it cites
- § 1.861-11 Special rules for allocating and apportioning interest expense of an affiliated group of corporations.
- § 1.882-4 Allowance of deductions and credits to foreign corporations.
- § 1.1502-4 Consolidated foreign tax credit.
- § 1.861-9T Allocation and apportionment of interest expense (temporary).
- § 1.861-10T Special allocations of interest expense (temporary).
- § 1.904-5 Look-through rules as applied to controlled foreign corporations and other entities.
Cited by 10 other regulations
- § 1.861-8 Computation of taxable income from sources within the United States and from other sources and activities.
- § 1.861-8T Computation of taxable income from sources within the United States and from other sources and activities (temporary).
- § 1.861-9 Allocation and apportionment of interest expense and rules for asset-based apportionment.
- § 1.861-9T Allocation and apportionment of interest expense (temporary).
- § 1.861-10 Special allocations of interest expense.
- § 1.861-11 Special rules for allocating and apportioning interest expense of an affiliated group of corporations.
- § 1.861-12T Characterization rules and adjustments for certain assets (temporary).
- § 1.861-14 Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations.
- § 1.861-14T Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations (temporary).
- § 1.988-4 Source of gain or loss realized on a section 988 transaction.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9882 (84 FR 69069)
- Amended by T.D. 9676 (79 FR 41426)
- Amended (77 FR 9844)
- Amended by T.D. 9571 (77 FR 2227)
- Amended by T.D. 9456 (74 FR 38875)
- Amended by T.D. 8916 (65 FR 274)
- Issued by T.D. 8228 (53 FR 35490)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Determination of Sources of Income
Nearby sections
- § 1.861-9T Allocation and apportionment of interest expense (temporary).
- § 1.861-10 Special allocations of interest expense.
- § 1.861-10T Special allocations of interest expense (temporary).
- § 1.861-11 Special rules for allocating and apportioning interest expense of an affiliated group of corporations.
- § 1.861-11T Special rules for allocating and apportioning interest expense of an affiliated group of corporations (temporary).
- § 1.861-12 Characterization rules and adjustments for certain assets.
- § 1.861-12T Characterization rules and adjustments for certain assets (temporary).
- § 1.861-13 Special rules for characterization of controlled foreign corporation stock.
- § 1.861-14 Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations.