
Treasury Regulations · 26 CFR
§ 1.861-14T. Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations (temporary).
Regulation text, no changes From the eCFR, current as of October 15, 2026. The eCFR is an authoritative but unofficial editorial compilation of the Code of Federal Regulations; the official text is the annual CFR on govinfo. Compare it with this section on ecfr.gov (external site) or the official annual CFR on govinfo (external site).
Regulation under 26 U.S.C. § 861
Cite as 26 CFR § 1.861-14T
At a glance
Read from the text and its source citation. Not part of the regulation.
- Status
- In the current eCFR
- Issued
- September 14, 1988 by T.D. 8228
- Last amended
- November 12, 2020 by T.D. 9922
- Issued under
- 26 U.S.C. § 861
- Length
- 3,926 words · about 17 min to read
- Defines
- 2 terms
- Cross-references
- cites 7 Code sections and 5 regulations; cited by 3
Such adjustments shall be accomplished in accordance with the rules of § 1.861-11T(g).
1 Examples 1 and 4 of this paragraph (j) apply to taxable years beginning before January 1, 2018.
(i) Facts. P owns all of the stock of X and all of the stock of Y. P, X and Y are domestic corporations. P is a holding company for the stock of X and Y. Both X and Y manufacture and sell a product which is included in a broad product category listed in § 1.861-8(e)(3)(i). During 1988, X incurred $100,000 on research connected with that product. All of the research was performed in the United States. In 1988, the domestic sales by X of the product totalled $400,000 and the foreign sales of the product totalled $200,000; Y's domestic sales of the product totalled $200,000 and Y's foreign sales of the product totalled $200,000. In 1988, X's gross income is $300,000, of which $200,000 is from domestic sales and $100,000 is from foreign sales; Y's gross income is $200,000 of which $100,000 is from domestic sales and $100,000 is from foreign sales.
(ii) P, X and Y are affiliated corporations within the meaning of section 864(e)(5) and this section. The research expenses incurred by X are allocable to all income connected with the relevant broad category listed in § 1.861-8T(e)(3)(i). Both X and Y have gross income includible within the class of gross income related to that product category. Accordingly, the research and experimental expenses incurred by X are to be allocated and apportioned as if X and Y were a single corporation. The apportionment for 1988 is as follows:
Tentative Apportionment on the Basis of Sales| Research expenses to be apportioned | $100,000 |
| Exclusive apportionment to United States source gross income | $30,000 |
| Research expense to be apportioned on the basis of sales | $70,000 |
Apportionment of research expense to foreign source general limitation income:
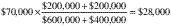
Apportionment of research expense to United States source gross income:
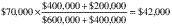
| Total apportioned deduction for research | $100,000 |
Of which—
| Apportioned to foreign source gross income | $28,000 |
| Apportioned to U.S. source gross income ($30,000 + $42,000) | $72,000 |
Research expense apportioned to foreign source gross income:
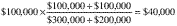
Research expense apportioned to United States income:
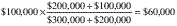
(i) Facts. P owns all of the stock of X, which owns all of the stock of Y. P, X and Y are all domestic corporations. P has incurred general training program expenses of $100,000 in 1987. Employees of P, X and Y participate in the training program. In 1987, P had United States source gross income of $200,000 and foreign source general limitation income of $200,000; X had U.S. source gross income of $100,000 and foreign source general limitation income of $100,000; and Y had U.S. source gross income of $300,000 and foreign source general limitation income of $100,000.
(ii) Analysis. P, X and Y are an affiliated group of corporations within the meaning of section 864(e)(5). The training expenses incurred by P are not definitely related solely to specific income producing activities or property of P. The employees of X and Y also participate in the training program. Thus, this expense relates to gross income generated by P, X and Y. This expense is definitely related and allocable to all of the gross income from foreign and domestic sources of P, X and Y. It is assumed that apportionment on the basis of gross income is reasonable. The apportionment of the expense is as follows:
Apportionment of $100,000 expense to foreign source general limitation income:
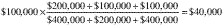
Apportionment of $100,000 expense to United States source gross income:
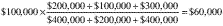
| Total apportioned expense | $100,000 |
(i) Facts. The facts are the same as in Example (2) above, except that only employees of P and X participate in the training program.
(ii) Analysis. Because only the employees of P and X participate in the training program and they perform no services for Y, the expense relates only to gross income generated by P and X. Accordingly, the $100,000 expense must be allocated and apportioned as if P and X were a single corporation. The apportionment of the $100,000 expense is as follows:
Apportionment of $100,000 expense to foreign source general limitation income:
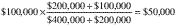
Apportionment of $100,000 expense to U.S. source gross income:
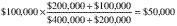
(i) Facts. P owns all of the stock of X which owns all of the stock of Y. P and X are domestic corporations; Y is a foreign corporation. In 1987 P incurred $10,000 of stewardship expenses relating to an audit of Y.
(ii) Analysis. The stewardship expenses incurred by P are not directly allocable to specific income producing activities or property of P. The expense is definitely related and allocable to dividends received or to be received by X. Accordingly, the expense of P is allocated and apportioned as if P and X were a single corporation. The expense is definitely related to dividends received or to be received by X from Y, a foreign corporation. Such dividends are foreign source general limitation income. Thus, the entire amount of the expense must be allocated to foreign source dividend income.
(i) Facts. P owns all of the stock of X which owns all of the stock of Y. P, X and Y are all domestic corporations. In 1987, P incurred $10,000 legal expense relating to the testimony of certain employees of P in connection with litigation to which Y is a party. This expense is not allocable to specific income of Y. In 1987, Y had $100,000 foreign source general limitation income and $300,000 U.S. source gross income.
(ii) Analysis. The legal expenses incurred by P are not definitely related solely to specific income producing activities or property of P. The expense is definitely related and allocable to the class of gross income which includes only gross income generated by Y. Accordingly, the expense of P is allocated and apportioned as if Y were the only member of the affiliated group, as follows:
Apportionment of legal expenses to foreign source general limitation income:
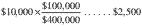
Apportionment of legal expenses to U.S. source gross income:
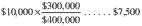
(i) Facts. P owns all of the stock of R, which owns all of the stock of F. P and R are domestic corporations, and F is a foreign sales corporation under section 922 of the Code. R and F have entered into an agreement whereby F is paid a commission with respect to sales of product A. In 1987, P had gross receipts of $1,000,000 from domestic sales of product A, and gross receipts of $1,000,000 from foreign sales of product A. R had gross receipts of $1,000,000 from domestic sales of product A, and $1,000,000 from export sales of product A. R's cost of goods sold attributable to export sales is $500,000. R has deductible expenses of $100,000 directly related to its export sales, and F has such deductible expenses of $100,000. During 1987, P incurred an expense of $100,000 for marketing studies involving the worldwide market for product A.
(ii) Analysis. P and R are an affiliated group of corporations within the meaning of section 864(e)(5) and this section. The expense incurred by P for marketing studies regarding the worldwide market for product A is an expense that is not directly related solely to the activities of P, but also to the activities of R. This expense must be allocated and apportioned under the rules of paragraph (c)(1) of this section, as if P and R were a single corporation. The expense is allocable to the class of gross income that includes all gross income generated by sales of product A. Apportionment on the basis of gross receipts is reasonable under these facts. F, a foreign corporation, is not a member of the affiliated group. However, for purposes of determining F's commission on its sales, the combined gross income of F and R must be reduced by the portion of the marketing studies expense of P that is incurred in connection with export sales involving F under the rules of paragraph (f) of this section. The computation of the combined taxable income of R and F is as follows:
| Combined Taxable Income of R and F | |
| R's gross receipts from export sales | $1,000,000 |
| R's cost of goods sold | $500,000 |
| Combined Gross Income | $500,000 |
| Less: | |
| R's other deductible expenses | $100,000 |
| F's other deductible expenses | 100,000 |
| Apportionment of P's expense: | |
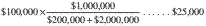
| Total | $225,000 |
| Combined Taxable Income | $275,000 |
[T.D. 8228, 53 FR 35501, Sept. 14, 1988, as amended by T.D. 8916, 65 FR 274, Jan. 3, 2001; T.D. 9143, 69 FR 44932, July 28, 2004; T.D. 9211, 70 FR 40663, July 14, 2005; T.D. 9456, 74 FR 38875, Aug. 4, 2009; T.D. 9922, 85 FR 72042, Nov. 12, 2020]
Terms defined here
Where the text says “the term … means”. Select a term to jump to its definition.
Cross-references
Computed from the citations in the text of 26 CFR.
Code sections it cites
- § 864 Definitions and special rules
- § 907 Special rules in case of foreign oil and gas income
- § 991 Taxation of a domestic international sales corporation
- § 951 Amounts included in gross income of United States shareholders
- § 482 Allocation of income and deductions among taxpayers
- § 250 Foreign-derived deduction eligible income and net CFC tested income
- § 904 Limitation on credit
Regulations it cites
- § 1.861-11T Special rules for allocating and apportioning interest expense of an affiliated group of corporations (temporary).
- § 1.861-8T Computation of taxable income from sources within the United States and from other sources and activities (temporary).
- § 1.1502-4 Consolidated foreign tax credit.
- § 1.861-14 Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations.
- § 1.861-8 Computation of taxable income from sources within the United States and from other sources and activities.
Cited by 3 other regulations
- § 1.861-8 Computation of taxable income from sources within the United States and from other sources and activities.
- § 1.861-8T Computation of taxable income from sources within the United States and from other sources and activities (temporary).
- § 1.861-14 Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations.
Amendment history
From the source citation at the end of the section, newest first. T.D. is a Treasury decision; FR is the Federal Register.
- Amended by T.D. 9922 (85 FR 72042)
- Amended by T.D. 9456 (74 FR 38875)
- Amended by T.D. 9211 (70 FR 40663)
- Amended by T.D. 9143 (69 FR 44932)
- Amended by T.D. 8916 (65 FR 274)
- Issued by T.D. 8228 (53 FR 35501)
Where it sits in 26 CFR
- Subchapter A Income tax
- Part 1 Income taxes
- Determination of Sources of Income
Nearby sections
- § 1.861-12 Characterization rules and adjustments for certain assets.
- § 1.861-12T Characterization rules and adjustments for certain assets (temporary).
- § 1.861-13 Special rules for characterization of controlled foreign corporation stock.
- § 1.861-14 Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations.
- § 1.861-14T Special rules for allocating and apportioning certain expenses (other than interest expense) of an affiliated group of corporations (temporary).
- § 1.861-15 Income from certain aircraft or vessels first leased on or before December 28, 1980.
- § 1.861-16 Income from certain craft first leased after December 28, 1980.
- § 1.861-17 Allocation and apportionment of research and experimental expenditures.
- § 1.861-18 Classification of, and source of gross income from, digital content transactions.